Posted on

First Time Buyer Schemes Leicestershire: Your 2026 Local Guide

First Time Buyer Schemes Leicestershire: Your 2026 Local Guide

You’ve spent another weekend driving through Quorn or Rothley, admiring the village charm but feeling like the price tags are drifting further out of reach. It’s a common frustration for many trying to secure their first home in Charnwood, especially when the average property price across the county has reached £297,000. Understanding the various first time buyer schemes Leicestershire offers is the first step toward moving from a rental to a home of your own.

We realise that saving for a deposit feels like a mountain to climb when the average rent in Leicester has hit £1,024 per month. This guide provides a clear, expert look at the financial support available in 2026 to help you bridge that gap. We’ll walk through everything from the First Homes scheme discounts to the details of the newly announced FTB ISA, ensuring you have the local knowledge needed to start your search with confidence. By the time you finish reading, you’ll have a practical roadmap for stepping onto the property ladder in our local villages.

Key Takeaways

  • Learn how current first time buyer schemes Leicestershire offers, such as First Homes and Shared Ownership, can help you secure a property with a smaller deposit.
  • Compare the financial advantages of new-build incentives against the character and potential to add value found in traditional Charnwood village homes.
  • Identify the often-overlooked “hidden” costs of buying, from local searches to professional surveys, to ensure your budget is realistic from the start.
  • Discover why registering with an independent agent in Rothley gives you a head start in finding the right home in competitive areas like Quorn or Mountsorrel.

Understanding the Leicestershire Property Market for First Time Buyers

The property landscape in 2026 shows that Leicestershire remains a resilient pocket of the UK market. While some regions have experienced a cooling period, our local house prices grew by 2.1% in the year to May 2026. For those looking to make their first move, understanding the term ‘first-time buyer’ involves more than just knowing you’re new to the market; it requires a grasp of the specific tools available to help you compete. With the average county price sitting at £297,000, many residents are finding that first time buyer schemes Leicestershire offers are essential for securing a home in their preferred location.

Why Leicestershire Villages are Popular

Villages such as Mountsorrel and Sileby offer a lifestyle that’s hard to replicate in more urban settings. They provide a genuine community feel while maintaining excellent transport links to both Leicester and Loughborough. This makes them ideal for young professionals who want a quiet retreat without a punishing commute. Charnwood offers a unique balance where village heritage meets modern convenience, making it the benchmark for quality of life in the East Midlands.

Market Trends to Watch in 2026

Current data shows that mortgage rates for those with a 5% deposit are averaging 4.97%. This figure directly dictates purchasing power in desirable spots like Rothley and Quorn, where demand frequently outstrips the supply of available homes. To succeed here, you need to be fully proceedable. This means having your financial ducks in a row before you even book a viewing.

Local trends often move independently of national headlines. While the broader UK news might focus on stagnation, the micro-markets in our villages remain buoyant due to high-quality school catchments and local amenities. Working with an independent agent provides a clearer picture than generic national reports. We see daily how first time buyer schemes Leicestershire has in place, such as the First Homes initiative, are helping people secure properties that might otherwise feel out of reach. Being prepared with a mortgage-in-principle and a solid deposit plan ensures you’re ready to act when the right character home or modern apartment becomes available.

Essential First Time Buyer Schemes in Charnwood and Beyond

Securing your first home in villages like Quorn or Rothley often requires a mix of disciplined saving and making the most of government initiatives. The various first time buyer schemes Leicestershire residents have access to in 2026 are specifically designed to lower entry barriers. Whether you need a reduced purchase price or a smaller deposit requirement, these programmes provide a steady hand for those looking to move out of the rental market.

The First Homes Scheme Explained

The First Homes scheme is a vital option for those living or working within the Charnwood Borough Council area. It offers new-build homes at a discount of between 30% and 50% against the market value. With the average county price for first-time purchasers sitting at £297,000, this discount can bring a high-quality home well within reach. Priority is typically given to local residents and key workers, ensuring that those who contribute to the community can afford to live here. When you eventually decide to sell, the discount is passed on to the next eligible buyer, which keeps the property affordable for future generations.

Shared Ownership Opportunities

Shared Ownership is a frequent feature of new developments in Sileby and Anstey. This scheme allows you to purchase a share of a property, usually between 25% and 75%, whilst paying a subsidised rent on the remaining portion. Because you only need a deposit based on the share you are buying, the initial financial hurdle is much lower. Over time, you have the option to “staircase”, which is the process of buying additional shares until you own the home outright. This phased approach is an excellent way to manage your long-term financial readiness without the pressure of a massive upfront cost.

The Mortgage Guarantee Scheme also remains a key tool in 2026. It allows you to secure a mortgage with just a 5% deposit on properties worth up to £600,000. With average rates for 5% deposit mortgages currently around 4.97%, this scheme is particularly useful for buyers with strong monthly incomes who haven’t yet built up a large savings pot. If you’re feeling overwhelmed by the options, you can message our team on WhatsApp for a straightforward chat about which schemes are currently active in our local villages.

New Build Incentives vs. Character Village Homes: Which is Right?

Choosing your first home in Leicestershire often comes down to a choice between the efficiency of a new build and the unique character of an older property. Both paths offer distinct advantages for those using first time buyer schemes Leicestershire provides. While a modern home in a development near Anstey offers a predictable start, a Victorian terrace in Mountsorrel might provide more long-term growth. It’s a balance of immediate ease versus future potential.

The Pros and Cons of Buying New

New build properties are frequently the primary focus for the UK Government’s First Homes Scheme, which is one of the most effective first time buyer schemes Leicestershire offers in 2026. This is because developers often set aside a percentage of new sites for local buyers at a significant discount. Beyond government support, builders often include incentives such as paying your legal fees or contributing towards your deposit. These perks can drastically reduce the amount of cash you need upfront.

Energy efficiency is another major factor. New homes usually carry an A or B Energy Performance Certificate (EPC) rating, which translates to lower monthly outgoings. You also benefit from a chain-free purchase. This means you aren’t waiting for a seller to find their next home, which can speed up the moving process by weeks. However, you often pay a “new build premium” for these benefits, and you may find that garden sizes are smaller than those found in established village streets.

The Appeal of Traditional Village Properties

If you prefer high ceilings and original fireplaces, character homes in places like Birstall or Mountsorrel remain excellent options. These properties often allow you to add value over time through modernisation. Unlike new builds, which are priced at their peak on day one, an older terrace offers the potential for capital growth if you’re willing to invest in some DIY. This makes them a favourite for those who view their first home as a project as well as a place to live.

Maintenance is a key consideration here. You’ll likely need a more detailed survey to check for damp or structural issues that aren’t a concern with new properties. Whether you’re leaning towards a modern apartment or a period cottage, obtaining a professional local valuation is crucial to ensure you aren’t overpaying in a competitive village market. This expertise helps you understand how a property’s price aligns with recent sales in the Charnwood area, giving you peace of mind before you commit.

Getting Your Finances Move-Ready for the Local Market

Before you start attending viewings in Rothley or Quorn, you need a clear picture of what you can actually afford. Financial readiness isn’t just about having a deposit; it’s about being prepared for the speed of the local market. Most sellers expect a mortgage-in-principle as proof that you’re a serious buyer. This document shows that a lender is prepared to loan you a specific amount, which gives you the confidence to make an offer the moment you find the right home.

One of the biggest advantages for those using first time buyer schemes Leicestershire offers is the current Stamp Duty relief. As of late 2026, first-time buyers pay 0% tax on properties up to £300,000. Since the average first-time buyer price in Leicester is around £212,000, many local moves are completely tax-free. If you’re looking at larger village homes between £300,001 and £500,000, you’ll pay 5% on the portion above that initial threshold. Our mortgage calculator is a helpful starting tool to help you model these costs against your monthly income.

Calculating Your True Budget

It’s easy to focus on the purchase price and forget the secondary costs. You’ll need to budget for conveyancing fees, professional surveys, and local searches, which look for issues like planning restrictions or environmental risks. These secondary expenses can add several thousand pounds to your total bill. We suggest speaking to a local mortgage advisor early in the process to ensure your savings cover both the deposit and the move itself. For a detailed breakdown, see our guide on The True Cost of Moving House in Leicestershire: A 2026 Resource Guide.

The Role of Professional Valuations

Understanding what properties are actually selling for is better than relying on asking prices. In competitive areas like Mountsorrel or Birstall, an expert assessment helps you avoid overpaying during a bidding war. We use deep-rooted local knowledge to provide clarity on market values, ensuring your offer is both fair and likely to be accepted. If you’re comparing different villages, you might find our insights on How Much Is My House Worth in Syston? A 2026 Guide to Property Values useful for understanding price variations across Charnwood.

Message us on WhatsApp to discuss your budget

First Time Buyer Schemes Leicestershire: Your 2026 Local Guide

Finding Your First Home with Taylors Estate Agency

Buying your first home is a milestone that shouldn’t feel like a cold transaction. While national portals give you a broad overview, they often miss the local nuances that truly matter. By registering with an independent agent in Rothley, you gain access to insights that automated alerts simply cannot provide. We understand exactly how the various first time buyer schemes Leicestershire offers apply to specific developments and character streets across our villages.

Our agency was established in 1992. Over these three decades, we’ve seen every type of market shift. This longevity means we aren’t just selling houses; we’re helping our neighbours move. For a first-time buyer, this deep experience acts as a steady hand during what can be an anxious process. We provide the dedicated attention of a boutique office, ensuring you never feel like just another number on a spreadsheet.

Our Local Expertise

Our team possesses deep-rooted knowledge of the Charnwood area, from the vibrant centre of Quorn to the quiet lanes of Thurcaston and Woodhouse Eaves. We know which areas offer the best value for those just starting out. We also know which streets are likely to see steady long-term growth. This local proficiency is vital when you’re deciding between a modern build or a period terrace. If you’re also thinking about the long-term, you might find our guide on Selling Your Property: A Guide to Choosing the Best Estate Agents in Leicestershire helpful for understanding how we support our clients throughout their entire property journey.

Next Steps for Your Search

The most effective way to find your perfect home is to be proactive. We recommend registering for our tailored property alerts. This ensures you’re among the first to know when a home matching your specific criteria becomes available. Unlike corporate brands that rely on generic call centres, our team in Rothley handles your search personally. We arrange viewings that fit around your busy schedule and provide honest, professional guidance at every stage.

We believe in transparency and clear communication. If you’re ready to start your search or just want to discuss how first time buyer schemes Leicestershire has available could work for you, our doors are always open. Get in touch with Taylors Estate Agency today for a friendly, no-obligation conversation about your future home.

Start Your Journey to Homeownership in Charnwood

Stepping onto the property ladder is a significant life event that requires both financial preparation and local insight. By understanding the current relief available and the nuances of our village markets, you can move forward with confidence. Whether you prefer a high-efficiency new build in Anstey or a period terrace in Mountsorrel, utilising the first time buyer schemes Leicestershire provides is a practical way to bridge the affordability gap and secure your future.

As independent Charnwood specialists established in 1992, Taylors Estate Agency is here to offer a steady hand throughout your search. We provide expert local valuations and honest advice that national corporate brands often lack. Our team understands the emotional and financial weight of this journey, and we are committed to helping you find a home that fits your lifestyle and your budget. We pride ourselves on being a reliable pillar of the community, offering transparency at every stage of the process.

Get in touch with the team at Taylors Estate Agency

We look forward to helping you find your first home in our beautiful Leicestershire villages and making your move as smooth as possible.

Frequently Asked Questions

What is the First Homes scheme and is it available in Leicestershire?

The First Homes scheme provides a discount of 30% to 50% on new-build properties for local buyers and key workers. It is active in 2026 across the Charnwood Borough Council area, including developments in Anstey and Sileby. To qualify, you must be a first-time buyer with a combined income under £80,000. The property price is capped at £250,000 after the discount, making it one of the most effective first time buyer schemes Leicestershire offers for those working locally.

How much deposit do I realistically need for a house in Charnwood?

Most buyers in Charnwood aim for a 5% deposit, which is supported by the government’s Mortgage Guarantee Scheme. With the average Leicestershire property price for first-time purchasers currently at £297,000, you would realistically need around £14,850. However, having a 10% or 15% deposit often provides access to more competitive interest rates. We recommend using our mortgage calculator early in your search to see how different deposit levels affect your monthly repayments and overall purchasing power.

Do first-time buyers still get Stamp Duty relief in 2026?

Yes, first-time buyers in 2026 still benefit from significant Stamp Duty Land Tax (SDLT) relief. You pay 0% tax on the first £300,000 of your home’s purchase price. For properties priced between £300,001 and £500,000, a 5% rate applies only to the amount above the £300,000 threshold. Since the average price for a first-time buyer in Leicester is approximately £212,000, the vast majority of first time buyer schemes Leicestershire residents use result in a tax-free move.

Can I buy a traditional cottage in Rothley using a government scheme?

While schemes like First Homes are restricted to new builds, you can certainly buy a traditional cottage in Rothley using other support. The Lifetime ISA (LISA) and the new FTB ISA allow you to use government bonuses for any property up to £450,000. Additionally, the Mortgage Guarantee Scheme applies to older character homes, helping you secure a characterful village property with just a 5% deposit, provided the property meets your lender’s specific criteria.

What are the best Leicestershire villages for affordable first-time homes?

Sileby and Syston are currently top choices for those seeking a balance between village amenities and affordability. These areas often have a wider range of terrace homes and modern apartments that fall within first-time buyer price brackets. Birstall and Mountsorrel also offer competitive entry points compared to the higher premiums found in Quorn or Rothley. Focusing on these villages allows you to get more for your money whilst remaining within the desirable Charnwood area.

How does Shared Ownership work in the Leicester area?

Shared Ownership allows you to buy a share of a property, typically between 10% and 75%, and pay rent on the remaining portion to a housing association. It is a popular way to enter the market in new developments across Sileby and Anstey. You only need a mortgage for the share you are purchasing, which significantly reduces the required upfront deposit. Over time, you have the option to increase your ownership through a process known as staircasing.

Should I buy a new build or an older house as my first property?

The choice depends on whether you prioritise energy efficiency or the potential to add value. New builds offer modern insulation, builder incentives, and no upward chain, which can make the move much faster. Older houses in villages like Mountsorrel often have larger gardens and more character. Traditional homes also offer the chance to build equity through modernisation, whereas new builds are typically priced at their peak from the day you move in.

What additional costs should I prepare for besides the deposit?

You should budget for several secondary expenses beyond your deposit. Conveyancing fees, professional surveys, and local searches typically add between £2,000 and £3,500 to your total costs. You will also need to consider removal company fees and initial buildings insurance. Preparing for these outgoings early ensures your move doesn’t stall. We always advise buyers to keep a small contingency fund for unexpected repairs if they are moving into a character village property.
Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

How Much Can I Borrow for a UK Mortgage? 2026 Guide

How Much Can I Borrow for a UK Mortgage? 2026 Guide

Imagine finding your perfect detached home in Rothley, only to discover that the bank’s “yes” is £50,000 short of the asking price. It’s a disheartening scenario that many buyers across Leicestershire face, particularly as lender criteria have tightened following the interest rate shifts of early 2026. You might feel overwhelmed by conflicting advice, wondering exactly how much can I borrow mortgage UK banks will actually commit to in today’s market.

We understand that behind every spreadsheet and salary multiple is a real family looking for stability. Whether you’re eyeing a character cottage in Quorn or a modern semi in Birstall, having a realistic figure is the only way to search with confidence. This guide will show you exactly how lenders calculate your borrowing power, moving beyond simple multiples to look at true affordability.

We’ll explore how the current 3.75% base rate influences your monthly repayments and explain the practical steps you can take to improve your “mortgageability.” By the end, you’ll have a clear picture of your budget, helping you move from browsing Rightmove to booking viewings in Charnwood with absolute peace of mind.

Key Takeaways

  • Learn why the 4.5x income multiple is only a baseline and how lenders assess your true affordability against 2026 interest rates.
  • Discover exactly how much can I borrow mortgage UK lenders will offer by understanding how they treat bonuses, commissions, and self-employed earnings.
  • Identify the “Big Three” financial pillars—deposit, credit health, and outgoings—that dictate your maximum loan-to-value ratio.
  • Get practical advice on improving your mortgageability through simple steps like electoral roll registration and managing monthly commitments.
  • Find out how your borrowing power aligns with current property values in Charnwood villages to help you target the right homes in your search.

Mortgage Affordability: Understanding the Basics of UK Borrowing

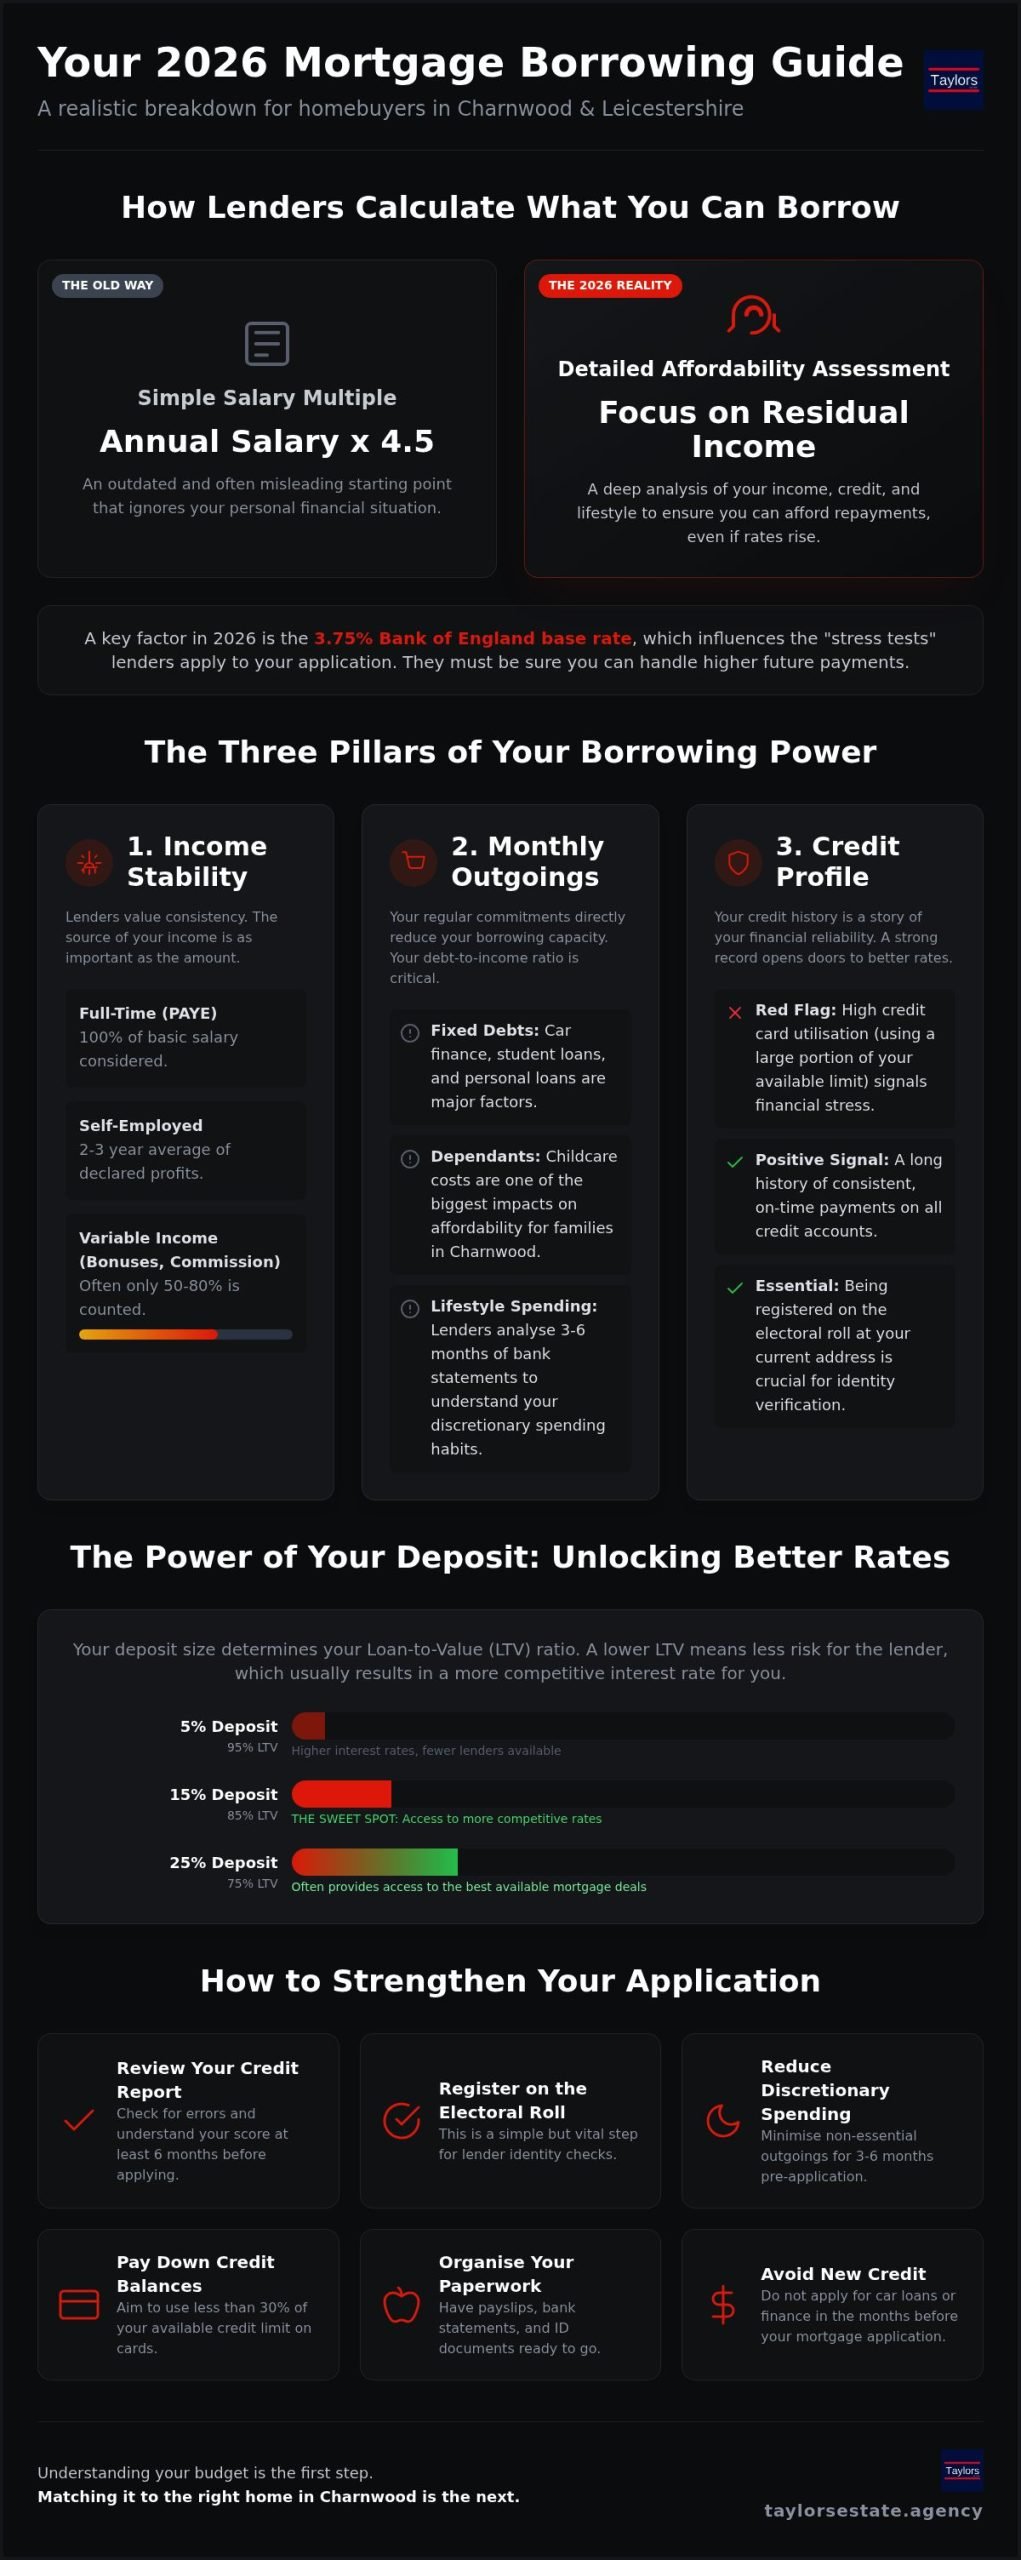
Mortgage borrowing is essentially the total capital a lender is willing to advance you, based on their detailed assessment of the risk involved. While it’s tempting to focus solely on the final figure, the process is rooted in Mortgage Affordability: Understanding the Basics, where banks balance your aspirations against financial reality. Most high street lenders use a standard “income multiple” as their starting point, which typically sits at 4.5 times your annual gross salary. This gives you a baseline for answering the question: how much can I borrow mortgage UK wide?

There’s a vital distinction between “borrowing power” and “affordability.” Borrowing power is the maximum amount a bank might theoretically offer you, whereas affordability is what you can comfortably pay back without sacrificing your lifestyle in villages like Mountsorrel or Quorn. An Agreement in Principle is the formal start of your buying journey, providing a document from a lender that states how much they’re prepared to lend you in theory.

The Role of Income Multiples in 2026

In 2026, these multiples aren’t set in stone. For joint applications, lenders usually combine your incomes before applying the multiple, which can significantly boost your budget for larger homes in Rothley. High earners, typically those with a salary over £75,000, or professionals like doctors and lawyers, might access enhanced multiples of 5 or even 5.5 times their income. With the Bank of England base rate currently at 3.75%, lenders are being more precise. They’re balancing these higher multiples against the reality of monthly repayments to ensure borrowers aren’t overextending themselves.

Gross Income vs Net Affordability

Lenders have moved far beyond just looking at your headline salary. They now scrutinise your disposable income, which is what remains after your essential outgoings, such as childcare, transport, and existing debts. This is where the stress test comes into play. Banks calculate whether you could still afford your mortgage if interest rates were to rise significantly above the current averages. They use 2026 cost-of-living data to ensure that your dream move to Charnwood remains sustainable even if your daily expenses increase. Understanding this shift from gross to net is crucial when calculating how much can I borrow mortgage UK lenders will actually approve.

Key Factors That Influence Your Maximum Mortgage Limit

While your salary provides the foundation, lenders look at three main pillars to determine your final limit: your deposit size, your credit history, and your monthly outgoings. These factors often carry more weight than the headline income multiple when calculating how much can I borrow mortgage UK lenders will offer. Your Loan-to-Value (LTV) ratio is particularly significant; it represents the percentage of the property value you are borrowing. Lower LTVs usually result in more competitive interest rates because the lender’s risk is reduced.

Age and the length of the mortgage term also play a role. A longer term can lower monthly payments but increases the total interest paid; meanwhile, lenders may cap terms that extend past your planned retirement age. To ensure a smooth application, maintaining a clean credit report for at least six months prior is vital. This means avoiding new credit applications or missed payments. You can follow the Official government guide to buying a home to help prepare your documentation and understand the legal steps involved.

The Power of the Deposit

For many buyers in Charnwood, a 10% or 15% deposit represents the “sweet spot” where interest rates become significantly more attractive. Larger deposits act as a safety net for the bank, which often leads to a higher borrowing ceiling. If you are already a homeowner in Leicestershire, the equity in your current property often serves as your primary deposit. Getting an accurate valuation is the first step to understanding how much equity you can bring to your next move, especially if you are moving between villages like Woodhouse Eaves or Sileby.

Debt-to-Income Ratios and Monthly Commitments

Lenders are increasingly sensitive to your debt-to-income ratio. Monthly commitments like car finance, student loans, and credit card balances effectively reduce the amount of income available for mortgage repayments. In 2026, childcare costs are a major factor in affordability checks, sometimes carrying as much weight as a significant loan. This is why banks scrutinise your bank statements so closely.

Organising your finances at least three months before you apply is essential. This includes clearing small balances and ensuring your bank statements reflect a stable financial pattern. If you’re unsure how your current commitments might affect your property search in Rothley or Birstall, get in touch with our team for some informal local guidance on preparing your finances for a move.

Beyond Salary: How Lenders Calculate Your True Borrowing Power

Lenders look far beyond your basic pay slip to understand your financial capacity. For many professionals across Leicestershire, a significant portion of their earnings comes from variable income such as bonuses, commission, or overtime. While these sums are vital to your household budget, banks rarely treat them with the same weight as a guaranteed salary. Most lenders will take a two-year average of these payments or apply a “haircut,” often only counting 50% of the total towards your borrowing limit. Understanding these nuances is a key part of answering how much can I borrow mortgage UK lenders will actually support.

Other income sources like pensions, dividends, or court-ordered maintenance payments can also be included, provided they are stable and documented. It’s also worth remembering that every lender has a different appetite for risk. A rejection from one high-street bank doesn’t mean your plans are over; it simply means your specific income structure didn’t fit their particular model. As local agents, we often see buyers succeed with a secondary lender after a “No” from their primary bank.

Self-Employed and Contractor Criteria

For the many business owners and freelancers in Rothley and Mountsorrel, the standard requirement is usually two years of certified accounts or SA302s. Lenders typically average your net profit over the last two years to find a stable figure. If your profits have recently increased, they might still use the lower figure to remain cautious. However, contractors in specific fields like IT or medicine are often treated differently. Some specialist lenders will calculate borrowing based on your daily rate rather than your annual accounts, which can significantly boost your budget for a home in Charnwood.

Joint Applications and Booster Options

Combining incomes is the most effective way to reach the price brackets found in villages like Quorn or Woodhouse Eaves. If a joint application still doesn’t provide enough leverage, a “Joint Borrower Sole Proprietor” (JBSP) mortgage might be an option. This allows a parent or family member to add their income to the mortgage to help with affordability without being named on the property deeds. Modern lenders are also very comfortable with gifted deposits from family, provided the funds are a genuine gift and not a loan. These “booster” options can be the difference between a compromise and finding your ideal home.

How to Increase Your Borrowing Potential Before You Buy

Your borrowing limit isn’t a static number. It’s a reflection of your financial health at a specific moment in time. By taking proactive steps in the months leading up to your application, you can often influence the final figure a lender offers. Understanding how much can I borrow mortgage UK wide involves looking at your profile through a bank’s eyes. They want to see stability, predictability, and a clear ability to manage debt.

Being on the electoral roll at your current Leicestershire address is one of the simplest yet most effective ways to boost your internal credit score. Whether you’re renting in Birstall or living with family in Anstey, this registration provides proof of address that lenders use for identity checks. We also advise against making major career changes or large purchases, such as a new car on finance, in the six months before you apply. These shifts can signal instability or reduce your disposable income, which directly impacts your affordability.

  • Register on the electoral roll at your current home address.
  • Avoid new credit applications for at least six months before applying.
  • Keep your credit card balances below 30% of their available limits.
  • Maintain a stable employment history during the application window.
  • Use a professional mortgage broker to access niche lenders who specialise in your specific income type.

Credit Score Optimisation

Fixing errors on your credit report is a vital task while you’re planning your move to villages like Cropston or Thurcaston. Even a small mistake in a past address or a wrongly recorded late payment can cause delays. Interestingly, having too much unused credit can sometimes be as detrimental as having too little. Lenders worry that you could suddenly run up large debts after the mortgage is granted. When checking your score, always use “soft” searches where possible, as “hard” searches leave a footprint that can temporarily lower your rating if too many occur in a short period.

Reducing Outgoings to Boost Affordability

Lenders perform a deep dive into your bank statements to identify discretionary spending. They may flag frequent high-value luxury purchases or recurring subscription services that you no longer use. Closing dormant store cards and cancelling unnecessary memberships can help clean up your financial profile. A small reduction in monthly debt can lead to a surprisingly large increase in the capital lent. For example, clearing a £50 monthly credit card payment could potentially increase your total mortgage offer by several thousand pounds, bringing that dream home in Rothley within reach.

Get in touch for a local perspective on your moving plans

How Much Can I Borrow for a UK Mortgage? 2026 Guide

Applying Borrowing Limits to the Leicestershire Property Market

Understanding how much can I borrow mortgage UK wide is only half the battle; the other half is knowing how that figure translates into a real-world home in Charnwood. Local market resilience is evident, with house prices in the area rising by 3.8% in the year to June 2026. This growth outpaced the wider East Midlands average, meaning your borrowing power needs to be matched carefully with current village values. In high-demand areas like Rothley or Quorn, where average sold prices sit between £393,000 and £425,000, being mortgage-ready is essential to securing a property against competing bids.

One challenge many buyers face is the “lending gap.” This occurs if a lender’s surveyor values a property lower than your agreed purchase price. Because banks only lend based on their own valuation, you may need to bridge this gap with extra cash. At Taylors Estate Agency, we provide integrated financial tools, including our in-house mortgage calculator, to help you model these scenarios before they happen. We aim to ensure that your financial planning is rooted in the reality of the Leicestershire market, rather than just a theoretical salary multiple.

What Your Borrowing Power Buys in Charnwood

Location significantly dictates what your budget can achieve. For example, a borrowing limit of £250,000 might secure a modern three-bedroom semi-detached home in Syston or Birstall. However, in a premium village like Woodhouse Eaves, that same figure might only be the starting point for a smaller cottage or a high-end apartment. It is also vital to look beyond the purchase price. You must budget for “hidden” costs such as removals and the 2026 Stamp Duty thresholds to ensure your move remains affordable. For a detailed breakdown of these expenses, see The True Cost of Moving House in Leicestershire: A 2026 Resource Guide.

Expert Valuations as a Financial Tool

If you are a homeowner in Rothley or Mountsorrel looking to move up the ladder, an accurate valuation of your current property is the cornerstone of your search. Knowing your equity is the “second half” of the equation when asking how much can I borrow mortgage UK lenders will permit. Taylors Estate Agency helps coordinate the entire chain by understanding both sides of the affordability equation; this reduces the risk of a sale falling through due to financial surprises. If you are starting your journey, our guide on How Much Is My House Worth in Syston? A 2026 Guide to Property Values offers a great starting point for local homeowners.

Your borrowing capacity is far more than a simple calculation on a bank’s website. As we have explored, the final answer to how much can I borrow mortgage UK lenders will support depends on your deposit, your outgoings, and the specific property you have your eye on. In a resilient market like Charnwood, having these figures confirmed is what allows you to move from browsing to making a successful offer.

Since 1992, Taylors Estate Agency has acted as a trusted local guide for thousands of families across Leicestershire. We believe that clarity is the best cure for anxiety, and our team is here to provide the personalised support you need to understand both your mortgageability and your current home’s value. If you’re thinking about moving in Charnwood and would like honest, local advice, please reach out.

our team would be happy to help

Finding your ideal home in a village like Rothley or Quorn should be an exciting milestone. With the right financial foundation and expert local knowledge, you can approach your next move with absolute confidence.

Frequently Asked Questions

How many times my salary can I borrow for a mortgage in 2026?

Most lenders use a baseline of 4.5 times your annual salary, though this can increase for specific applicants. High earners with a combined income exceeding £150,000 may access multiples as high as 6.5 times through certain banks. When asking how much can I borrow mortgage UK lenders will ultimately decide based on your debt-to-income ratio. This ensures that your monthly repayments remain sustainable even if your circumstances change after moving to villages like Quorn or Sileby.

Does my student loan affect how much I can borrow for a mortgage?

Yes, your student loan repayments are considered a monthly outgoing that reduces your overall disposable income. Lenders don’t look at the total debt balance, but they do factor the monthly deduction into their affordability calculators. This means a higher student loan payment could slightly lower the maximum capital a bank is willing to advance. It’s a common factor for many young professionals looking at properties in Birstall or Syston.

Can I get a mortgage with a 5% deposit in Leicestershire?

Yes, 5% deposit mortgages are available in Leicestershire, provided you meet the lender’s credit and affordability criteria. These 95% Loan-to-Value (LTV) products are popular with first-time buyers in areas like Mountsorrel or Anstey. However, you’ll usually find that interest rates are higher for smaller deposits. Saving a 10% or 15% deposit often provides access to more competitive deals, which can significantly lower your monthly mortgage costs over the long term.

How do high interest rates in 2026 impact my borrowing power?

High interest rates directly reduce your borrowing power because they increase the cost of monthly repayments. With the Bank of England base rate at 3.75% in 2026, lenders apply “stress tests” to see if you could afford payments if rates rose even further. This cautious approach means you might be offered a lower total amount than you would have been in a lower-rate environment. It makes accurate budgeting for your Charnwood home search even more critical.

Will being self-employed reduce the amount I can borrow?

Being self-employed doesn’t automatically reduce your borrowing limit, but lenders calculate your income differently. Most banks will average your net profits from the last two years of certified accounts to determine a stable figure. If your profits are fluctuating, they’ll often use the lower year as a precaution. Providing clear SA302 documents is essential for business owners in Rothley to demonstrate they have the consistent income needed to support a mortgage application.

What outgoings do lenders look at during affordability checks?

Lenders scrutinise a wide range of essential and discretionary outgoings during their deep dive into your bank statements. They specifically look at:

  • Childcare and school fees
  • Existing loans and car finance
  • Credit card and store card balances
  • Regular pension contributions
  • Essential living costs like utilities and groceries

Reducing these commitments three months before applying can help maximise the figure you see when calculating how much can I borrow mortgage UK lenders will agree to.

Does a higher credit score always mean I can borrow more money?

Not necessarily, as a high credit score primarily affects your eligibility for a mortgage and the interest rates you’re offered. While a perfect score makes you a more attractive borrower, the actual amount you can borrow is dictated by your income and outgoings. You could have an excellent credit rating but still be limited by a high debt-to-income ratio. Both factors must work in harmony to secure the best possible mortgage for your move.

How long does a mortgage offer stay valid once I find a house in Rothley?

Most mortgage offers are valid for between three and six months from the date they are issued. This gives you time to complete the legal process once you’ve found your ideal home in Rothley or Barrow upon Soar. If the purchase takes longer than expected, you may need to apply for an extension or provide updated bank statements. It’s always best to keep your lender informed of any delays in the conveyancing process to avoid your offer expiring.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

Steps to Buying a House in Leicestershire: A Local Expert’s 2026 Guide

Steps to Buying a House in Leicestershire: A Local Expert’s 2026 Guide

Imagine finding the perfect Victorian cottage in Rothley or Quorn, only to lose out because you weren’t prepared for the competitive pace of the 2026 market. It’s a common worry for many buyers who feel overwhelmed by fluctuating mortgage rates and the fear of being gazumped just as they’ve set their hearts on a property. Understanding the specific steps to buying a house in Leicestershire is the best way to move from uncertainty to a successful, stress-free completion.

We know that the financial side can be just as daunting as the search itself, especially with the average county house price sitting at £297,000 and the Bank of England base rate currently at 3.75%. You need a clear roadmap that accounts for every cost, from RICS surveys to the final legal fees. This guide provides a comprehensive walkthrough of the local property journey, designed to help you find a home in a desirable Charnwood village. We will cover everything from initial budgeting and local market trends to the final exchange of contracts, giving you the expert insight needed to collect your keys with confidence.

Key Takeaways

  • Calculate your total budget by including essential costs like Stamp Duty and legal fees to ensure you are financially prepared before starting your search.
  • Research specific Charnwood villages such as Rothley and Mountsorrel to find a community that aligns with your lifestyle and property needs.
  • Follow the essential steps to buying a house in Leicestershire by using recent sold prices to inform a competitive and realistic opening offer.
  • Protect your investment by choosing the correct RICS survey level based on the age and condition of your chosen property rather than relying solely on a lender valuation.
  • Coordinate closely with your solicitor to manage the exchange of contracts and deposit transfers for a predictable and successful completion day.

Financial Preparation and Establishing Your Budget

Getting your finances in order is the most critical of the early steps to buying a house in Leicestershire. It’s about more than just the deposit. You need to understand how your lifestyle fits into the local market. With the average house price in the county currently around £297,000, having a clear picture of your total capital is essential. Look at your savings. Decide exactly how much you can comfortably put down. A larger deposit often opens doors to more competitive mortgage rates, which is particularly important as the Bank of England base rate sits at 3.75% in late 2026.

Calculating the True Cost of Your Move

Many buyers focus solely on the purchase price, but the additional costs can quickly add up. In Charnwood, you’ll need to budget for Stamp Duty Land Tax. For standard buyers, this starts at 2% for properties over £125,000. For a £300,000 home, this means a £3,750 bill. You should also account for legal fees. These typically range from £1,340 to £1,567 for a standard freehold purchase. You can find a detailed breakdown in our cost of moving house leicestershire guide. To Learn more about Leicestershire and the demographics of its various villages, checking regional data is a sensible way to see which areas might better suit your budget. Don’t forget to set aside a contingency fund. Even well-maintained homes in villages like Birstall or Mountsorrel might need minor repairs or a fresh coat of paint.

The Importance of a Mortgage in Principle

Before you start booking viewings in popular spots like Rothley or Quorn, you need a Mortgage in Principle (MIP). This document isn’t a formal offer. It shows sellers and agents that a lender is prepared to give you the funds. In a competitive market where properties in Woodhouse Eaves move quickly, having an MIP makes you a serious contender. It strengthens your hand during negotiations. The seller knows you’ve already done the legwork. Use a mortgage calculator early on to see what your monthly repayments might look like at current rates. For the best 2026 deals, speak to an independent mortgage adviser. They can scan the whole market rather than just one bank’s products. This proactive approach is one of the smartest steps to buying a house in Leicestershire, ensuring you don’t fall in love with a home that’s out of reach.

Finding Your Ideal Home in Leicestershire’s Villages

Once your budget is firm, the next of the steps to buying a house in Leicestershire involves narrowing down your search to specific communities. Start by defining your non-negotiables. Consider whether you need to be within walking distance of local primary schools or if proximity to the A6 for commuting is essential. Separating these from “nice-to-haves”, like a utility room or a kitchen island, ensures you don’t get distracted by aesthetic features that can be added later.

Many of the finest homes in Charnwood sell before they ever reach the national portals. Registering your specific requirements with independent estate agents leicestershire gives you a significant advantage. Local experts often hold information about properties in Rothley or Birstall that are just days away from being listed. If you’re struggling to decide between two areas, you can message us for a local’s perspective on current village demand.

Shortlisting Your Target Locations

Charnwood offers a diverse range of characters. You might prefer the bustling community feel and local shops in Anstey or the historic, elevated views in Mountsorrel. Rothley and Woodhouse Eaves remain highly sought after for their stunning period cottages and proximity to Bradgate Park. Always visit your shortlisted villages at various times. A quiet street on a Saturday afternoon might become a busy cut-through during the weekday commute toward Leicester or Loughborough.

The Art of the Property Viewing

During a viewing, look past the staging and decor to assess the building’s bones. Check the windows for draughts and look at the ceiling corners for any signs of historic leaks. It’s helpful to bring a checklist of questions regarding the property’s maintenance history. In 2026, checking the age and service record of the boiler is a vital priority because replacing an inefficient system is a major expense that can impact your move-in budget. Assessing the loft insulation and wall thickness will also give you a better idea of future running costs.

Finding the right home is an exciting milestone, but the transition from viewing a property to securing it requires a strategic approach. This is where the practical steps to buying a house in Leicestershire become high-stakes. You need to base your opening offer on data rather than emotion. Before picking up the phone, check recent sold prices on HM Land Registry for similar properties in the same street. If a house in Mountsorrel or Sileby is listed at £300,000 but comparable homes sold for £285,000 recently, your offer should reflect that reality whilst remaining respectful of the seller’s expectations.

When you communicate your offer to the estate agent, be explicit about your buying position. Sellers in 2026 are often looking for the path of least resistance. If you’re a first-time buyer, chain-free, or have a Mortgage in Principle ready, say so. These details can make your offer more attractive than a higher bid from someone who hasn’t yet sold their own home. Once the offer is accepted, the “sold subject to contract” phase begins, and the focus shifts to the legal work.

Negotiating Your Purchase

Negotiation is a delicate balance. In competitive village markets like Quorn or Rothley, you might face a counter-offer. It’s vital to stay calm and keep a level head. Remember that the estate agent acts as a professional mediator. Their goal is to facilitate a successful sale for their client whilst ensuring the buyer is committed. Be prepared to move slightly on price if the property ticks every box, but always keep your maximum budget and the current 1.6% national house price growth in mind to avoid overextending yourself.

Understanding the Conveyancing Journey

As soon as your offer is accepted, you must formally instruct a solicitor to begin the conveyancing work. This is one of the most technical steps to buying a house in Leicestershire. Your solicitor will conduct local authority searches, check property titles, and raise specific enquiries with the seller’s legal team. They look for anything that might affect the property’s value or your future use of it, such as planned developments or boundary issues.

We always recommend choosing a local solicitor who knows the Charnwood area. They’ll have established links with local councils and a better understanding of regional land issues than a national firm. To keep the process moving, aim to respond to any paperwork or enquiries on the day you receive them. Small delays in signing documents can ripple through a property chain, so staying proactive is the best way to ensure you reach the finish line without unnecessary stress.

Surveys, Valuations, and Finalising the Mortgage

Once the legal wheels are turning, you must focus on the physical condition of your future home. This is often where the most anxiety lies in the steps to buying a house in Leicestershire. It’s vital to distinguish between a lender’s valuation and a private RICS survey. A valuation is a basic check to ensure the property is worth the loan amount; it doesn’t protect you from hidden structural issues. For that, you need an independent professional to inspect the building thoroughly. This step ensures you aren’t buying a “money pit” that could derail your finances later.

Selecting the Right Survey for Your Home

Choosing the correct survey level depends largely on the age and construction of the property. A RICS Level 2 survey is usually sufficient for conventional houses built after 1900. However, if you’re buying one of the historic granite cottages in Mountsorrel or Quorn, a Level 3 Building Survey is a wiser investment. These older properties can suffer from specific issues like “granite damp,” where the dense local stone prevents moisture from escaping if the wrong mortar has been used. If your surveyor identifies significant red flags, such as subsidence or rising damp, you can use the report to renegotiate the purchase price. Alternatively, you might ask the seller to carry out essential repairs before you proceed to exchange.

Securing Your Formal Mortgage Offer

With a satisfactory valuation in hand, your lender will move from a Mortgage in Principle to a formal binding offer. This document confirms they’ll provide the funds on the agreed terms. Sometimes, a lender’s valuation comes in lower than your agreed purchase price, which is known as a down-valuation. This can be a hurdle. It’s often resolved by providing further evidence of local sold prices or by increasing your deposit to bridge the gap. Before you reach the exchange of contracts, ensure your building insurance is ready to start from the exchange date. Most mortgage lenders make this a mandatory condition to protect their interest in the property from the moment you’re legally committed.

Ask us for a list of recommended local surveyors

Steps to Buying a House in Leicestershire: A Local Expert’s 2026 Guide

Exchange, Completion, and Moving Day

Reaching the final stage of your property journey is both exhilarating and demanding. After weeks of legal checks and financial preparation, the transition from “sold subject to contract” to owning the property happens in two distinct steps. First, you’ll sign the final contract and transfer your deposit, typically 10% of the purchase price, to your solicitor. This preparation ensures everything is ready for the exchange, which is the most definitive of the steps to buying a house in Leicestershire. Until this moment, either party can withdraw without significant financial penalty, but once contracts are exchanged, the deal is legally binding.

During this period, you’ll also agree on a completion date that suits everyone in the chain. It’s the time to finalise your removal plans and notify utility companies, including water, gas, and electricity providers, of your upcoming move. Ensuring your broadband is booked for installation in your new home in Anstey or Birstall early can save you from weeks without a connection after you move in.

The Significance of the Exchange of Contracts

The exchange of contracts is the point of no return. Your solicitor will carry out a final check of the chain and, once satisfied, will formally exchange with the seller’s legal team. This process locks in the price and the date. Since you’re now legally committed, you’ll need to ensure your buildings insurance is active. The logistics of transferring your deposit funds must be handled securely, usually via a bank transfer. Once the solicitors confirm the exchange is complete, you can finally book your removals with total certainty that the move is going ahead.

Completion Day: What to Expect

Completion day is when the remaining purchase funds are transferred through the banking system. This usually happens on a weekday to ensure the CHAPS payments can clear. You’ll likely spend the morning packed and ready, waiting for the call from your solicitor or agent. In Leicestershire villages, there’s a long standing tradition of “handover etiquette” that we always encourage. Leaving a folder with boiler instructions, window key locations, and a quick note about which day the bins go out in Sileby or Quorn makes a world of difference for the new owners.

Once the seller’s solicitor confirms they’ve received the full balance, the keys can be released. You can then head over to our Rothley office to collect your keys and begin your life in your new home. It’s a moment of great pride for us to see our clients reach this milestone with a smile.

Speak to our team for honest local advice on your next move

Securing Your Future in the Charnwood Villages

Owning a home in one of Leicestershire’s historic villages is a rewarding milestone. By following these practical steps to buying a house in Leicestershire, you’ve moved from initial budgeting to a clear understanding of the legal and physical checks required for a successful purchase. Success in the 2026 market depends on thorough preparation, from securing a Mortgage in Principle early to selecting the correct RICS survey for a period cottage.

Since 1992, Taylors Estate Agency has acted as a trusted guide for buyers across Charnwood. As independent village specialists, we provide the steady hand and local proficiency needed to stay ahead of the competition. We believe that property is about people and communities. Our team is here to ensure your journey to collecting your keys is as smooth and transparent as possible.

Message us on WhatsApp for a friendly chat about your move

We look forward to helping you find your perfect place in our local community.

Frequently Asked Questions

How long does it typically take to buy a house in Leicestershire?

Buying a house in Leicestershire typically takes between 12 and 16 weeks from the moment your offer is accepted. This timeline depends heavily on the length of the property chain and the efficiency of the solicitors involved. If you’re a first-time buyer or purchasing a vacant property, the process can be quicker. However, complex chains involving multiple sales in villages like Anstey or Sileby can sometimes extend the journey beyond four months.

Do I need a local solicitor, or can I use an online conveyancer?

Whilst you can use an online conveyancer, we strongly recommend choosing a local solicitor who understands the Charnwood area. Local firms have established relationships with Charnwood Borough Council and understand regional land issues that national call centres might miss. Although Taylors doesn’t provide in-house conveyancing, we’ve seen that transactions often proceed more smoothly when legal teams can communicate effectively with local agents who have deep-rooted knowledge of the county.

What are the most popular villages for families in Charnwood?

Families often gravitate towards Rothley, Quorn, and Mountsorrel due to their excellent local schools and community facilities. These villages offer a balance of rural charm and practical amenities, such as local parks and reliable transport links via the A6. Anstey and Barrow upon Soar are also popular choices, providing a variety of property types from modern developments to traditional family homes that cater to different budgets and lifestyle requirements.

How much should I budget for a survey in 2026?

In 2026, you should budget between £400 and £1,000 for a RICS Level 2 survey, which is suitable for most modern homes. If you’re purchasing an older or unique property, a Level 3 Building Survey typically costs between £630 and £1,500. Investing in the right survey is one of the most important steps to buying a house in Leicestershire, as it helps you avoid unexpected repair bills for issues like damp or structural movement.

Can I buy a house in Leicestershire if I haven’t sold my current one yet?

You can certainly start your search, but you’ll be in a much stronger negotiating position if your current home is already under offer. Sellers in competitive areas like Woodhouse Eaves often prioritise proceedable buyers who aren’t dependent on a sale that hasn’t happened yet. If you haven’t sold, you might consider a bridge loan or moving into rented accommodation to become a chain-free buyer, which is highly attractive to local sellers.

What happens if the property chain breaks?

If a property chain breaks, the transaction effectively pauses until a new buyer or property is found to fill the gap. This can be frustrating, but an experienced estate agent will work proactively to find a replacement and keep the remaining links together. It’s a common part of the steps to buying a house in Leicestershire, and staying calm whilst your agent explores alternative options is the best way to manage the situation.

Are there any specific local searches I should be aware of in Leicestershire?

Your solicitor will conduct standard local authority searches, but in certain parts of Leicestershire, you should check for radon gas and historic mining activity. Radon is a naturally occurring gas found in some granite-rich areas of Charnwood, such as Mountsorrel. Whilst usually manageable, it’s a specific local factor that your legal team will investigate. They’ll also check for any planned infrastructure projects or road improvements that might affect your chosen village.

How do I know if I am paying a fair price for a property in Rothley?

To ensure you’re paying a fair price in Rothley, compare the property against recent sold prices on HM Land Registry for similar homes in the same street. Market trends in 2026 show that whilst national prices are stable, specific Charnwood villages often maintain higher demand. You can also request a free valuation from a local expert to understand the true market value based on 15 years of experience in the local property sector.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

Mortgage Application Checklist UK: A Professional Guide for Leicestershire Buyers (2026)

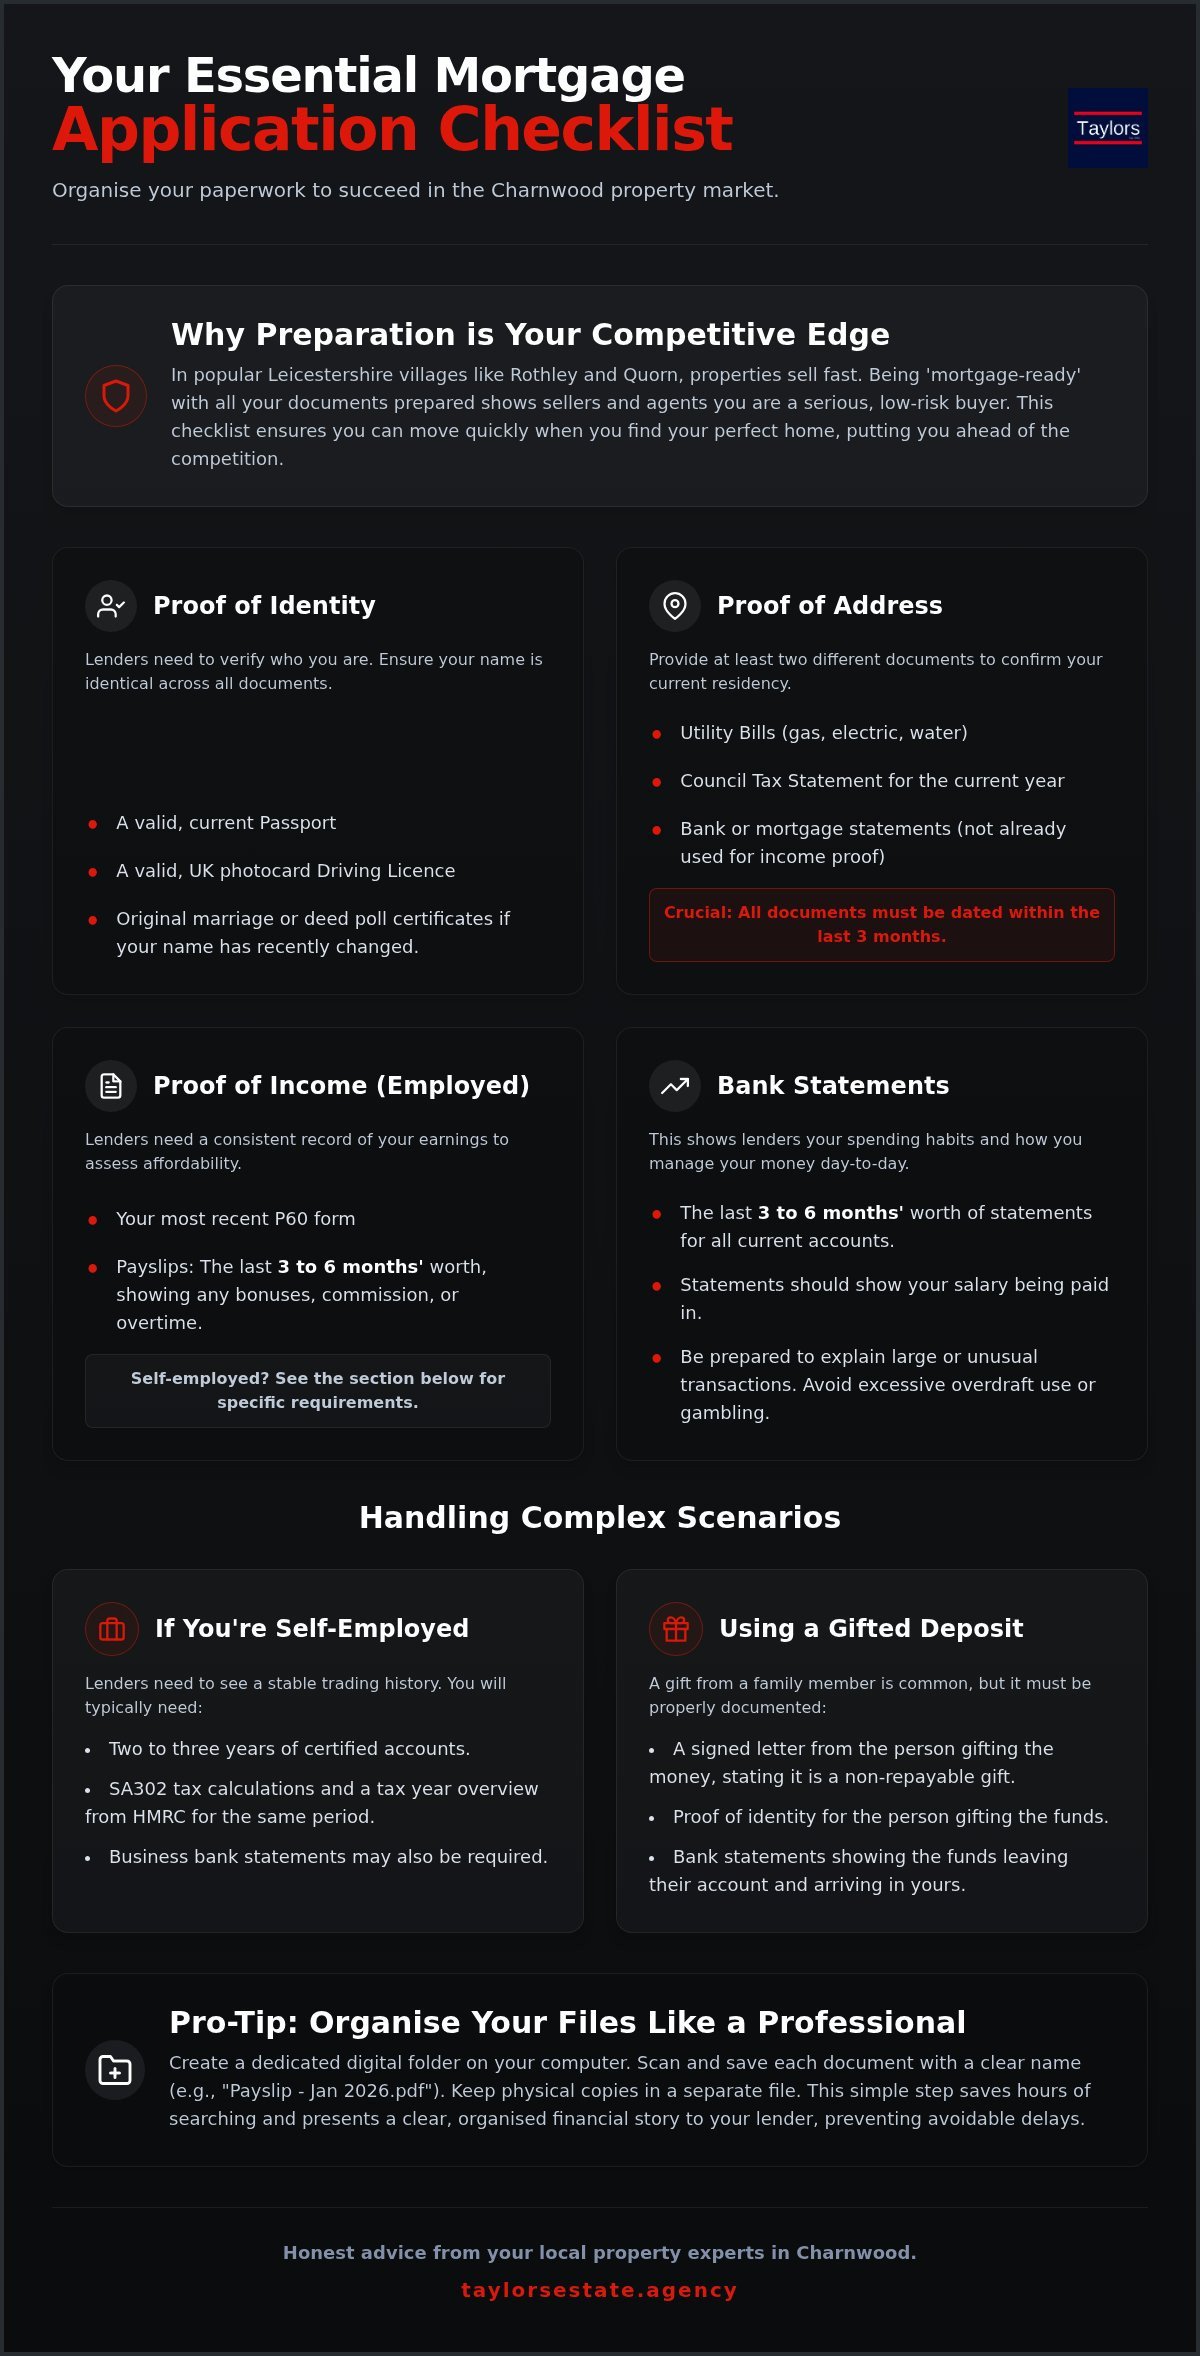
Imagine finding your perfect home in Rothley or a Victorian terrace in Quorn, only to watch it slip away because a single document was missing from your file. It’s a frustrating situation that many buyers face when they aren’t prepared for the lender’s scrutiny. In the Charnwood property market, being mortgage-ready is just as important as having your deposit saved, as delays in paperwork can lead to losing out to a more prepared bidder.

We know that gathering years of financial history feels daunting, especially if you’re self-employed or managing a gifted deposit. This guide provides a definitive mortgage application checklist UK to help you organise your paperwork well before you start viewing properties. We’ll walk you through exactly what lenders require in 2026, from proof of identity to the intricate details of your monthly expenditure. You’ll gain a clear understanding of the application timeline and the peace of mind that comes from having your story of money perfectly documented and ready for review.

Key Takeaways

  • Understand why preparing your paperwork early is essential for staying ahead in competitive Leicestershire villages like Rothley and Quorn.
  • Follow a detailed mortgage application checklist UK to ensure your identity, address, and income documents are exactly what lenders expect in 2026.
  • Learn how to manage complex financial situations, such as self-employment or gifted deposits, without causing delays to your purchase.
  • Discover how to organise your digital and physical files to present a clear, professional story of your finances to your lender.
  • See how an expert property valuation provides the foundation for your budget before you begin viewing homes across the Charnwood area.

Why Being Mortgage Ready Matters in the Leicestershire Property Market

Properties in villages like Rothley and Quorn don’t wait for anyone. When a charming cottage or a modern family home hits the market, the interest is often immediate and intense. Being “mortgage ready” isn’t just a suggestion; it’s a strategic necessity for anyone serious about moving. If you haven’t started your mortgage application checklist UK, you risk being pushed to the back of the queue by buyers who have their finances perfectly aligned and ready for scrutiny.

A Mortgage in Principle (MIP) serves as your badge of credibility. It tells a seller that a lender has already looked at your basic figures and is prepared to lend you a specific amount. In a competitive environment, this document is often the difference between an agent booking you a viewing or advising the vendor to wait for a more “qualified” applicant. Beyond the logistics, being prepared reduces the immense emotional weight of the search. You can view homes with confidence, knowing exactly what you can afford amongst the various listings across Leicestershire. This clarity allows you to make decisions based on facts rather than hope.

The Competitive Edge in Charnwood

Vendors in Sileby or Anstey are looking for the path of least resistance. They want a sale that is likely to complete without a hitch. By having your paperwork in order, you present yourself as a low-risk buyer. The UK mortgage industry is complex, and lenders are increasingly thorough with their checks. Local agents, including our team at Taylors, prioritise offers from buyers who can prove their funding immediately. This proactive approach prevents the heartbreak of losing your dream home because you were still hunting for old payslips whilst someone else was signing their contract.

Using Financial Tools to Set Your Budget

Before you fall in love with a property in Mountsorrel, you need a realistic view of your purchasing power. A good starting point is to use a mortgage calculator to get a rough estimate of your borrowing capacity. However, you should remember that these tools provide a general guide. A lender will dive much deeper into your mortgage application checklist UK to verify your actual disposable income. You must also account for the cost of moving house leicestershire, including stamp duty and legal fees, to ensure your budget is robust and sustainable for the long term.

The Essential Documentation Checklist: Proving Your Identity and Income

Lenders in 2026 are more meticulous than ever. To meet the standards of a mortgage application checklist UK, you must provide documents that leave no room for doubt. Your primary identity document, typically a valid UK photocard driving licence or international passport, must be current and valid. If you’ve recently moved to a new home in Birstall or Sileby, ensure your licence reflects your new address before applying. For proof of residency, lenders usually require two separate documents, such as utility bills or council tax statements, dated within the last three months.

Income verification is the next hurdle. Lenders generally ask for your last three to six months of payslips to establish a consistent earning pattern. If your income includes shift allowances, bonuses, or commission, these should be clearly visible. Bank statements are perhaps the most sensitive part of the process. Lenders look for a clean money trail, scrutinising your spending habits amongst other monthly commitments. They’ll look for excessive overdraft use or frequent gambling transactions, which can flag you as a higher risk. Ensure you provide full statements, not just transaction lists, to show you manage your finances responsibly. If you’re unsure if your current statements are “mortgage ready,” you can message our team for a quick chat about local requirements.

Identity Documents: Avoiding Common Errors

Consistency is the foundation of a successful application. Your full name must appear exactly the same way on your passport, utility bills, and payslips. If you’ve recently changed your name through marriage or deed poll, you’ll need the original certificates to bridge any gaps. Using a comprehensive UK mortgage application checklist helps ensure you don’t miss these small but vital details that can stall an application for weeks. Lenders won’t accept documents where the names don’t align perfectly without legal proof of the change.

Income Proof for Employed Professionals

When submitting your documents, quality matters. Lenders require original PDF downloads from your employer’s payroll portal rather than mobile phone screenshots or blurry photos. Screenshots often lack the essential metadata and formatting that banks use to verify authenticity. If your pay varies due to commission or overtime, be prepared to explain these fluctuations to your advisor so they can present your case accurately to the lender. The P60 is the annual summary of your pay and tax that lenders use to verify your basic salary. Having this document ready prevents unnecessary back-and-forth during the underwriting stage.

Handling Complex Scenarios: Self-Employment and Gifted Deposits

Not every buyer in Leicestershire is a PAYE employee with a simple deposit. If you’re a business owner in Mountsorrel or receiving help from family to buy in Rothley, your mortgage application checklist UK will require extra layers of verification. Lenders aren’t trying to be difficult; they’re simply performing due diligence to ensure the loan is sustainable and the funds are legitimate. Preparing these specific documents early prevents the stress of a last-minute scramble when you’ve found a property you love.

The Self-Employed Paper Trail

For the self-employed, the traditional payslip is replaced by the SA302 form and a Tax Year Overview. Lenders typically look for at least two years of certified accounts to assess your average earnings. They’re searching for consistency in your net profit over this period. If your income fluctuates significantly, be prepared to explain why, perhaps due to a large one-off investment in your business or a temporary market shift. Consistency is key, and lenders often take an average of the last two years’ profits to determine your borrowing power.

Having a qualified accountant sign off on your financial statements adds a layer of authority that lenders appreciate. You can download your SA302 forms directly from the HMRC website, which provides the “Tax Calculation” summary lenders use to verify your declared income. Ensuring these figures match your bank statements is a vital step in proving your financial stability. Without these matching records, underwriters may struggle to approve your application, regardless of how successful your business appears on the surface.

Handling Gifted Deposits Correctly

Gifted deposits are common amongst first-time buyers in villages like Anstey or Cropston. However, a simple bank transfer isn’t enough to satisfy modern lending requirements. Your family members must provide a signed letter stating the amount, their relationship to you, and a clear “no-repayment” clause. This confirms the money is a genuine gift, not a hidden loan that would affect your monthly affordability calculations. It’s a small but vital detail that can halt an application if missed.

To comply with UK Anti-Money Laundering (AML) regulations, the donor also needs to provide proof of identity and their own bank statements. This documents the “source of funds,” showing exactly how the money was accumulated. It’s wise to ensure your solicitor and chosen estate agents leicestershire are aware of the gift early in the sales process. Early transparency prevents delays when you’re nearing the exchange of contracts on your new home, keeping the momentum of your move on track.

Avoiding Delays: How to Organise Your Financial Paperwork Like a Pro

Efficiency is the hallmark of a successful move. Once you’ve gathered the items for your mortgage application checklist UK, the way you store and present them can significantly impact your speed to offer. We recommend creating a dedicated digital folder with a logical structure. Use clear, descriptive filenames, such as “John_Doe_Payslip_Jan_2026.pdf”, rather than generic strings of numbers. This small step allows your mortgage advisor or solicitor to identify documents instantly, preventing the back-and-forth emails that often stall an application.

Whilst digital is the standard for submissions, keeping a physical “home-buying file” is equally beneficial. Having hard copies ready for face-to-face meetings with local advisors in Rothley ensures you can answer questions on the spot. You must also remember the “Three-Month Rule”. Lenders require the most recent data, so if your search for a home in Charnwood takes longer than expected, you’ll need to refresh your file as old statements expire. It’s also wise to review your credit report via Experian or Equifax before the lender does, allowing you to correct any errors that might affect your score.

Audit Your Own Bank Statements

Lenders look for patterns, not just balances. Before you submit your statements, perform a self-audit to identify potential “red flags”. Frequent payday loans or large, unidentified transfers between accounts can trigger requests for more information. If you have regular outgoings that look unusual, be prepared to explain them as part of your affordability assessment. We advise buyers to stop using their overdraft three months before an application to show better financial behaviour. This proactive shift demonstrates that you are living within your means and are ready for the responsibility of a monthly mortgage payment.

Collaborating with Local Professionals

Your mortgage application checklist UK isn’t just for the bank. A local solicitor in Rothley or Loughborough will require the same proof of identity and source of funds for the conveyancing process. By having these organised early, you can move from “offer accepted” to “contracts exchanged” with much more momentum. Working with a local mortgage broker who understands the Charnwood property market adds another layer of security. At Taylors, we encourage buyers to be transparent about their financial position from the first viewing. This honesty allows us to advocate for you more effectively when speaking to vendors in villages like Mountsorrel or Quorn.

Get expert advice on organising your paperwork

Mortgage Application Checklist UK: A Professional Guide for Leicestershire Buyers (2026)

Beyond the Paperwork: Taking Your Next Steps with Taylors Estate Agency

Completing your mortgage application checklist UK is a significant milestone, but it represents just one half of the moving journey. Once you have your documents organised and your Mortgage in Principle secured, the focus shifts to finding a property that fits your lifestyle. At Taylors, we’ve spent over 30 years guiding buyers and sellers through the nuances of the Leicestershire property market. Established in 1992, our Rothley-based team offers a level of local proficiency that only comes from decades of active engagement in the community. We understand that behind every document is a family looking for a fresh start in Mountsorrel or a professional seeking a quiet retreat in Sileby.

Our role is to act as a reliable pillar of support throughout the entire transaction. Choosing a local, independent agent ensures you have a dedicated partner who communicates directly with your lender and solicitor to maintain momentum. This “steady hand” approach is designed to reduce client anxiety, providing clarity whilst you move from the initial application to the day you receive your keys. By being transparent about your financial readiness from the start, you allow us to advocate for you more effectively when presenting offers to vendors in competitive areas like Rothley or Anstey.

Start Your Search with Confidence

You can begin your search with complete confidence by browsing our current residential listings across Charnwood. We strongly recommend registering for our property alerts to ensure you’re the first to hear when a new home in Quorn or Barrow Upon Soar hits the market. Our team prides itself on proactive coordination, acting as the essential link between you, the seller, and the various professionals handling your move. This ensures that the hard work you put into gathering your financial paperwork translates into a successful and timely completion.

Get a Professional Valuation

For many Leicestershire residents, the next step involves selling a current home to fund their purchase. Understanding your available equity is a vital part of the mortgage application checklist UK, as it forms the foundation of your deposit and borrowing capacity. We provide expert, no-obligation property valuation services to give you an accurate, evidence-based figure for your financial planning. Knowing your home’s true value allows you to approach lenders with the confidence that your budget is realistic. Contact Taylors Estate Agency today for a friendly, honest chat about your future plans and how our independent boutique service can deliver the results you need.

Securing Your Future in Leicestershire

Taking the time to prepare your mortgage application checklist UK is the most effective way to ensure your journey to a new home in Charnwood is as smooth as possible. By organising your financial story before you begin viewing properties in Rothley or Quorn, you position yourself as a serious, qualified buyer ready to act when the right opportunity arises. This proactive approach doesn’t just satisfy the lender’s requirements; it gives you the confidence to make decisions based on clear, verified facts.

As independent local experts since 1992, we’ve spent decades becoming specialists in Rothley and Charnwood property. Our team provides friendly, honest advice from experienced agents who prioritise your peace of mind whilst handling the complexities of the 2026 market. We’re proud to act as a reliable pillar of the community, offering the steady hand and local proficiency needed to turn your moving plans into a reality.

Book a free property valuation with Taylors Estate Agency today

We look forward to helping you take the next step toward your dream home in our beautiful corner of Leicestershire.

Frequently Asked Questions

How long does a mortgage application take in the UK?

A mortgage application typically takes between two and six weeks to reach a formal offer stage, though this timeline depends on the complexity of your finances and the lender’s current workload. Providing a complete mortgage application checklist UK at the start can significantly speed up the process. Delays often occur when underwriters require additional clarification on bank statements or self-employed accounts, so being prepared from day one is essential for a smooth experience.

Can I apply for a mortgage if I have only been self-employed for one year?

Whilst most high-street lenders require at least two or three years of certified accounts, it’s possible to apply with only one year of self-employment through specialist providers. You’ll need a finalised SA302 and a Tax Year Overview from HMRC to prove your earnings. Lenders will scrutinise your previous employment history and the sustainability of your business, so having a qualified accountant to sign off your figures is highly recommended for buyers in Rothley or Quorn.

Do I need to provide bank statements for all my accounts?

Lenders generally require the last three to six months of statements for all active current accounts, especially those where your salary is paid and your outgoings are managed. If your deposit is held in a separate savings account, you must provide statements for that as well to prove the source of funds. Underwriters look for a clear, consistent money trail across all your financial holdings to ensure your reported disposable income is accurate and sustainable.

What is the difference between a Mortgage in Principle and a full application?

A Mortgage in Principle is an initial estimate from a lender indicating how much they might be willing to lend you based on basic information. It doesn’t involve a full credit check or a property valuation. A full application is the formal process triggered once you have an offer accepted on a home. This stage involves the detailed scrutiny of your mortgage application checklist UK and a professional assessment of the property you intend to buy in Leicestershire.

Will a gifted deposit affect my mortgage application?

A gifted deposit won’t negatively affect your application as long as it’s documented correctly with a signed gift letter. This letter must confirm the money is a gift, not a loan, and that the donor has no legal interest in the property. Lenders must also verify the donor’s identity and the source of their funds to comply with anti-money laundering regulations, which is a standard part of the process for buyers in Charnwood villages.

What happens if my passport has expired before I apply?

You cannot use an expired passport as your primary proof of identity for a mortgage application. Lenders require valid, current photocard identification to satisfy their security checks and regulatory requirements. If your passport has expired, you may be able to use a valid UK photocard driving licence instead. If you possess neither, you should prioritise renewing your passport before starting your application to avoid unnecessary delays in the home-buying process across Leicestershire.

Do I need to provide proof of my deposit if it is in a savings account?

Yes, you must provide bank statements for any savings account where your deposit is held. Lenders need to see the accumulation of funds to ensure the money has been saved legitimately over time or comes from a verified source like an inheritance. If the money was recently transferred from another account, be prepared to provide the statements for that account too, ensuring the entire trail is transparent and easy for the underwriter to follow.

How far back do lenders look at my bank statements?

Most UK lenders will ask to see your bank statements from the last three months, though some may request up to six months if your income is complex. They use this period to assess your typical spending habits and identify any regular financial commitments that could impact your ability to keep up with mortgage repayments. Maintaining clean statements during this window, with no returned payments or excessive overdraft use, is vital for a successful outcome when buying in Sileby.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

How Much Can I Borrow? 2026 UK Affordability Guide

How Much Can I Borrow? 2026 UK Affordability Guide

Why does one website tell you that you can afford a detached home in Quorn, while another suggests you’re limited to a small apartment in the city centre? It’s a common frustration because determining how much can I borrow mortgage UK has shifted from a simple salary calculation to a complex assessment of your daily lifestyle. You’ve likely spent hours on generic calculators only to end up more confused by conflicting results and the impact of the 3.75% Bank of England base rate on your monthly budget.

We understand that this uncertainty makes planning your move to Rothley or Mountsorrel feel like a guessing game. This guide breaks down the realistic factors lenders use in 2026, from the standard salary multiple rules to the way your credit history and monthly outgoings truly impact your capacity. We will explain how current interest rates affect your repayments and provide a clear roadmap to strengthen your financial profile. By the end, you’ll have the knowledge to start viewing properties in Charnwood with a budget that’s grounded in reality and professional insight.

Key Takeaways

  • Learn how lenders calculate how much can I borrow mortgage UK by moving beyond simple salary multiples to look at your specific lifestyle and monthly commitments.
  • Understand why your discretionary spending and credit history are just as important as your annual income when banks assess your affordability in 2026.
  • Identify the “sweet spot” for deposit sizes, typically between 10% and 15%, to secure more competitive interest rates and increase your overall borrowing power.
  • Discover practical steps to improve your financial profile before applying, such as ensuring you are on the electoral roll and managing your outgoings early.
  • See how matching your budget to specific Charnwood locations requires a deep understanding of local market values and moving costs, a speciality of Taylors Estate Agency.

Understanding the UK Mortgage Borrowing Landscape in 2026

The UK mortgage industry has evolved significantly over the last few years. While many buyers still start their journey by multiplying their gross annual income by 4 or 4.5, this is rarely the final figure. Lenders now use sophisticated algorithms to determine how much can I borrow mortgage UK, focusing on your ability to maintain payments even if life throws a curveball. The Financial Conduct Authority (FCA) oversees these standards to ensure lending remains responsible, preventing the market from returning to the risky practices of the past.

There is a vital distinction between what a bank is willing to lend and what you can comfortably afford each month. In 2026, with the Bank of England base rate sitting at 3.75%, your “paper” affordability might look different from your bank balance reality. A high salary is a great foundation, but it’s only one piece of the puzzle. We often see buyers in Rothley who are surprised that their maximum loan is lower than expected because of high commuter costs or existing financial commitments.

The Salary Multiple vs. Affordability Testing

Lenders prioritise residual income in their 2026 assessments. This is the money left over after you’ve paid for essentials like utilities, council tax in Charnwood, and groceries. Even if you earn a substantial wage, high childcare costs or significant personal debt will reduce your maximum loan. Banks also apply stress tests, calculating whether you could still manage repayments if interest rates were to climb several percentage points higher than your current deal. This ensures you won’t lose your home if the economic climate shifts during your fixed term.

How Your Employment Type Affects the Calculation

Your income’s stability is just as important as the total amount. Full-time PAYE employees usually have the simplest path, with lenders taking 100% of their basic salary into account. However, for those working in Leicestershire’s thriving self-employed sector or on fixed-term contracts, the rules are more nuanced. Following the FCA’s recent consultation on mortgage rules, some lenders now offer more flexibility for those with variable incomes. They may look at a two or three-year average of your accounts. Bonuses, commissions, and overtime are often shaded, meaning a bank might only count 50% to 80% of that income towards your total borrowing capacity.

Critical Factors That Influence Your Borrowing Capacity

Your borrowing capacity isn’t a static figure etched in stone. It’s a moving target shaped by what we call the “big three”: your income, your outgoings, and your credit score. When you ask how much can I borrow mortgage UK, you’re really asking how a lender views your financial reliability. Banks in 2026 are particularly focused on your debt-to-income ratio. This is a simple calculation of your monthly debt commitments against your gross earnings. If you have dependent children or existing financial commitments like car leases; these will naturally reduce your total borrowing power.

Lenders now scrutinise discretionary spending with a fine-tooth comb. They aren’t just looking at whether you can pay the mortgage today; but whether you can sustain it if life becomes more expensive. If you’re looking at homes in Rothley or Quorn; understanding these nuances early can save significant stress later. If you want to see how your current debts might change your outlook; a mortgage affordability calculator is a brilliant place to start your research.

The Role of Your Credit Profile

Your credit score is about more than just paying your bills on time. It’s a snapshot of your relationship with money. Lenders look for patterns; such as how much of your available credit you actually use. High credit card utilisation; even if you pay the minimum every month; suggests a reliance on debt that banks find off-putting. We recommend that buyers in Mountsorrel and Birstall organise their finances at least six months before starting their search. This means avoiding new credit applications; such as furniture finance or car loans; and keeping your balances low. If you’re wondering how your specific profile might affect your chances; send us a quick message for some honest local advice.

Assessing Your Monthly Expenditure

Lenders divide your bank statements into essential and non-essential costs. Essentials are the non-negotiables; student loans, car finance, and childcare costs. For many families in Charnwood; childcare is often the heaviest weight on an application. Then they look at your lifestyle choices. Discretionary spend is the primary lever for 2026 mortgage approvals. By reducing non-essential outgoings like premium subscriptions or frequent dining out in the months leading up to your application; you effectively increase your “paper” affordability. This demonstrates to the lender that you have the surplus income necessary to handle the 3.75% base rate environment comfortably.

Loan-to-Value (LTV) and Its Impact on Your Purchase

Loan-to-Value, or LTV, is the percentage of the property’s value that you are looking to borrow. If you are buying a home in Rothley for £400,000 and have a £40,000 deposit, your LTV is 90%. This figure is a critical component when calculating how much can I borrow mortgage UK because it determines which interest rate tiers you qualify for. Lenders view a lower LTV as a lower risk; which often results in more generous borrowing limits and cheaper monthly repayments.

In the 2026 market; the “sweet spot” for many buyers in Leicestershire is a 10% or 15% deposit. While the Freedom to Buy scheme has made 95% mortgages a permanent fixture; these high-LTV products usually come with higher interest rates to offset the lender’s risk. By reaching an 85% LTV; you often move into a different pricing bracket that can save you thousands of pounds over the life of your fixed term. Property valuations in sought-after areas like Mountsorrel are stable; but lenders will always base their final loan offer on their own surveyor’s valuation rather than the agreed purchase price.

How Deposit Size Changes Your Monthly Costs

The difference between a 95% and an 80% LTV mortgage is about more than just the initial cash you put down. A 95% mortgage might carry an interest rate significantly higher than the average 5-year fixed rate of 5.66%. Stepping up to an 80% LTV can unlock rates that are much closer to the base rate; drastically reducing your monthly outgoings. If you are planning to sell an existing property to fund your next move; it’s vital to get an accurate starting point. You can check how much is my house worth in Syston to understand how much equity you could potentially port over to your new purchase.

Property Types and Lender Restrictions in Leicestershire

The type of property you choose in Charnwood can also dictate your LTV requirements. Period properties in Quorn or Anstey are beautiful; but they often require more detailed surveys. If a property has non-standard construction; such as a thatched roof or timber frame; some lenders may reduce the maximum LTV they are willing to offer. They might even require a larger deposit to protect their security. The property itself acts as the final collateral for the loan; so if the building is considered high-maintenance or difficult to resell; it directly impacts the bank’s willingness to lend the full amount you’ve requested.

Practical Steps to Maximise Your Borrowing Power

Preparing for a mortgage application is a marathon; not a sprint. If you want to accurately determine how much can I borrow mortgage UK; you need to look at your finances through a lender’s eyes at least six months before you intend to buy. Start by ensuring you’re on the electoral roll at your current address. This is a simple but vital step for identity verification; as a lack of registration can lead to automatic rejections or frustrating delays that might cost you a property in a competitive village like Quorn or Woodhouse Eaves.

Gathering your documentation early is equally important for a smooth process. You’ll generally need your last three P60s and three months of bank statements to prove your income and spending habits. For the self-employed in Leicestershire; have your last two years of tax calculations (SA302s) and tax year overviews ready. Reducing existing debt before your search begins is also a primary lever; as it improves your debt-to-income ratio and increases your monthly disposable income. This proactive approach shows lenders you’re managing your finances responsibly. Having this data at your fingertips ensures your application is based on accurate; verifiable figures rather than estimates.

Financial preparation also involves a realistic look at your lifestyle. Lenders in 2026 are looking for stability and predictability. If you’ve recently changed jobs or have gaps in your employment history; be prepared to explain these clearly. By organising your finances well in advance; you position yourself as a low-risk borrower; which is essential for securing the most competitive rates in the Charnwood market.

Financial Housekeeping Before You Apply

Lenders prefer a “clean” financial history. Closing credit cards you don’t use reduces the total credit available to you; which banks see as a potential risk. Try to stay out of your overdraft for three months and avoid large purchases like new cars. These commitments appear as monthly outgoings; directly reducing your borrowing capacity. Maintaining transparent spending makes it much easier for an underwriter to approve your loan.

Contact our team for a personal consultation on your local property search

Securing a Decision in Principle (DIP)

A Decision in Principle (DIP) is an initial assessment confirming a lender’s willingness to lend a specific amount. While it isn’t a full mortgage offer; it shows sellers in Rothley or Anstey that you’re a prepared buyer. A DIP is the “currency of trust” when making an offer on a competitive property. It proves you’ve researched your budget and have the backing to move forward with confidence; which is vital in the 2026 market where how much can I borrow mortgage UK remains a key concern for many.

How Much Can I Borrow? 2026 UK Affordability Guide

Knowing your borrowing limit is the foundation; however, applying that figure to the Charnwood market is where the real work begins. A generic calculator won’t tell you that a budget stretching to a semi-detached in Birstall might secure a more spacious detached property in Sileby. We believe in a balanced approach where your financial capacity meets your lifestyle aspirations. It’s about more than just the mortgage; you must also account for the true cost of moving house in Leicestershire, including updated stamp duty thresholds and local surveyor fees.

When you finally determine how much can I borrow mortgage UK, the next step is matching that loan to the right postcode. This is where local expertise becomes your most valuable asset. We support our clients from the initial valuation through to the day they collect their keys; ensuring every decision is backed by evidence and 15 years of local market experience. Understanding how much can I borrow mortgage UK is only half the battle; the other half is knowing where that money goes furthest in the current landscape.

Why Local Knowledge Trumps Online Calculators

Online tools provide a rough estimate; but they lack the nuance of local market dynamics. For instance, some lenders are more cautious about specific property ages or construction types in villages like Barrow Upon Soar. An experienced agent understands these lender attitudes and can guide you toward homes more likely to pass a valuation survey without complications. We help you find the right balance between borrowing and the practical reality of maintaining a home in a specific neighbourhood. This ensures you don’t just buy a house; but a home you can afford to enjoy for years to come.

Starting Your Journey in Rothley

Our team has seen every common pitfall; from over-borrowing to missing out on properties due to a lack of preparation. We offer a “steady hand” approach; providing honest advice that prioritises your peace of mind. Whether you’re moving within Cropston or looking to settle in Thurcaston; we act as your guide through the entire process. If you have questions about specific village values or need a sounding board for your plans; you can get in touch via WhatsApp for personalised advice.

Taking Your Next Steps in the Charnwood Market

Determining how much can I borrow mortgage UK is a strategic look at your financial life through a lender’s eyes rather than a simple calculation. We have explored how 2026 affordability models prioritise your daily spending habits and how reaching specific deposit thresholds can significantly lower your monthly costs. By taking proactive steps to manage your credit and organise your documentation; you build a foundation of trust with potential lenders before you even step inside a property.

Since 1992; Taylors Estate Agency has acted as a trusted local guide for buyers across Rothley and the wider Charnwood area. Our independent status and 15 years of professional experience mean we offer honest; practical advice tailored to the villages we know so well. We are committed to helping you find a balance between your borrowing capacity and the lifestyle you want to lead in Leicestershire.

Ask our local experts for honest mortgage advice on WhatsApp

We are here to provide the steady hand you need to move forward with confidence. Your journey toward a new home starts with clear; evidence-based planning and a partner who understands the local landscape.

Frequently Asked Questions

Is the 4.5 times salary rule still accurate for UK mortgages in 2026?

The 4.5 times salary rule remains a standard benchmark for the UK mortgage industry in 2026; however; it is no longer the sole deciding factor. While many lenders use this as a baseline; others may offer up to 5.5 times your income if you have a high salary or minimal outgoings. Your final offer depends heavily on detailed affordability stress tests that look at your net income after all essential living costs are deducted.

Can I borrow more if I have a larger deposit?

A larger deposit improves your Loan-to-Value (LTV) ratio; which often unlocks more competitive interest rates. While a bigger deposit doesn’t automatically increase the multiple of your salary you can borrow; lower interest rates reduce your monthly repayment costs. This can lead to a more favourable affordability assessment; potentially allowing you to secure a slightly larger loan because the monthly commitment is more manageable for your household budget.

How do my monthly outgoings affect my mortgage borrowing amount?

Your monthly outgoings are subtracted from your take-home pay to determine your “residual income.” Lenders scrutinise everything from car finance and student loans to childcare costs and regular subscriptions. If your fixed monthly commitments are high; the amount you can borrow will decrease; as the lender must ensure you have enough surplus cash to cover your mortgage payments even if interest rates were to rise during your term.

Will being self-employed reduce how much I can borrow?

Being self-employed doesn’t inherently reduce your borrowing capacity; provided you can supply two to three years of certified accounts or SA302 forms. Lenders typically average your net profit over this period to determine your income. Some specialist lenders are now more flexible for those with only one year of trading; though they may require a larger deposit to offset the perceived risk of a variable or recently established income.

Does a student loan impact my mortgage affordability?

Yes; student loan repayments are treated as a monthly commitment that reduces your net take-home pay. When calculating how much can I borrow mortgage UK; lenders factor in these deductions just like any other debt or tax. While a student loan won’t prevent you from getting a mortgage; it will slightly lower the maximum loan amount available to you because it reduces the total disposable income you have available for repayments.

How much can I borrow if I am buying with a partner?

When buying with a partner; lenders typically combine your gross annual incomes and apply a multiple; usually between 4 and 4.5 times the total. This significantly increases your borrowing power compared to a single application. Both applicants undergo the same rigorous credit checks and expenditure assessments; so high debts or poor credit history from one partner can still impact the overall amount the lender is willing to offer for your joint purchase.

What happens if the property valuation is lower than my mortgage offer?

If a lender’s valuation comes in lower than your agreed purchase price; they will only lend based on that lower figure. This is known as a “down valuation.” In this scenario; you would need to increase your deposit to cover the shortfall or renegotiate the price with the seller. This is why understanding local market values in areas like Rothley or Quorn is vital before making an offer on a home.

Should I use an online mortgage calculator before viewing houses?

An online how much can I borrow mortgage UK calculator is a helpful starting point for a rough estimate; but it shouldn’t be your final word. These tools often miss the nuances of 2026 lender behaviour and your specific outgoings. We recommend obtaining a Decision in Principle (DIP) before viewing properties in Charnwood; as this provides a more accurate reflection of your actual budget and demonstrates your serious intent to sellers.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

What is a Mortgage in Principle? A Guide for UK Home Buyers

What is a Mortgage in Principle? A Guide for UK Home Buyers

Walking into a house viewing in Rothley or Mountsorrel without a Mortgage in Principle is a bit like trying to board a flight without a passport; you might get to the terminal, but you aren’t going anywhere. You’re likely asking, what is a mortgage in principle UK lenders provide, and do you actually need one before you start your search? It’s natural to feel anxious about being rejected by sellers or worried that a formal check might damage your credit score before you’ve even made an offer.

We agree that the financial hurdles of buying a home can feel heavy, but securing this document is the most effective way to prove you’re a serious buyer. This guide explains how the process works and why it’s a vital first step for anyone looking in the Charnwood area. You’ll discover how to get an accurate budget without affecting your credit rating and how to position yourself as the preferred candidate for local homeowners. We also look at what the current 3.75% base rate means for your application, ensuring you have a clear path from your initial search to a successful mortgage offer.

Key Takeaways

  • Learn exactly what is a mortgage in principle UK lenders provide and how it acts as a preliminary certificate of your borrowing capacity.
  • Discover how to obtain an agreement using soft credit searches that won’t leave a visible mark on your credit file or affect your score.
  • Understand why sellers in Charnwood villages like Rothley and Quorn often require an AIP before they will consider your offer or even confirm a viewing.
  • Find out why these certificates typically last between 30 and 90 days and what steps you must take if your search for a Leicestershire home takes longer.
  • Gain the confidence to start your property search with a clear budget, knowing exactly what you can afford before you step through the door.

What is a mortgage in principle and why is it essential?

A mortgage in principle (AIP) is essentially a certificate from a bank or building society that gives you a clear indication of your borrowing capacity. It acts as a preliminary assessment of your finances, showing that a lender is prepared, in theory, to offer you a specific amount. When you’re asking what is a mortgage in principle UK lenders provide, it’s best to view it as a vital budgeting tool rather than a final contract. In a market where the average house price in Leicester sits around £230,000, having this figure in black and white allows you to focus your search on homes in Rothley or Mountsorrel that are truly within reach.

This document is built upon the legal framework of a mortgage, but it doesn’t commit you to a specific lender or property yet. Instead, it provides the confidence to approach estate agents as a verified buyer. Without one, you might find yourself falling in love with a property in Quorn only to discover later that the monthly repayments don’t align with your lender’s affordability criteria. It narrows your search, saves time, and ensures you aren’t chasing properties that sit outside your financial reality.

The difference between an AIP and a formal offer

It’s vital to understand that an AIP is not a binding guarantee. It’s based on unverified information you’ve provided about your income and spending. A formal mortgage offer only arrives much later, once you’ve had an offer accepted on a house and the lender has conducted a full audit of your payslips, bank statements, and the property’s value. This stage also involves a “hard” credit check and a professional valuation of the home you intend to buy.

Mistaking a “principle” for an “offer” can lead to significant stress during the conveyancing process. If a lender discovers discrepancies during their deep dive, they can still decline your application. We’ve seen buyers across Charnwood face disappointment because they assumed the initial certificate was set in stone. Treat the AIP as your permission to shop and the formal offer as the final deal.

Commonly used terms: AIP vs. DIP

You’ll likely hear several different names for this document depending on which bank you visit. Whether it’s called an Agreement in Principle (AIP), a Decision in Principle (DIP), or simply a Mortgage in Principle, they all serve the exact same purpose. Different institutions prefer different labels, but for you as a buyer in Leicestershire, the weight they carry with sellers remains identical.

In the 2026 financial climate, an AIP is a conditional statement that confirms you meet a lender’s basic criteria based on a high-level view of your creditworthiness and current income levels. It’s the first major milestone in your journey toward homeownership.

How the application process works in 2026

Applying for an Agreement in Principle (AIP) is much more streamlined than in previous years. Most lenders have optimised their digital portals to provide an answer within minutes. However, the speed of the result depends on how prepared you are with your financial data. You’ll need to provide an honest snapshot of your income, existing debts, and monthly outgoings to ensure the figure you receive is realistic for the current market. When exploring what is a mortgage in principle UK lenders require, remember that accuracy at this stage prevents delays when you eventually transition to a full application.

The process begins by gathering your core financial documents. While you don’t usually need to upload them for an AIP, having them to hand ensures the numbers you enter are precise. Once you submit your details, the lender performs a preliminary check against their lending criteria. If you meet their requirements, you’ll receive a certificate that remains valid for between 30 and 90 days. This document is your green light to start viewing properties in villages like Barrow upon Soar or Birstall with the confidence that a lender has already given you a tentative “yes”.

Information you will need to provide

Lenders look for stability and affordability above all else. You’ll need to state your exact gross annual salary, along with details of any bonuses, overtime, or secondary income streams. They also require a full three-year address history to satisfy identity checks and assess your residential stability. Don’t forget to include fixed monthly costs like car finance, student loans, or childcare fees. Providing accurate data now prevents the “mortgage gap” later, where a final offer might be lower than the initial principle because of missed expenditure details.

Online vs. broker-led applications

Choosing how to apply depends on your individual circumstances. Automated online systems are excellent for straightforward earners who want a quick certificate to start viewing houses in Sileby or Thurcaston. If your income is more complex, such as being self-employed or having multiple commission structures, a broker-led approach is often better. An independent broker can scan the 7,400 mortgage products available in August 2026 to find a lender whose criteria match your specific profile. With average 2-year fixed rates currently around 5.63%, a professional can often secure a more competitive deal or a higher borrowing limit because they understand the nuances of different bank policies.

Once you have your certificate, check that the projected monthly repayments fit within your wider budget. It’s easy to focus only on the total loan amount, but you must also factor in the cost of moving house leicestershire residents should expect, including survey fees, legal costs, and potential stamp duty. We recommend using a mortgage calculator to see how different interest rates might affect your long-term affordability. If you’re feeling unsure about how much you should realistically borrow in the current market, you can always message our team for local advice on how to prepare for your next move.

Understanding credit checks and validity periods

One of the most frequent concerns we hear from buyers in Rothley and Birstall is whether applying for a certificate will leave a permanent mark on their credit file. When exploring what is a mortgage in principle UK lenders offer, it’s vital to distinguish between the two types of credit searches used. Most modern banks now utilise a ‘soft’ credit search for this initial stage. This is essentially a high-level background check that allows the lender to verify your identity and your history of managing debt without leaving a visible footprint for other organisations to see. It gives you the freedom to check your borrowing power without the fear of damaging your credit rating before you’ve even found a property.

This approach provides a “steady hand” for those at the start of their journey. It allows you to shop around and compare options with the confidence that your credit score remains intact. However, you should be aware that a ‘hard’ search, which is recorded on your credit report, is typically reserved for the moment you submit a full mortgage application. Hard searches provide a much deeper dive into your financial behaviour and can temporarily lower your score, which is why we always recommend securing your AIP first to avoid unnecessary hard checks on multiple properties.

Will an AIP affect my credit score?

A soft search has no impact on your future borrowing ability. You can see it on your own credit report, but it remains invisible to any other lenders or companies searching your file. This transparency is a significant advantage in the early stages of a home search. We suggest you avoid making multiple full applications in a short window, as several hard searches can suggest to lenders that you’re struggling to secure credit. Before you commit to an application, always ask the lender or your broker to confirm they are using a soft search to protect your financial profile.

What happens when your certificate expires?

AIP certificates aren’t indefinite; they typically remain valid for between 60 and 90 days. This window is designed to reflect your most current financial situation and the prevailing market conditions. In a climate where the Bank of England base rate sits at 3.75%, lenders must ensure their “in principle” offers align with current affordability tests. If your search for a home in Sileby or Anstey takes longer than three months, you’ll simply need to renew the document.

Renewing is usually a quick process of updating your latest income and expenditure details. Be mindful that if your circumstances change, such as taking on new car finance or changing jobs, the lender may adjust the amount they are willing to lend. Staying organised with your paperwork ensures that when that perfect Leicestershire home finally hits the market, your proof of funds is current and you’re ready to act immediately. It’s about being proactive so you don’t miss out on a property because of an expired document.

What is a Mortgage in Principle? A Guide for UK Home Buyers

Why Leicestershire sellers prioritise buyers with an AIP

In villages like Rothley and Quorn, the property market remains remarkably resilient. With average house prices in Leicester reaching £230,000 by mid-2026, sellers are understandably selective about who they let through their front door. They aren’t just looking for the highest offer; they’re looking for the highest level of certainty. When you understand what is a mortgage in principle UK sellers look for, you realise it’s more than just a piece of paper. It’s a badge of credibility that proves you’ve done your homework and have the financial backing to see a transaction through to completion.

Without this document, your offer is essentially a promise without proof. In a competitive environment, a seller is far more likely to choose a slightly lower offer from a buyer with an AIP over a higher one from someone who hasn’t yet spoken to a lender. It reduces the risk of the sale falling through weeks later due to affordability issues, providing the steady hand that homeowners need during a stressful time. Many local agents now view an AIP as a prerequisite for viewings on high-demand homes, as it protects the seller’s time and ensures only qualified buyers are entering the market.

Gaining an advantage in a competitive market

Having your finances organised allows you to move with speed. When a new home hits the market in Mountsorrel, the first few days are often the most critical. If you’re already armed with your certificate, you can make an offer the moment you leave the viewing. This proactive approach often puts you at the front of the queue. Understanding what is a mortgage in principle UK banks require also serves as a potent negotiation tool. It demonstrates that your offer price is based on actual borrowing limits rather than guesswork, giving the seller the confidence to accept your bid and take the property off the market.

Local insights for Rothley and Mountsorrel

At Taylors Estate Agency, we’ve helped buyers manage the Charnwood market since 1992, and we’ve seen how much weight local sellers place on financial readiness. If you’re planning a move within Leicestershire, you must also consider your current position. For those selling a property to fund their next purchase, knowing how much is my house worth Syston or Rothley homeowners should ask is the other half of the equation. Balancing your confirmed borrowing power with an accurate valuation of your current home gives you a complete, realistic budget for your search.

Contact our Rothley team for a local market update

Your next steps: From principle to property purchase

Securing your certificate is a significant milestone that transforms you from a casual browser into a serious contender. Now that you have a clear answer to what is a mortgage in principle UK lenders provide, you can step into any home in Birstall or Cropston knowing exactly where you stand. This document removes the guesswork, allowing you to focus your energy on properties that fit both your lifestyle and your financial reality. We suggest using a mortgage calculator to model different scenarios; seeing how a £5,000 difference in your offer price impacts your monthly repayments helps you make cooler, more calculated decisions when the right house appears.

Keep your financial documents organised and easily accessible during this phase. Lenders might require a fresh review of your situation if your search extends toward the 90-day expiry limit. If your income changes or you take on a new credit commitment, such as a car lease, your borrowing power could shift. Staying in close contact with your mortgage advisor ensures you are always ready to act if a property hits the market in a high-demand area like Woodhouse Eaves.

Making an offer with confidence

When you find a home that checks all your boxes, present your AIP alongside your offer. This transparency shows the estate agent and the seller that you’re a “qualified buyer” who is ready to proceed immediately. If you fall in love with a property that costs slightly more than your AIP figure, it doesn’t necessarily mean the end of the road. You’ll usually need to bridge that gap with a larger cash deposit, as the lender’s loan amount remains capped at the figure on your certificate. Being honest with your agent about these financial boundaries leads to a smoother transaction and builds trust with the seller.

Moving to a full mortgage application

The acceptance of your offer triggers the transition from an ‘in principle’ agreement to a formal mortgage offer. This stage involves the lender performing a “hard” credit check and instructing a professional valuation of the property to ensure it provides adequate security for the loan. Simultaneously, you’ll need to instruct a solicitor to begin the conveyancing and legal work. While there are many moving parts, this is where a “steady hand” is most valuable. Taylors has been supporting Leicestershire buyers since 1992, providing the local expertise needed to guide you from that first viewing to the day you finally collect your keys.

Take the first step toward your new home

Securing a mortgage in principle is the foundation of a successful property search in Leicestershire. It provides the clarity you need to set a realistic budget and the credibility required to be taken seriously by sellers in competitive villages like Rothley and Quorn. By understanding what is a mortgage in principle UK lenders offer, you can explore the market with confidence, knowing your credit score is protected and your finances are in order.

Since 1992, Taylors has provided a steady hand for buyers across Charnwood and the surrounding villages. As an independent, family-run agency with over 30 years of local expertise, we pride ourselves on delivering honest, transparent guidance that puts your peace of mind first. We’re here to ensure your transition from a mortgage in principle to collecting your keys is as straightforward as possible.

Speak with our local experts for honest property advice

We look forward to helping you find your perfect place in our community and making your next move a success.

Frequently Asked Questions

Is a mortgage in principle a guarantee that I will get the loan?

No, a mortgage in principle isn’t a binding guarantee that you’ll receive the loan. It’s a conditional indication based on a high-level assessment of your finances. The lender only makes a formal offer after a full application, which includes a detailed affordability check and a professional property valuation. If your circumstances change or the property doesn’t meet their specific criteria, the lender can still decline your final application.

Can I get a mortgage in principle with a bad credit score?

You can still obtain an agreement with a poor credit history, though your options may be more limited. Some specialist lenders cater specifically to those with lower scores, provided you can demonstrate financial stability elsewhere. When looking at what is a mortgage in principle UK lenders offer for those with credit issues, it’s often helpful to speak with an independent broker who can identify which banks are most likely to accept your specific profile.

Do I have to take out a mortgage with the same lender who gave me the AIP?

You aren’t obligated to stay with the same lender who issued your initial certificate. It’s common for buyers to get an AIP from one bank to start viewing houses and then switch to a different provider if they find a better interest rate later. With over 7,400 mortgage products currently on the market, shopping around ensures you secure the most competitive deal for your new home in villages like Rothley or Mountsorrel.

How much does it cost to get a mortgage in principle in the UK?

Obtaining a mortgage in principle is typically free of charge. Most banks and building societies provide this service as a way to attract potential borrowers. While you won’t pay for the document itself, you should budget for other costs that follow, such as valuation fees or broker charges. Some brokers may charge an upfront fee for their advice, so it’s always wise to check their terms before you begin the assessment process.

What documents do I need for a mortgage in principle?

For the initial stage, you usually don’t need to provide physical documents. You simply need to provide accurate details of your gross annual income, monthly financial commitments, and your address history for the last three years. However, having your recent payslips and bank statements to hand is helpful. This ensures the figures you enter are precise, which prevents discrepancies when the lender eventually asks for proof during the full mortgage application.

Can I change the amount on my mortgage in principle later?

You can certainly adjust the amount on your certificate, but this usually requires a fresh assessment. If your income increases or you decide to put down a larger deposit, you can ask the lender to update the figure to reflect your new borrowing power. It’s important that the document remains accurate for your search. If the property price significantly exceeds your initial AIP, sellers in Quorn or Anstey may require an updated certificate before accepting your offer.

Does a mortgage in principle include the deposit amount?

The certificate focuses on the amount the bank is willing to lend you, but the application process will ask for your deposit figure. The lender uses your deposit amount to calculate the Loan to Value (LTV) ratio, which determines the interest rates available to you. While the AIP confirms your borrowing limit, your total purchase budget is the combination of this loan amount and the cash deposit you have saved for your Leicestershire move.

How long does it take to get a mortgage in principle online?

If you apply through a lender’s digital portal, you can often receive your certificate in under 15 minutes. Most automated systems use soft credit searches to provide an instant decision based on the data you submit. This speed is a major advantage for buyers in Leicestershire, allowing you to secure proof of funds on the same day you find a property you love, ensuring you don’t miss out in a fast-moving local market.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

Best Leicestershire Areas for First-Time Buyers: 2026 Guide

Best Leicestershire Areas for First-Time Buyers: 2026 Guide

With the average price for a first-time buyer property in Leicester sitting at £214,000 as of mid-2026, many are surprised to find that stepping onto the ladder is still remarkably achievable if you know where to look. We know the process feels daunting right now, especially with mortgage rates for a 5% deposit averaging around 4.97% and the rising costs in sought-after villages like Quorn. It’s easy to feel stuck between wanting a home with character and the reality of your monthly budget, leading to concerns about whether you are making a sound long-term investment.

This guide identifies the best areas in Leicestershire for first time buyers, focusing on locations that offer genuine value and vibrant community spirits. We’ll provide you with a clear shortlist of affordable spots like Sileby and Syston, professional reassurance on the 2026 market, and a straightforward look at the actual costs involved. By the end of this article, you’ll have the clarity needed to move from scrolling through listings to booking your first viewing with confidence, backed by over 30 years of local expertise in the Charnwood area.

Key Takeaways

  • Understand why Leicestershire’s property market remains robust compared to national trends, making it a secure choice for your first home investment in 2026.
  • Explore the best areas in Leicestershire for first time buyers, focusing on high-value locations like Sileby and Syston that offer excellent transport links and local amenities.
  • Learn why Charnwood’s commuter villages often provide better long-term resale value and more living space than city-centre alternatives.
  • Gain clarity on the financial preparation required to step onto the ladder, including the importance of securing a Mortgage in Principle early in your search.
  • See how 30 years of local village expertise can help you find a home that fits your lifestyle whilst ensuring your investment is protected for the future.

Why Leicestershire remains a top choice for first-time buyers in 2026

Leicestershire has carved out a reputation for market resilience that stands apart from the national average. While some regions across the UK experienced cooling prices throughout 2025, our local market maintained a steady, upward trajectory. According to HM Land Registry data from May 2026, the average price for a first-time buyer property in Leicester rose by 2.1% to £214,000. This stability provides a reassuring foundation for those looking to invest their hard-earned savings into a permanent home rather than continuing to pay rising rents.

The county offers a diverse mix of environments that appeal to varied lifestyles. If you want to learn more About Leicestershire and its unique geography, you’ll see why the blend of industrial heritage and rolling countryside is so attractive. For young professionals, the strategic transport links are a primary draw. The Midland Main Line provides efficient rail access to London and Sheffield, whilst the M1 corridor ensures that the rest of the Midlands is within easy reach. These connections mean you don’t have to sacrifice a career in the city to enjoy a quieter life in a Charnwood village.

The Charnwood advantage for new homeowners

The fringe of the Charnwood Forest remains one of the best areas in Leicestershire for first time buyers who value the outdoors. You can live within a short drive of Bradgate Park or the Outwoods without the premium price tag of more established rural hotspots. Many buyers are choosing villages like Mountsorrel or Birstall because they offer a genuine community feel. Local pubs and independent shops in these areas create a welcoming atmosphere that city-centre living often lacks. It’s about finding that balance where you can enjoy a Saturday morning walk in the forest and still be back in time for lunch at a local cafe.

Understanding 2026 market trends in the East Midlands

Current market dynamics are heavily influenced by the Bank of England’s decision to hold the base rate at 3.75% in July 2026. This has brought a level of predictability to mortgage products that was missing in previous years. We’ve seen a clear shift in preference amongst buyers; there is less interest in cramped city apartments and a growing demand for suburban houses with private gardens. For those with a 5% deposit, average mortgage rates of around 4.98% are making monthly repayments more manageable. Buying now often works out as a more cost-effective move than continuing to pay an average of £1,025 per month in rent, which has risen by 2.8% over the last year.

Top areas for value: Where your money goes further in Charnwood

Finding the best areas in Leicestershire for first time buyers often involves looking just a few miles down the road from the most expensive postcodes. While Rothley and Quorn are undeniably popular, villages like Sileby and Mountsorrel offer a very similar lifestyle for a more accessible entry price. Official Leicestershire property price data shows that whilst the county average is £296,000, there are still pockets within Charnwood where your deposit goes significantly further. These “middle-ground” villages provide the perfect balance of rural charm and practical amenities without the “Golden Triangle” price premium.

Sileby: A commuter village with a community heart

Sileby is a standout choice for those who need to commute but want a genuine village atmosphere. Its train station is a rare and valuable asset for a village of this size, providing direct links to Leicester, Loughborough, and Nottingham. Most buyers starting out here find excellent value in the Victorian terraces near the centre or the established semi-detached homes on the outskirts. The village is remarkably self-contained; you have traditional bakeries, local micro-pubs, and modern coffee shops all within walking distance. It’s a place where people tend to stay for the long term, which is always a good sign for future resale value.

Anstey and Syston: Strategic locations for growing families

Anstey is often called the “Gateway to Charnwood” because it sits perfectly between the city and the forest. It’s a favourite for young couples who need quick access to the A46 or M1 but want Bradgate Park as their local green space. Syston, by contrast, offers a more bustling, town-like feel. Its high street is incredibly active, featuring a wide variety of housing stock from 1930s semis to modern developments. In these areas, you can typically find a three-bedroom home for roughly £50,000 less than a comparable property in Rothley. This price gap allows you to secure a larger garden or an extra bedroom that might be out of reach in the more expensive neighbouring villages.

Mountsorrel also deserves a mention for its unique granite-village character. It serves as an excellent alternative to Quorn, offering similar riverside walks and heritage properties but often at a lower price point. If you’re finding it difficult to narrow down your search, we can send you a curated list of local homes that match your specific budget and requirements. Focusing on these high-value areas ensures you don’t overstretch your finances whilst still securing a home in one of the county’s most desirable districts.

Village life vs. City living: Comparing the long-term benefits

Choosing between a city-centre apartment and a village house is one of the biggest decisions you’ll face. Whilst the convenience of LE1 is tempting, the long-term benefits of Charnwood often outweigh the initial appeal of urban living. When we look at the best areas in Leicestershire for first time buyers, we aren’t just looking at the purchase price. We’re looking at what that money actually buys you in terms of square footage, privacy, and future growth. In the city, your budget might secure a modern two-bedroom apartment. However, in villages like Mountsorrel or Sileby, that same investment often stretches to a three-bedroom Victorian terrace with a private garden and easier parking.

These period properties offer a level of character and charm that new-build city blocks struggle to replicate. Beyond the aesthetics, village homes typically provide better air quality and immediate access to the county’s finest green spaces. This shift towards “space over speed” has become a defining trend in 2026, with more buyers prioritising a home office or a garden over proximity to a city-centre bar. The resale factor is also stronger in the villages. A house with a garden in a quiet cul-de-sac is almost always easier to sell than a flat in a saturated urban market.

The true cost of a city-centre flat

Many buyers overlook the ongoing financial commitments attached to leasehold properties. Monthly service charges and annual ground rent can add hundreds of pounds to your outgoings, significantly reducing your actual monthly budget. There is also the lingering complexity of cladding certificates and lease extensions which can complicate your resale down the line. Most village houses are freehold, meaning you own the land and the building outright with no hidden monthly fees. To understand the full picture before you commit, we recommend reading The True Cost of Moving House in Leicestershire: A 2026 Resource Guide.

Why Charnwood villages are a safer investment

Historical price stability in areas like Barrow upon Soar and Sileby makes them a reliable choice for your first purchase. These locations possess a “forever home” potential that city flats lack. Buyers often move into a village terrace and stay for years, eventually upgrading within the same community as their needs change. Local school catchments also play a vital role in protecting your property’s value. A home near a highly-rated primary school will always be in demand, regardless of wider economic shifts. If you’re looking slightly further afield for value, you might consider the lifestyle benefits of living in Melton Mowbray, which offers a similar balance of community spirit and investment security.

Best Leicestershire Areas for First-Time Buyers: 2026 Guide

Financial steps to secure your first Leicestershire property

Securing your first home requires more than just finding the right postcode; it demands a clear financial strategy. By the time you’ve identified the best areas in Leicestershire for first time buyers, you should already have your Mortgage in Principle (MIP) ready. This document proves to sellers in competitive villages like Rothley or Quorn that you’re a serious contender. With the Bank of England base rate holding at 3.75% as of July 2026, lenders are offering more stable products, but having that MIP in hand remains your strongest negotiation tool.

It’s also essential to budget for the costs that sit outside your deposit. For properties under £300,000, you’ll benefit from 0% Stamp Duty, which covers the majority of first-time buyer homes in Leicestershire. However, you must still account for conveyancing fees, buildings insurance, and moving costs. An independent agent can often help you find “off-market” opportunities in villages like Mountsorrel or Birstall before they hit the major portals, giving you a head start in a busy market.

Using a mortgage calculator for your search

We recommend using our mortgage calculator to filter your search by monthly cost rather than just the total purchase price. This helps you understand how current interest rates, which averaged 4.98% for a 5% deposit in August 2026, translate into your actual living costs. Choosing between a fixed-rate and a tracker mortgage is a significant decision in the current climate. Speaking to a local broker who understands the Charnwood market is invaluable; they can often access products tailored to the specific property types found in our villages.

Get expert advice on your first mortgage

Surveys and valuations: why they matter

There is a vital difference between a basic mortgage valuation and a comprehensive HomeBuyer Report. A mortgage valuation is for the lender’s benefit only, whilst a survey protects your investment. In older Leicestershire properties, particularly the Victorian terraces in Sileby or the granite cottages in Mountsorrel, common issues like rising damp or ageing roof structures can be costly if missed. Identifying these early allows you to renegotiate the price or plan for future repairs. Understanding these professional standards is just as important when the time comes for Selling Your Property: A Guide to Choosing the Best Estate Agents in Leicestershire, as it ensures you are working with experts who value transparency and thoroughness.

How Taylors Estate Agency supports your first move

Buying your first home is a significant milestone, and having a local expert by your side makes all the difference. We’ve been helping people find the best areas in Leicestershire for first time buyers since 1992. As an independent agency based in Rothley, we don’t answer to corporate shareholders; we answer to you. Our team treats every buyer as a future neighbour, providing the honest, transparent advice you need to make an informed decision. Whether you’re looking at a cottage in Mountsorrel or a modern semi in Sileby, our 30 years of experience ensures you’re supported at every stage.

We provide more than just a list of properties. Our role involves guiding you through the local nuances that national portals often miss. We’ll tell you which streets in Birstall have the best parking or which parts of Anstey are closest to the most sought-after school catchments. This depth of knowledge is why so many first-time buyers trust us to act as their “steady hand” throughout the purchasing process. We also provide access to a hand-picked network of trusted local solicitors and surveyors who understand the specific property types found across Charnwood.

The Taylors difference: local roots since 1992

Our independent status is our greatest asset. It allows us to offer a dedicated, flexible service that corporate city agents simply can’t match. We pride ourselves on total transparency, ensuring there are no hidden surprises during your purchase. Our team lives and works in the heart of Charnwood, giving us a genuine, personal connection to villages like Mountsorrel, Sileby, and Quorn. This isn’t just a market to us; it’s our home, and we want to help you make it yours too.

Next steps for your property search

The best homes in Charnwood often move quickly. To stay ahead, we recommend registering for our property alerts. This ensures you hear about new listings before they even reach the major national websites. You can also book a free consultation with our Rothley team to discuss your specific requirements in detail. We’ll help you narrow down your search based on your budget and lifestyle needs. If you’re currently renting but planning for the future, it helps to understand the wider market; for instance, you might find our guide on How Much Is My House Worth in Syston? A 2026 Guide to Property Values useful for comparing different local price points. Finding your first home is a journey, and we’re here to ensure it’s a successful one.

Finding a first home is about balancing your current budget with your future aspirations. By looking towards the best areas in Leicestershire for first time buyers, particularly the high-value villages across Charnwood, you can secure a property that offers both character and investment security. The stability of our local market throughout 2026 shows that whilst national headlines may vary, villages like Sileby and Mountsorrel remain excellent choices for long-term growth.

Success in this market comes down to being well-prepared and having a trusted local guide by your side. We’ve been independent experts in this region since 1992, providing the steady hand and deep local knowledge required to help you step onto the ladder. Whether you need a free, no-obligation property valuation or simply want an honest chat about which village suits your lifestyle, we’re ready to help.

Contact our friendly Rothley team for honest local advice on your first move

We’re excited to help you find a place in Charnwood that you’ll be proud to call home for years to come.

Frequently Asked Questions

What is the average house price for first-time buyers in Leicestershire in 2026?

The average price paid by first-time buyers in Leicester reached £214,000 in May 2026, whilst the broader county average sits at £296,000. These figures indicate that the best areas in Leicestershire for first time buyers are often found in Charnwood’s “middle-ground” villages. Locations like Sileby and Syston offer a blend of affordability and amenities that are increasingly difficult to find in the city centre.

Which Leicestershire villages have the best transport links for commuters?

Sileby and Barrow upon Soar are standout choices because they both feature their own train stations on the Midland Main Line. This provides direct, efficient rail access to Leicester, Loughborough, and Nottingham. For those who prefer to drive, Anstey is often favoured due to its immediate proximity to the A46 and M1, allowing for easy travel across the entire East Midlands region.

Is Sileby a good area for first-time buyers?

Sileby is widely considered one of the best areas in Leicestershire for first time buyers because it combines excellent rail links with a high concentration of affordable Victorian terraces. The village is remarkably self-sufficient, boasting local bakeries, micro-pubs, and independent shops. It offers a genuine community atmosphere that provides better long-term value and “forever home” potential than many city-centre developments.

How much deposit do I need to buy a house in Charnwood?

You typically need a minimum deposit of 5% of the property’s purchase price, though a larger amount often secures more competitive interest rates. For a home priced at the city average of £214,000, a 5% deposit would be £10,700. The 95% Mortgage Guarantee Scheme remains active in early 2026, helping those with smaller savings step onto the ladder with a 5% deposit.

Are there any specific grants for first-time buyers in Leicestershire?

Several initiatives are available in 2026, including the First Homes Scheme which offers new-build properties at a 30% discount for local buyers. Shared Ownership is another popular option across the county, allowing you to purchase a share of a home and pay rent on the remainder. Additionally, the 0% Stamp Duty threshold for first-time buyers remains at £300,000, covering most entry-level homes in the area.

What are the best primary schools in the Charnwood area?

Charnwood features many highly-regarded primary schools, including Rothley Primary Academy, St Bartholomew’s in Quorn, and Christ Church in Mountsorrel. These schools are a significant draw for young families, often protecting the resale value of nearby homes. It’s vital to check specific catchment areas before you buy, as these boundaries can change and directly impact your child’s placement and the property’s desirability.

Should I buy a new-build or a period property in Leicestershire?

New-builds offer modern energy efficiency and incentives like the First Homes Scheme, but period properties often provide more character and larger garden spaces. Older Victorian terraces in villages like Sileby or granite cottages in Mountsorrel have a proven track record of holding their value well. Your choice should depend on whether you prioritise lower monthly running costs or the unique charm and plot size of a traditional home.

How long does the house-buying process typically take in Leicestershire?

The process usually takes between 12 and 16 weeks from the point your offer is accepted to the day you move in. This timeline depends on the length of the property chain and how quickly the legal and survey stages are completed. Having a Mortgage in Principle ready and instructing an experienced local solicitor early can help keep the momentum moving and reduce the likelihood of unnecessary delays.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager