Posted on

How to Make the Selling Process Less Stressful

How to Make the Selling Process Less Stressful

A home sale feels more manageable when you know what is coming next. Selling can bring uncertainty about viewings, negotiations, delays and a property chain, often alongside work and everyday responsibilities. Knowing how to make the selling process less stressful starts with clear expectations, manageable actions and regular communication, so you can focus on the decisions that matter.

This guide covers the main stages of a sale and practical ways to prepare for each one. You’ll find tips for organising viewings and paperwork, tracking progress and responding calmly if timings change or negotiations become difficult. A sale will not always go exactly to plan, but a clear point of contact and an understanding of your options can make uncertainty easier to manage.

For homeowners in Rothley, Charnwood and nearby Leicestershire villages, local guidance can help make advice relevant to your property and plans. We’ll look at how a clear plan and supportive communication can help you stay involved and in control throughout your move.

Key Takeaways

  • Separate the tasks you can plan from decisions and timing changes that are outside your control.
  • Understand the main stages of a home sale, from valuation and marketing through to offers and progression.
  • Decide which parts of selling you want to manage yourself and where estate agent support could help.
  • Use a simple weekly routine and realistic viewing arrangements to keep sale-related tasks manageable.
  • Learn how to make the selling process less stressful with clear communication and local guidance suited to your circumstances.

Why can selling a home feel stressful, and what can you control?

Selling brings financial decisions, practical jobs and personal feelings together. You may be preparing a much-loved property for viewings while thinking about where you’ll live next, when to move and how an offer fits your plans. That combination can feel demanding. Stress can affect people physically and psychologically; understanding the biological and psychological impacts of stress helps explain why uncertainty around a major change can weigh on you.

You can plan some parts of a sale: preparing the property, setting priorities, arranging access for viewings and keeping track of questions. Other things depend on buyers and the people involved later in the transaction. A buyer may take time to decide, or timings may change. A sale may involve a chain, but not every move does, and no two transactions follow exactly the same timetable.

Clear expectations cannot prevent every delay, but they can reduce avoidable uncertainty. One practical way to make the selling process less stressful is to separate the next action you can take from an outcome you cannot control. That keeps your attention on useful steps rather than trying to predict every possible turn.

Which parts of selling tend to create the most pressure?

Pressure often builds around five areas: preparing the property, fitting in viewings, weighing up offers, getting clear updates and waiting for progress after an offer is accepted. Each stage raises different questions, from what to tidy away to whether an offer’s proposed timing works for you. The most difficult stage will depend on your circumstances, responsibilities and priorities.

For example, a Rothley seller working from home might find frequent viewing arrangements disruptive, while another household may be more concerned about choosing between an offer and the timing of an onward move. These are examples, not a rule about local sales. Identifying the specific pressure makes it easier to decide what planning or support could help.

What can a seller influence from the outset?

Before marketing begins, write down what matters most to you: your preferred moving window, practical limits on viewings, what you need from an offer and how you’d like to receive updates. Ask what each stage involves and who will keep you informed. Agreeing these preferences early gives everyone a useful reference point if plans or circumstances change.

  • Prepare: List the jobs to complete before photography and viewings.
  • Prioritise: Note which parts of an offer matter to you beyond the figure alone.
  • Communicate: Agree a practical way to receive updates and raise questions.
  • Record: Keep one written list of questions, answers and agreed actions.

Preparation helps you feel ready, but it cannot guarantee a buyer’s decision or prevent changes involving other parties. Keeping questions in one place, rather than trying to remember every conversation, makes it easier to follow up and means you do not have to hold every detail in your head.

How does a clear selling process make the next steps easier?

A sale can feel less daunting when you know what each stage is for and which decisions may come next. Treat the process as a series of milestones rather than a fixed timetable: progress and timing depend on the property, the people involved and individual circumstances. This outline can help you see where you are and what information to gather.

  1. Valuation and planning: Discuss the property, its features and your priorities, then consider an asking price and prepare for marketing.
  2. Marketing: Agree how the property will be presented and advertised so potential buyers can assess what it offers.
  3. Viewings: Buyers visit to look around and decide whether the home suits their needs. Feedback can help you understand their response.
  4. Offers: Review the terms and circumstances of an offer before deciding how to respond.
  5. Progression: Once an offer is accepted, updates and information need to be coordinated as the transaction advances.

These milestones provide orientation, not a promise that every sale will follow the same order or reach a particular outcome. A buyer may need time to consider, an offer may not be accepted, and circumstances can change. Knowing the purpose of each stage still helps you identify your next question, rather than feeling you have to solve the whole sale at once.

What should sellers expect before marketing begins?

Use early conversations to clarify your priorities, understand the reasoning behind the valuation and gather useful details about the property. Think about what makes the home distinctive, any improvements or alterations, and practical arrangements that could affect viewings. Preparing this information helps you make grounded decisions instead of having to search for details in a rush when interest comes in.

Before agreeing the next steps, write down anything you want explained, such as how the asking price was considered or what will happen once marketing starts. A practical home valuation preparation checklist can help you organise property details and questions ahead of a valuation discussion. Taylors’ wider Leicestershire selling guidance can provide further context on the stages, while your plan should reflect your home and priorities.

How do viewings, offers and progression differ?

A viewing gives a buyer the chance to assess the property; it is not a commitment to make an offer. If an offer arrives, look beyond the headline amount. Consider how it fits your plans and what you know about the buyer’s position, then ask for any details you need to make an informed decision. You remain responsible for deciding whether to accept, decline or respond with different terms.

Progression begins after an offer is accepted. It involves keeping track of updates and helping information move between the people involved as the transaction advances. The legal work is handled by the parties’ conveyancing representatives, while clear communication helps you understand what has happened and what remains outstanding. Knowing the difference is part of how to make the selling process less stressful: each stage has its own purpose, so you can focus on the decision or action in front of you.

If talking through your property’s likely sale stages would help you plan, you can discuss your selling plans with Taylors.

Should you manage a sale alone or use estate agent support?

Some sellers prefer to manage enquiries and viewings themselves; others value having an agent coordinate these tasks and keep communication moving. The right approach depends on your time, comfort with handling buyer questions and the support you would find useful. Using an agent does not mean handing over control: you remain responsible for key choices, including whether to accept an offer.

TaskYour rolePotential agent supportQuestion to consider
EnquiriesRespond to buyers and answer questionsHandle enquiries and share relevant detailsCan I respond promptly around my other commitments?
ViewingsArrange access and prepare the propertyCoordinate appointments and provide feedbackHow much flexibility do I have during the week?
OffersWeigh up terms and decide how to respondPass on offers and help clarify the buyer’s positionWhat matters most to me beyond the amount?
UpdatesKeep track of questions and actionsShare updates and help coordinate communicationWhat update routine would work for me?

Which tasks could take more time when selling independently?

Handling a sale yourself can mean fielding enquiries, finding suitable times for viewings and keeping notes on buyer feedback, while also preparing the property and managing your usual commitments. The workload depends on the home, the level of interest and your availability. You may be well placed to take this on, or you may find that coordinating each contact takes more time than expected.

How can local agent support ease coordination?

Taylors’ residential sales service supports sellers across the process, from presenting a home to managing buyer communication and sharing progress. Agreeing how you’ll receive updates and where to send questions helps keep responsibilities clear, particularly if several people are involved. Useful support clarifies responsibilities while leaving important decisions with you.

For a seller in Rothley or elsewhere in Charnwood, local guidance can help make conversations about a property relevant to its setting and the owner’s plans. If you’re comparing your options, consider which tasks you want to handle personally and which you’d prefer to discuss with an agent. A guide to choosing estate agents in Leicestershire can help you identify useful questions, such as how communication is handled and what support is included. The right arrangement is the one that fits your needs, not a particular way of selling.

To talk through the kind of support that could suit your plans, discuss selling your home with Taylors.

How to Make the Selling Process Less Stressful

What practical habits can make selling less stressful day to day?

A few repeatable habits can stop a sale from taking over your week. Set aside a short time to review what has changed instead of checking messages constantly or trying to remember every conversation. Keep one shared record, whether a notebook or digital document, for dates, contacts, viewing feedback, outstanding questions and agreed actions. If someone else in your household is involved, make sure they know where to find it.

One up-to-date action list helps you avoid relying on memory during a busy move. A simple weekly check-in could include:

  • Reviewing messages and noting new updates.
  • Adding questions you want answered and recording who will follow them up.
  • Checking dates for viewings or other agreed actions.
  • Crossing off completed tasks and choosing the next practical step.

Keep the list focused. The aim is not to create extra admin, but to give you one reliable place to see what is happening and what still needs attention. This is a practical way to make the selling process less stressful, particularly when you’re balancing a move with work and home life.

How can you prepare for viewings without disrupting every day?

Agree viewing windows that fit your household’s routine, including work, school runs and arrangements for pets. A manageable reset might involve clearing access, quickly tidying the main living areas and putting away personal essentials you’d rather keep private. You do not need to aim for a show home every day. A short, repeatable routine is easier to maintain than last-minute preparation before every appointment.

If plans change, update the person arranging the viewing as early as you can and suggest another suitable time. Clear boundaries make it easier to accommodate interest without feeling that your whole day must remain open.

How should sellers handle uncertainty and changing plans?

When an update raises new questions, note three things: what you know, what is still outstanding and who is expected to provide the next update. For example, if a proposed date changes, record what has changed and which decisions depend on the revised timing. This makes your next conversation more specific and helps separate confirmed information from assumptions.

Before reacting, revisit your priorities. Consider what matters most to you now, which options remain open and what you need clarified before deciding. Buyer decisions, other parties and timings can change, so do not treat an early estimate as a guarantee. Focus on the next action you can take and add it to your shared record.

Small routines will not make every part of a sale predictable, but they can reduce the mental load of tracking details and adapting to new information. A regular review, realistic viewing arrangements and a clear record give you a steadier way to manage the moving parts.

Talk through your home-selling plans with Taylors

How can Taylors help make selling in Charnwood feel more manageable?

Taylors is an independent estate agency based in Rothley, supporting residential sellers across Leicestershire. Local guidance makes it possible to discuss your property, your plans and the questions you need answered, rather than treating every move as identical. You can also explain how you prefer to receive updates, making communication easier to fit around your day-to-day responsibilities.

Taylors supports sellers in Rothley, Mountsorrel, Anstey, Sileby, Syston, Quorn and Barrow upon Soar, as well as elsewhere in Leicestershire. A local perspective can inform a conversation about your home’s features and circumstances without relying on broad assumptions about prices or market conditions. Taylors has been established since 1992; that history provides context for its local knowledge, not a promise of a particular sale result.

What does local guidance mean for sellers around Rothley?

It means having the chance to discuss the details that make your property and plans distinct. You might want to explain changes you’ve made to the home, ask how its features could be presented to buyers or talk through practical limits on viewing arrangements. These details help shape relevant advice, while you remain involved in decisions about how and when to proceed.

Clear communication matters too. Raise questions as they arise and agree how you’d like updates shared, so you can keep track of what has been discussed and what still needs attention. Local insight is most useful when it relates to your situation, not when it is presented as a blanket prediction about what will happen next.

What is a low-pressure first step if you are considering a move?

Start by gathering the questions you’d like to discuss. These might include your preferred timing, what matters most in your next move, which property details could affect a sale and what you want to understand before making decisions. You do not need to have every answer ready. A conversation can help organise your thoughts and clarify which options are worth considering.

A free property valuation can be a useful early discussion about your home and its potential sale, without obliging you to put it on the market. It gives you an opportunity to ask informed questions and think through possible next steps at a pace that suits you. If you’re considering how to make the selling process less stressful, beginning with a clear conversation can make the choices ahead easier to assess.

If you’re thinking about selling in Rothley, Charnwood or the surrounding Leicestershire villages, you’re welcome to Talk to Taylors about your next steps.

Take your next step with confidence

You do not need to have every detail of your move settled before taking a first step. Start with one question you’d like answered, such as what to prepare or how your preferred timing might shape your plans. A focused conversation can turn a broad idea into a clearer decision, without requiring you to commit to selling before you’re ready.

Learning how to make the selling process less stressful often comes down to choosing an approach that fits your life, rather than trying to control every outcome. Give yourself room to consider advice, weigh up your priorities and decide what feels right. Taking the process one decision at a time can help you keep sight of what matters to you.

Talk to Taylors about your move

A thoughtful start can make the next decision feel more manageable. When you’re ready, take it at your own pace.

Frequently Asked Questions

How can I make selling my house less stressful?

Reduce avoidable pressure by deciding which choices need thought or discussion before they arise. If you share ownership, for example, agree how you’ll handle a decision that needs everyone’s input, such as responding to a revised offer. You could also set aside a regular time for sale-related decisions, rather than letting every new message interrupt work or family time.

What is the most stressful part of selling a house?

There is no single stage that is hardest for everyone. The emotional side can be especially demanding if you’re selling a long-time family home, while practical pressures may centre on fitting a move around work or caring responsibilities. If several people are affected, make space to talk about what each person finds difficult. That can help avoid misunderstandings when decisions arise.

Can an estate agent reduce the stress of selling a home?

An agent can offer a professional perspective on how buyers are responding to a property and help you consider possible next steps. Before instructing an agent, read the proposed agency agreement carefully so you understand the service and terms you’re agreeing to. This gives you a clearer basis for deciding whether the arrangement suits you, while keeping choices about your home and any offer in your hands.

What happens if a buyer changes their mind after making an offer?

If a buyer withdraws, speak to your conveyancer about any legal implications and what action is appropriate at that point. Your estate agent can explain the marketing position and discuss practical options for finding another buyer. Keep major commitments, such as booking removals or giving notice, under review until you’ve received advice on the status of the transaction and your own circumstances.

Should I accept the first offer on my property?

Not necessarily. Before responding, make sure you understand any conditions attached to the offer and the buyer’s position, including whether they need to sell another property or arrange a mortgage. These details can affect how an offer fits your plans, but they do not make the decision for you. Ask your agent to clarify anything unclear, then consider the full proposal before replying.

How often should I expect updates while selling my home?

The useful frequency depends on what is happening in your sale. You might want contact after a viewing, when an offer arrives or when an issue needs your attention. If an update is expected from someone else, ask what the next step depends on and when it would be sensible to follow up. That helps you distinguish a genuine hold-up from a quiet period.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

How Much Can I Borrow? 2026 UK Affordability Guide

How Much Can I Borrow? 2026 UK Affordability Guide

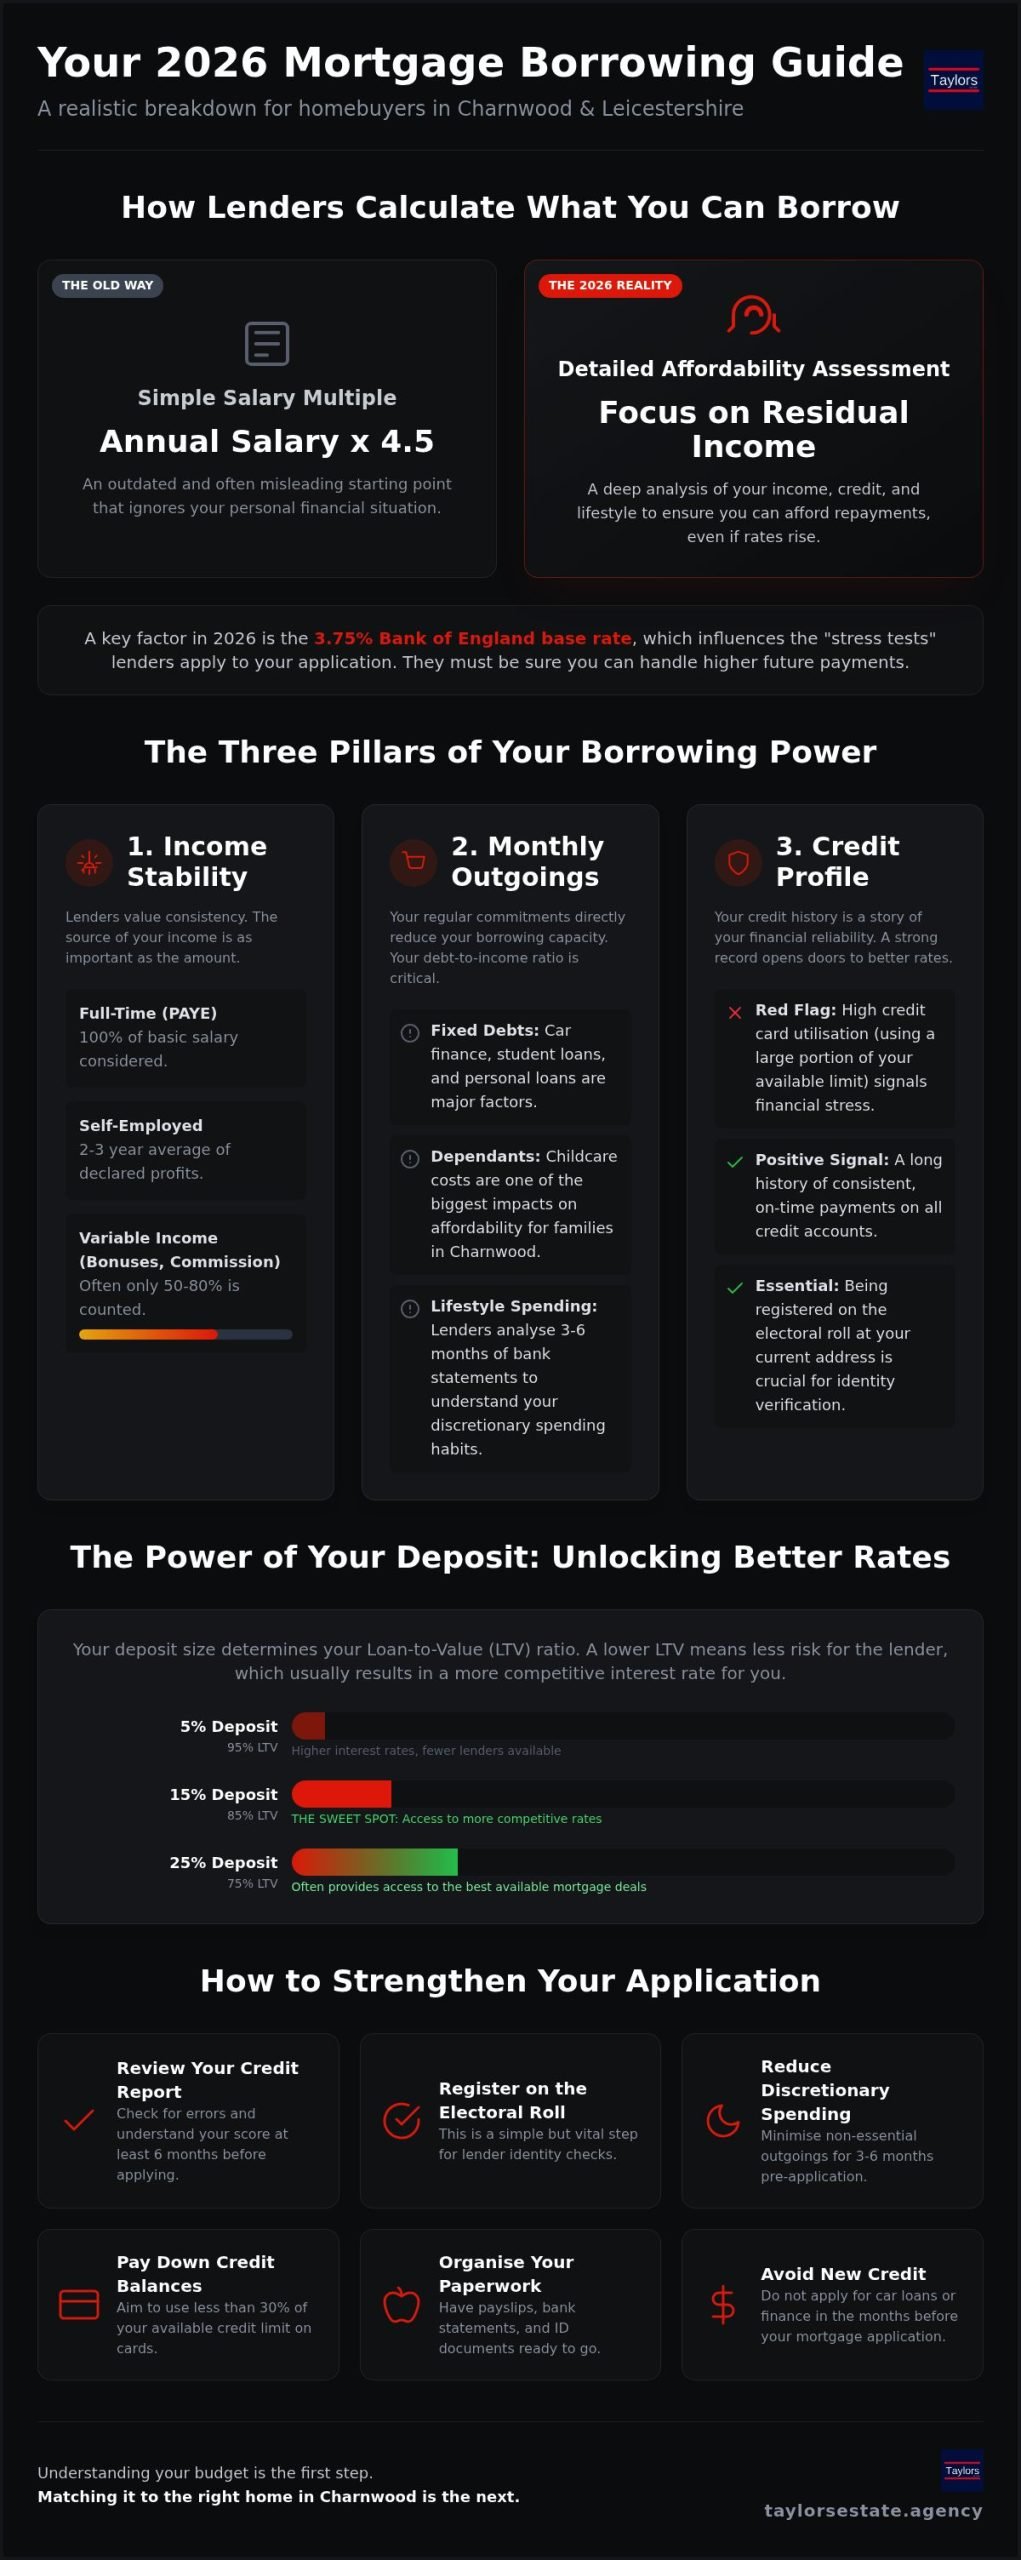
Why does one website tell you that you can afford a detached home in Quorn, while another suggests you’re limited to a small apartment in the city centre? It’s a common frustration because determining how much can I borrow mortgage UK has shifted from a simple salary calculation to a complex assessment of your daily lifestyle. You’ve likely spent hours on generic calculators only to end up more confused by conflicting results and the impact of the 3.75% Bank of England base rate on your monthly budget.

We understand that this uncertainty makes planning your move to Rothley or Mountsorrel feel like a guessing game. This guide breaks down the realistic factors lenders use in 2026, from the standard salary multiple rules to the way your credit history and monthly outgoings truly impact your capacity. We will explain how current interest rates affect your repayments and provide a clear roadmap to strengthen your financial profile. By the end, you’ll have the knowledge to start viewing properties in Charnwood with a budget that’s grounded in reality and professional insight.

Key Takeaways

  • Learn how lenders calculate how much can I borrow mortgage UK by moving beyond simple salary multiples to look at your specific lifestyle and monthly commitments.
  • Understand why your discretionary spending and credit history are just as important as your annual income when banks assess your affordability in 2026.
  • Identify the “sweet spot” for deposit sizes, typically between 10% and 15%, to secure more competitive interest rates and increase your overall borrowing power.
  • Discover practical steps to improve your financial profile before applying, such as ensuring you are on the electoral roll and managing your outgoings early.
  • See how matching your budget to specific Charnwood locations requires a deep understanding of local market values and moving costs, a speciality of Taylors Estate Agency.

Understanding the UK Mortgage Borrowing Landscape in 2026

The UK mortgage industry has evolved significantly over the last few years. While many buyers still start their journey by multiplying their gross annual income by 4 or 4.5, this is rarely the final figure. Lenders now use sophisticated algorithms to determine how much can I borrow mortgage UK, focusing on your ability to maintain payments even if life throws a curveball. The Financial Conduct Authority (FCA) oversees these standards to ensure lending remains responsible, preventing the market from returning to the risky practices of the past.

There is a vital distinction between what a bank is willing to lend and what you can comfortably afford each month. In 2026, with the Bank of England base rate sitting at 3.75%, your “paper” affordability might look different from your bank balance reality. A high salary is a great foundation, but it’s only one piece of the puzzle. We often see buyers in Rothley who are surprised that their maximum loan is lower than expected because of high commuter costs or existing financial commitments.

The Salary Multiple vs. Affordability Testing

Lenders prioritise residual income in their 2026 assessments. This is the money left over after you’ve paid for essentials like utilities, council tax in Charnwood, and groceries. Even if you earn a substantial wage, high childcare costs or significant personal debt will reduce your maximum loan. Banks also apply stress tests, calculating whether you could still manage repayments if interest rates were to climb several percentage points higher than your current deal. This ensures you won’t lose your home if the economic climate shifts during your fixed term.

How Your Employment Type Affects the Calculation

Your income’s stability is just as important as the total amount. Full-time PAYE employees usually have the simplest path, with lenders taking 100% of their basic salary into account. However, for those working in Leicestershire’s thriving self-employed sector or on fixed-term contracts, the rules are more nuanced. Following the FCA’s recent consultation on mortgage rules, some lenders now offer more flexibility for those with variable incomes. They may look at a two or three-year average of your accounts. Bonuses, commissions, and overtime are often shaded, meaning a bank might only count 50% to 80% of that income towards your total borrowing capacity.

Critical Factors That Influence Your Borrowing Capacity

Your borrowing capacity isn’t a static figure etched in stone. It’s a moving target shaped by what we call the “big three”: your income, your outgoings, and your credit score. When you ask how much can I borrow mortgage UK, you’re really asking how a lender views your financial reliability. Banks in 2026 are particularly focused on your debt-to-income ratio. This is a simple calculation of your monthly debt commitments against your gross earnings. If you have dependent children or existing financial commitments like car leases; these will naturally reduce your total borrowing power.

Lenders now scrutinise discretionary spending with a fine-tooth comb. They aren’t just looking at whether you can pay the mortgage today; but whether you can sustain it if life becomes more expensive. If you’re looking at homes in Rothley or Quorn; understanding these nuances early can save significant stress later. If you want to see how your current debts might change your outlook; a mortgage affordability calculator is a brilliant place to start your research.

The Role of Your Credit Profile

Your credit score is about more than just paying your bills on time. It’s a snapshot of your relationship with money. Lenders look for patterns; such as how much of your available credit you actually use. High credit card utilisation; even if you pay the minimum every month; suggests a reliance on debt that banks find off-putting. We recommend that buyers in Mountsorrel and Birstall organise their finances at least six months before starting their search. This means avoiding new credit applications; such as furniture finance or car loans; and keeping your balances low. If you’re wondering how your specific profile might affect your chances; send us a quick message for some honest local advice.

Assessing Your Monthly Expenditure

Lenders divide your bank statements into essential and non-essential costs. Essentials are the non-negotiables; student loans, car finance, and childcare costs. For many families in Charnwood; childcare is often the heaviest weight on an application. Then they look at your lifestyle choices. Discretionary spend is the primary lever for 2026 mortgage approvals. By reducing non-essential outgoings like premium subscriptions or frequent dining out in the months leading up to your application; you effectively increase your “paper” affordability. This demonstrates to the lender that you have the surplus income necessary to handle the 3.75% base rate environment comfortably.

Loan-to-Value (LTV) and Its Impact on Your Purchase

Loan-to-Value, or LTV, is the percentage of the property’s value that you are looking to borrow. If you are buying a home in Rothley for £400,000 and have a £40,000 deposit, your LTV is 90%. This figure is a critical component when calculating how much can I borrow mortgage UK because it determines which interest rate tiers you qualify for. Lenders view a lower LTV as a lower risk; which often results in more generous borrowing limits and cheaper monthly repayments.

In the 2026 market; the “sweet spot” for many buyers in Leicestershire is a 10% or 15% deposit. While the Freedom to Buy scheme has made 95% mortgages a permanent fixture; these high-LTV products usually come with higher interest rates to offset the lender’s risk. By reaching an 85% LTV; you often move into a different pricing bracket that can save you thousands of pounds over the life of your fixed term. Property valuations in sought-after areas like Mountsorrel are stable; but lenders will always base their final loan offer on their own surveyor’s valuation rather than the agreed purchase price.

How Deposit Size Changes Your Monthly Costs

The difference between a 95% and an 80% LTV mortgage is about more than just the initial cash you put down. A 95% mortgage might carry an interest rate significantly higher than the average 5-year fixed rate of 5.66%. Stepping up to an 80% LTV can unlock rates that are much closer to the base rate; drastically reducing your monthly outgoings. If you are planning to sell an existing property to fund your next move; it’s vital to get an accurate starting point. You can check how much is my house worth in Syston to understand how much equity you could potentially port over to your new purchase.

Property Types and Lender Restrictions in Leicestershire

The type of property you choose in Charnwood can also dictate your LTV requirements. Period properties in Quorn or Anstey are beautiful; but they often require more detailed surveys. If a property has non-standard construction; such as a thatched roof or timber frame; some lenders may reduce the maximum LTV they are willing to offer. They might even require a larger deposit to protect their security. The property itself acts as the final collateral for the loan; so if the building is considered high-maintenance or difficult to resell; it directly impacts the bank’s willingness to lend the full amount you’ve requested.

Practical Steps to Maximise Your Borrowing Power

Preparing for a mortgage application is a marathon; not a sprint. If you want to accurately determine how much can I borrow mortgage UK; you need to look at your finances through a lender’s eyes at least six months before you intend to buy. Start by ensuring you’re on the electoral roll at your current address. This is a simple but vital step for identity verification; as a lack of registration can lead to automatic rejections or frustrating delays that might cost you a property in a competitive village like Quorn or Woodhouse Eaves.

Gathering your documentation early is equally important for a smooth process. You’ll generally need your last three P60s and three months of bank statements to prove your income and spending habits. For the self-employed in Leicestershire; have your last two years of tax calculations (SA302s) and tax year overviews ready. Reducing existing debt before your search begins is also a primary lever; as it improves your debt-to-income ratio and increases your monthly disposable income. This proactive approach shows lenders you’re managing your finances responsibly. Having this data at your fingertips ensures your application is based on accurate; verifiable figures rather than estimates.

Financial preparation also involves a realistic look at your lifestyle. Lenders in 2026 are looking for stability and predictability. If you’ve recently changed jobs or have gaps in your employment history; be prepared to explain these clearly. By organising your finances well in advance; you position yourself as a low-risk borrower; which is essential for securing the most competitive rates in the Charnwood market.

Financial Housekeeping Before You Apply

Lenders prefer a “clean” financial history. Closing credit cards you don’t use reduces the total credit available to you; which banks see as a potential risk. Try to stay out of your overdraft for three months and avoid large purchases like new cars. These commitments appear as monthly outgoings; directly reducing your borrowing capacity. Maintaining transparent spending makes it much easier for an underwriter to approve your loan.

Contact our team for a personal consultation on your local property search

Securing a Decision in Principle (DIP)

A Decision in Principle (DIP) is an initial assessment confirming a lender’s willingness to lend a specific amount. While it isn’t a full mortgage offer; it shows sellers in Rothley or Anstey that you’re a prepared buyer. A DIP is the “currency of trust” when making an offer on a competitive property. It proves you’ve researched your budget and have the backing to move forward with confidence; which is vital in the 2026 market where how much can I borrow mortgage UK remains a key concern for many.

How Much Can I Borrow? 2026 UK Affordability Guide

Knowing your borrowing limit is the foundation; however, applying that figure to the Charnwood market is where the real work begins. A generic calculator won’t tell you that a budget stretching to a semi-detached in Birstall might secure a more spacious detached property in Sileby. We believe in a balanced approach where your financial capacity meets your lifestyle aspirations. It’s about more than just the mortgage; you must also account for the true cost of moving house in Leicestershire, including updated stamp duty thresholds and local surveyor fees.

When you finally determine how much can I borrow mortgage UK, the next step is matching that loan to the right postcode. This is where local expertise becomes your most valuable asset. We support our clients from the initial valuation through to the day they collect their keys; ensuring every decision is backed by evidence and 15 years of local market experience. Understanding how much can I borrow mortgage UK is only half the battle; the other half is knowing where that money goes furthest in the current landscape.

Why Local Knowledge Trumps Online Calculators

Online tools provide a rough estimate; but they lack the nuance of local market dynamics. For instance, some lenders are more cautious about specific property ages or construction types in villages like Barrow Upon Soar. An experienced agent understands these lender attitudes and can guide you toward homes more likely to pass a valuation survey without complications. We help you find the right balance between borrowing and the practical reality of maintaining a home in a specific neighbourhood. This ensures you don’t just buy a house; but a home you can afford to enjoy for years to come.

Starting Your Journey in Rothley

Our team has seen every common pitfall; from over-borrowing to missing out on properties due to a lack of preparation. We offer a “steady hand” approach; providing honest advice that prioritises your peace of mind. Whether you’re moving within Cropston or looking to settle in Thurcaston; we act as your guide through the entire process. If you have questions about specific village values or need a sounding board for your plans; you can get in touch via WhatsApp for personalised advice.

Taking Your Next Steps in the Charnwood Market

Determining how much can I borrow mortgage UK is a strategic look at your financial life through a lender’s eyes rather than a simple calculation. We have explored how 2026 affordability models prioritise your daily spending habits and how reaching specific deposit thresholds can significantly lower your monthly costs. By taking proactive steps to manage your credit and organise your documentation; you build a foundation of trust with potential lenders before you even step inside a property.

Since 1992; Taylors Estate Agency has acted as a trusted local guide for buyers across Rothley and the wider Charnwood area. Our independent status and 15 years of professional experience mean we offer honest; practical advice tailored to the villages we know so well. We are committed to helping you find a balance between your borrowing capacity and the lifestyle you want to lead in Leicestershire.

Ask our local experts for honest mortgage advice on WhatsApp

We are here to provide the steady hand you need to move forward with confidence. Your journey toward a new home starts with clear; evidence-based planning and a partner who understands the local landscape.

Frequently Asked Questions

Is the 4.5 times salary rule still accurate for UK mortgages in 2026?

The 4.5 times salary rule remains a standard benchmark for the UK mortgage industry in 2026; however; it is no longer the sole deciding factor. While many lenders use this as a baseline; others may offer up to 5.5 times your income if you have a high salary or minimal outgoings. Your final offer depends heavily on detailed affordability stress tests that look at your net income after all essential living costs are deducted.

Can I borrow more if I have a larger deposit?

A larger deposit improves your Loan-to-Value (LTV) ratio; which often unlocks more competitive interest rates. While a bigger deposit doesn’t automatically increase the multiple of your salary you can borrow; lower interest rates reduce your monthly repayment costs. This can lead to a more favourable affordability assessment; potentially allowing you to secure a slightly larger loan because the monthly commitment is more manageable for your household budget.

How do my monthly outgoings affect my mortgage borrowing amount?

Your monthly outgoings are subtracted from your take-home pay to determine your “residual income.” Lenders scrutinise everything from car finance and student loans to childcare costs and regular subscriptions. If your fixed monthly commitments are high; the amount you can borrow will decrease; as the lender must ensure you have enough surplus cash to cover your mortgage payments even if interest rates were to rise during your term.

Will being self-employed reduce how much I can borrow?

Being self-employed doesn’t inherently reduce your borrowing capacity; provided you can supply two to three years of certified accounts or SA302 forms. Lenders typically average your net profit over this period to determine your income. Some specialist lenders are now more flexible for those with only one year of trading; though they may require a larger deposit to offset the perceived risk of a variable or recently established income.

Does a student loan impact my mortgage affordability?

Yes; student loan repayments are treated as a monthly commitment that reduces your net take-home pay. When calculating how much can I borrow mortgage UK; lenders factor in these deductions just like any other debt or tax. While a student loan won’t prevent you from getting a mortgage; it will slightly lower the maximum loan amount available to you because it reduces the total disposable income you have available for repayments.

How much can I borrow if I am buying with a partner?

When buying with a partner; lenders typically combine your gross annual incomes and apply a multiple; usually between 4 and 4.5 times the total. This significantly increases your borrowing power compared to a single application. Both applicants undergo the same rigorous credit checks and expenditure assessments; so high debts or poor credit history from one partner can still impact the overall amount the lender is willing to offer for your joint purchase.

What happens if the property valuation is lower than my mortgage offer?

If a lender’s valuation comes in lower than your agreed purchase price; they will only lend based on that lower figure. This is known as a “down valuation.” In this scenario; you would need to increase your deposit to cover the shortfall or renegotiate the price with the seller. This is why understanding local market values in areas like Rothley or Quorn is vital before making an offer on a home.

Should I use an online mortgage calculator before viewing houses?

An online how much can I borrow mortgage UK calculator is a helpful starting point for a rough estimate; but it shouldn’t be your final word. These tools often miss the nuances of 2026 lender behaviour and your specific outgoings. We recommend obtaining a Decision in Principle (DIP) before viewing properties in Charnwood; as this provides a more accurate reflection of your actual budget and demonstrates your serious intent to sellers.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager