Posted on

Mortgage affordability calculator: how much could you borrow?

Mortgage affordability calculator: how much could you borrow?

A mortgage affordability calculator can give you a useful starting figure, but it can’t promise that a lender will offer you that amount. If you’re deciding which homes to view and what repayments might fit your budget, treat the result as an estimate, not a decision.

Taylors’ mortgage calculator can help you make an early estimate before you start viewing. This guide explains what the figure can tell you, why a lender’s assessment may differ, and how income, regular spending and existing borrowing can affect what you may be able to borrow. It also covers the difference between a borrowing estimate and a realistic home-buying budget, including the costs of moving.

For buyers in Charnwood, local prices can help put the numbers in context. ONS figures for July 2026 put the average first-time buyer price at £232,000, while average prices were £217,000 for terraced homes and £133,000 for flats or maisonettes. These are broad guide figures, not a measure of what every property costs. Use them as context while setting a grounded search budget for Rothley, nearby villages and across Leicestershire.

Key Takeaways

  • A mortgage affordability calculator gives you an early estimate, not a mortgage offer or guarantee.
  • Income is only part of the picture. Regular commitments, your deposit and household circumstances can all affect affordability.
  • Compare estimated borrowing with the monthly spending limit that feels manageable, leaving room for household costs and a financial buffer.
  • Set a personal ceiling for your Charnwood property search and allow for other purchase and moving costs.
  • Use Taylors’ mortgage calculator as a first step, then treat the result as a guide rather than a lender’s decision.

What does a mortgage affordability calculator actually estimate?

A mortgage affordability calculator gives an indicative estimate of how much you might be able to borrow, based on the details you enter. It can help you plan a property search, but the result is only as useful as the information behind it. It is not a lender’s decision or a promise of the amount you’ll receive.

In brief: a calculator offers an early guide based on your information. A lender makes its own assessment of your circumstances and the property.

The estimate is about potential borrowing, not necessarily a comfortable household budget. A lender may assess whether repayments meet its criteria, but you also need to decide what feels sustainable alongside your everyday spending, plans and need for a financial cushion. Two buyers with similar estimated borrowing limits might choose different property budgets because their priorities and monthly commitments differ.

The term “affordability” can also refer to broader housing measures. A Housing Affordability Index looks at housing costs in relation to income at a wider level, rather than estimating an individual buyer’s mortgage eligibility. A general measure can offer context, but it can’t predict what a particular lender will decide about your application.

What is the difference between affordability and a mortgage agreement?

A calculator provides an early indication. An agreement in principle is a separate step: a lender considers information about you against its requirements and indicates how much it may be prepared to lend. It is not a formal mortgage offer or a guarantee that an application will be accepted. Lenders can assess the same circumstances differently, so one calculator result is not a verdict from the whole market.

Even after an agreement in principle, the lender’s decision may depend on a fuller application and further checks. The property itself can also matter. Keep each stage in perspective: an online estimate helps with initial planning, while the lender decides whether to lend and on what terms.

When should a buyer use an affordability calculator?

Use one early, before choosing a firm property-search range. The estimate can help you prepare questions about how regular commitments are considered or what might change the amount available. It can also help you compare potential borrowing with the monthly cost you would feel comfortable managing.

Revisit the estimate if your circumstances or the information you enter changes. A different income, deposit, household commitment or borrowing balance may affect the result, depending on the calculator and lender. Use accurate figures and treat the output as a planning snapshot, not a fixed ceiling. It is a practical starting point for setting your home-buying budget.

How income, deposit and spending shape a mortgage affordability estimate

A mortgage affordability estimate depends on more than your headline salary or deposit. Income helps indicate what may be affordable, while regular commitments and household costs affect how much room remains in your budget. Your deposit changes how much you need to borrow, but it is only one part of the calculation.

Affordability depends on more than salary or deposit alone: it reflects income, financial commitments, available savings and the needs of your household.

Which financial details can change the estimate?

Income is one factor, but how it is recorded matters. Gross income is your pay before tax and other deductions; take-home pay is what reaches your bank account. A calculator or lender may use income information in a particular way, so follow the tool’s instructions. For your own monthly budget, start with take-home pay, as that is what you have available to spend.

Existing credit commitments, such as loan or credit card repayments, can reduce the amount left for mortgage costs. For your personal budget, include regular household bills, travel, childcare and other recurring expenses rather than relying on a best-case month. Household circumstances can affect both day-to-day costs and how a lender views an application.

Lenders do not all assess applications in the same way. They may weigh income, commitments and household details differently, so there is no universal formula that turns a salary into a guaranteed borrowing figure. The National Association of Realtors Housing Affordability Index offers a broader example of affordability being considered against income and housing costs. It relates to the US market, so it should not be used as a direct guide to a UK lender’s decision.

Why does the deposit matter to your budget?

For a given purchase price, a larger deposit means you need to borrow less. That changes the amount of mortgage you need, but does not guarantee that a lender will approve an application or offer particular terms. Your overall circumstances and the lender’s criteria still matter.

Keep deposit savings separate from the rest of your purchase budget. You may also need funds for buying and moving, so do not treat every pound you have saved as available for the deposit. The right balance is personal: a larger deposit may reduce the amount borrowed, while keeping savings back can leave more room for expenses and unexpected needs.

Make your estimate more useful by entering accurate, up-to-date figures and checking them before you start. Include commitments you might otherwise overlook, and revisit the calculation if your income, borrowing or household costs change. If you are using the result to shape a search in Charnwood, Taylors can offer local property guidance. Discuss your Charnwood property search with Taylors.

Mortgage calculator estimate versus a comfortable buying budget

A mortgage affordability calculator may show potential borrowing, but that is not automatically the right amount to spend on a home. Set a more grounded budget by separating what you might borrow from what you are comfortable paying each month and the total funds you will need to buy and move.

Budget figureWhat it meansHow to use it
Estimated borrowingAn indicative amount you may be able to borrow, subject to a lender’s assessment.Treat it as a starting point, not a target price.
Planned spending limitThe property budget you decide feels manageable for your circumstances.Check expected repayments against your household spending and savings plans.
Total purchase budgetThe funds needed for the home, deposit and costs associated with buying and moving.Keep costs outside the mortgage in your overall plan.

Why might the calculator’s maximum feel too high?

A lender’s assessment and your personal comfort measure different things. Even if an estimated repayment looks affordable on paper, account for regular bills, existing commitments, savings goals and household costs that can vary. There is no single buffer that suits every buyer. Test a lower spending limit against your actual monthly outgoings and consider whether it leaves room for unexpected expenses.

Look beyond the mortgage payment. A home brings ongoing costs, and your usual spending may change after moving, for example if your travel arrangements or household bills are different. Leave room to manage those costs without relying on every month going exactly to plan. A lower personal ceiling can keep your search aligned with the life you want to maintain, not just the maximum a calculator suggests.

What costs sit outside the mortgage estimate?

The borrowing estimate may not show the full amount you need to buy and settle into a property. Include purchase-related costs, removals and other moving expenses, as well as ongoing homeownership costs such as maintenance and household bills. Which costs apply, and how much they are, will depend on your circumstances and the property.

Keep these funds separate from your deposit and monthly repayment plan. If all your savings go towards the deposit, you may have less flexibility for expenses during the move or after you get the keys. Taylors’ guide to the true cost of moving house in Leicestershire can help you consider the broader picture. Use it alongside your own budget rather than assuming every cost applies to every purchase.

Before settling on a search ceiling, compare estimated borrowing with your chosen spending limit and total purchase budget. This can help you focus on homes that fit your finances, while keeping money aside for the practical costs of moving.

Mortgage affordability calculator: how much could you borrow?

A borrowing estimate becomes more useful when you turn it into a clear search plan. Start with the estimate, set a personal ceiling that reflects your household budget, allow for costs beyond the purchase price and refine what you are looking for. This keeps the search practical without letting one calculator result dictate every decision.

  1. Start with an estimate. Use the result from a mortgage affordability calculator as an initial guide, not a target you have to reach.
  2. Choose your own ceiling. Decide what you would be comfortable spending based on your wider circumstances.
  3. Allow for other costs. Keep funds aside for purchase and moving expenses, as well as the costs of running a home.
  4. Refine the search. Match your budget to the property features and locations that matter most to you.

How can buyers set a sensible search ceiling?

Start below the maximum estimate if that better suits your monthly budget or gives you more financial breathing space. Separate essential property needs from features you would like but could compromise on. This makes it easier to compare homes without stretching your budget for something that is not essential. Review your ceiling if your income, deposit or regular commitments change.

Write down the monthly amount you are comfortable committing to, then use it to guide the property budget you explore. A lender’s view of borrowing and your preferred spending limit are different considerations. Keep your own limit in view as you search, particularly when a property tempts you to go beyond it.

How should local searches reflect your budget?

Charnwood offers a range of places to consider, and the homes available will vary over time. Rothley, Quorn, Mountsorrel, Anstey, Sileby, Syston and Barrow upon Soar are useful starting points for a local search, not a set of price comparisons. Focus on homes that match your budget and requirements rather than assuming every property in one village will suit the same buyer.

Describe your search in practical terms: the type of home you need, how many bedrooms would work and any location priorities, such as being close to family or a regular journey. Then compare suitable listings across the areas you are open to. If options are limited, decide whether to widen the location, adjust a preference or wait for a better match. Change one thing at a time so you can see how it affects your choices.

If you are moving from an existing home, factor in the funds available after a sale when setting your budget. The amount depends on the property and the details of the move, so include it in your planning rather than assuming it will match a particular figure.

Discuss your Charnwood property search with Taylors

Using Taylors’ mortgage calculator as a first step towards buying

Taylors’ mortgage calculator can help you begin planning a property search by giving you an estimate to consider alongside your own budget. It is an early planning tool, not a lender’s decision. Use the result to organise your next steps rather than treating it as an amount you need to borrow or spend in full.

With that distinction in mind, you can clarify what matters most in a home, identify the areas you want to explore and keep a realistic spending limit in view. Taylors helps buyers search for residential property across Leicestershire, including Charnwood and nearby villages.

What should you do after getting an estimate?

Review the information and assumptions behind the estimate. If a figure has changed or no longer reflects your circumstances, update your planning. Then consider these next steps:

  • Write down the budget you feel comfortable using for a property search, taking your wider household finances into account.
  • Note questions about eligibility, borrowing or mortgage products to discuss with an appropriately qualified mortgage professional.
  • Use your chosen budget to guide the homes and locations you explore, rather than treating the estimate as a spending target.

A mortgage professional can discuss your circumstances, lender criteria and suitable mortgage products. This is separate from estate agency guidance. Mortgage questions belong with a suitably qualified professional, while you can discuss property-search questions with a local estate agent.

How can local property guidance support your next step?

Once you have a comfortable budget and a clearer idea of your requirements, local guidance can help bring your search into focus. Taylors can help you explore residential properties across Leicestershire, including Charnwood and surrounding villages. Discuss the type of home you are looking for, preferred locations and essential priorities, so your search is based on what suits you rather than an estimate alone.

If your requirements shift as you view properties, take stock of what you have learnt and refine your search. Perhaps a different layout matters more than an extra room, or you are open to another village. Keep any change in spending within the limit you have set for yourself.

The estimate is a place to begin. Pair it with a considered budget and local property knowledge for a more grounded basis for exploring homes in Leicestershire.

Talk to Taylors about your Leicestershire property search

Take your next step with a clear plan

Your next move does not need to be a firm commitment to buy. Use the mortgage affordability calculator as one planning reference, then keep a short list of questions and property priorities as your search develops. You will have something practical to revisit if your circumstances change or you learn more about the homes available.

For mortgage eligibility and product recommendations, speak with an appropriately qualified mortgage professional. For local property-search guidance, Taylors is an independent Rothley estate agency established in 1992, helping buyers explore residential property across Leicestershire. Keeping those roles clear can make the next stage more straightforward.

Talk to Taylors about your Leicestershire property search

Take the process at a pace that suits you. With a considered plan and local guidance, you can move towards a home that fits your priorities and budget.

Frequently Asked Questions

How accurate is a mortgage affordability calculator?

Its usefulness depends on the figures entered and the assumptions built into the tool. Two calculators may produce different results because they ask for different information or process it differently. Check the instructions, use current figures from your records and note when you last updated them. If a result changes unexpectedly, review the inputs before drawing conclusions.

Can a mortgage affordability calculator guarantee I will be approved?

No. Only a lender can decide whether to approve a mortgage application. During the application process, the lender may review supporting documents and assess the property as well as your financial circumstances. If you are preparing to apply, organise relevant information and discuss eligibility with an appropriately qualified mortgage professional. This can help you understand what the online result leaves unanswered.

How much deposit do I need to use a mortgage affordability calculator?

There is no one deposit amount that applies to every calculator. Check what the tool asks for and, if it requires a figure, enter the amount you realistically expect to have available for the purchase. Do not include savings you intend to keep for other needs. If you are still building your deposit, revisit the calculation as your savings change.

Does a mortgage affordability calculator include bills and moving costs?

That depends on the calculator, so check which costs it asks you to enter and what its result represents. For your own planning, make a separate checklist of costs that may apply to your move, then add ongoing household expenses to your monthly budget. Replace rough assumptions with actual figures when you have them. This helps prevent an online estimate being mistaken for a complete purchase budget.

Can I use a mortgage affordability calculator if I am self-employed?

Yes, but a basic online result may not capture the detail of self-employed income, particularly if earnings vary. Before speaking with a mortgage professional, organise a clear record of how your income has changed over time and note any unusual fluctuations. They can explain how a lender may assess your circumstances and what supporting information could be relevant to an application.

Should I use a mortgage affordability calculator before viewing homes?

Yes. It can give you a starting point for deciding which properties to shortlist. Before booking a viewing, note the features each home offers and any questions you want to ask. Afterwards, compare what you saw with your priorities and refine your shortlist. This keeps the search focused on homes that suit your needs, not just their advertised features.
Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

How Much Can I Borrow for a UK Mortgage? 2026 Guide

How Much Can I Borrow for a UK Mortgage? 2026 Guide

Imagine finding your perfect detached home in Rothley, only to discover that the bank’s “yes” is £50,000 short of the asking price. It’s a disheartening scenario that many buyers across Leicestershire face, particularly as lender criteria have tightened following the interest rate shifts of early 2026. You might feel overwhelmed by conflicting advice, wondering exactly how much can I borrow mortgage UK banks will actually commit to in today’s market.

We understand that behind every spreadsheet and salary multiple is a real family looking for stability. Whether you’re eyeing a character cottage in Quorn or a modern semi in Birstall, having a realistic figure is the only way to search with confidence. This guide will show you exactly how lenders calculate your borrowing power, moving beyond simple multiples to look at true affordability.

We’ll explore how the current 3.75% base rate influences your monthly repayments and explain the practical steps you can take to improve your “mortgageability.” By the end, you’ll have a clear picture of your budget, helping you move from browsing Rightmove to booking viewings in Charnwood with absolute peace of mind.

Key Takeaways

  • Learn why the 4.5x income multiple is only a baseline and how lenders assess your true affordability against 2026 interest rates.
  • Discover exactly how much can I borrow mortgage UK lenders will offer by understanding how they treat bonuses, commissions, and self-employed earnings.
  • Identify the “Big Three” financial pillars—deposit, credit health, and outgoings—that dictate your maximum loan-to-value ratio.
  • Get practical advice on improving your mortgageability through simple steps like electoral roll registration and managing monthly commitments.
  • Find out how your borrowing power aligns with current property values in Charnwood villages to help you target the right homes in your search.

Mortgage Affordability: Understanding the Basics of UK Borrowing

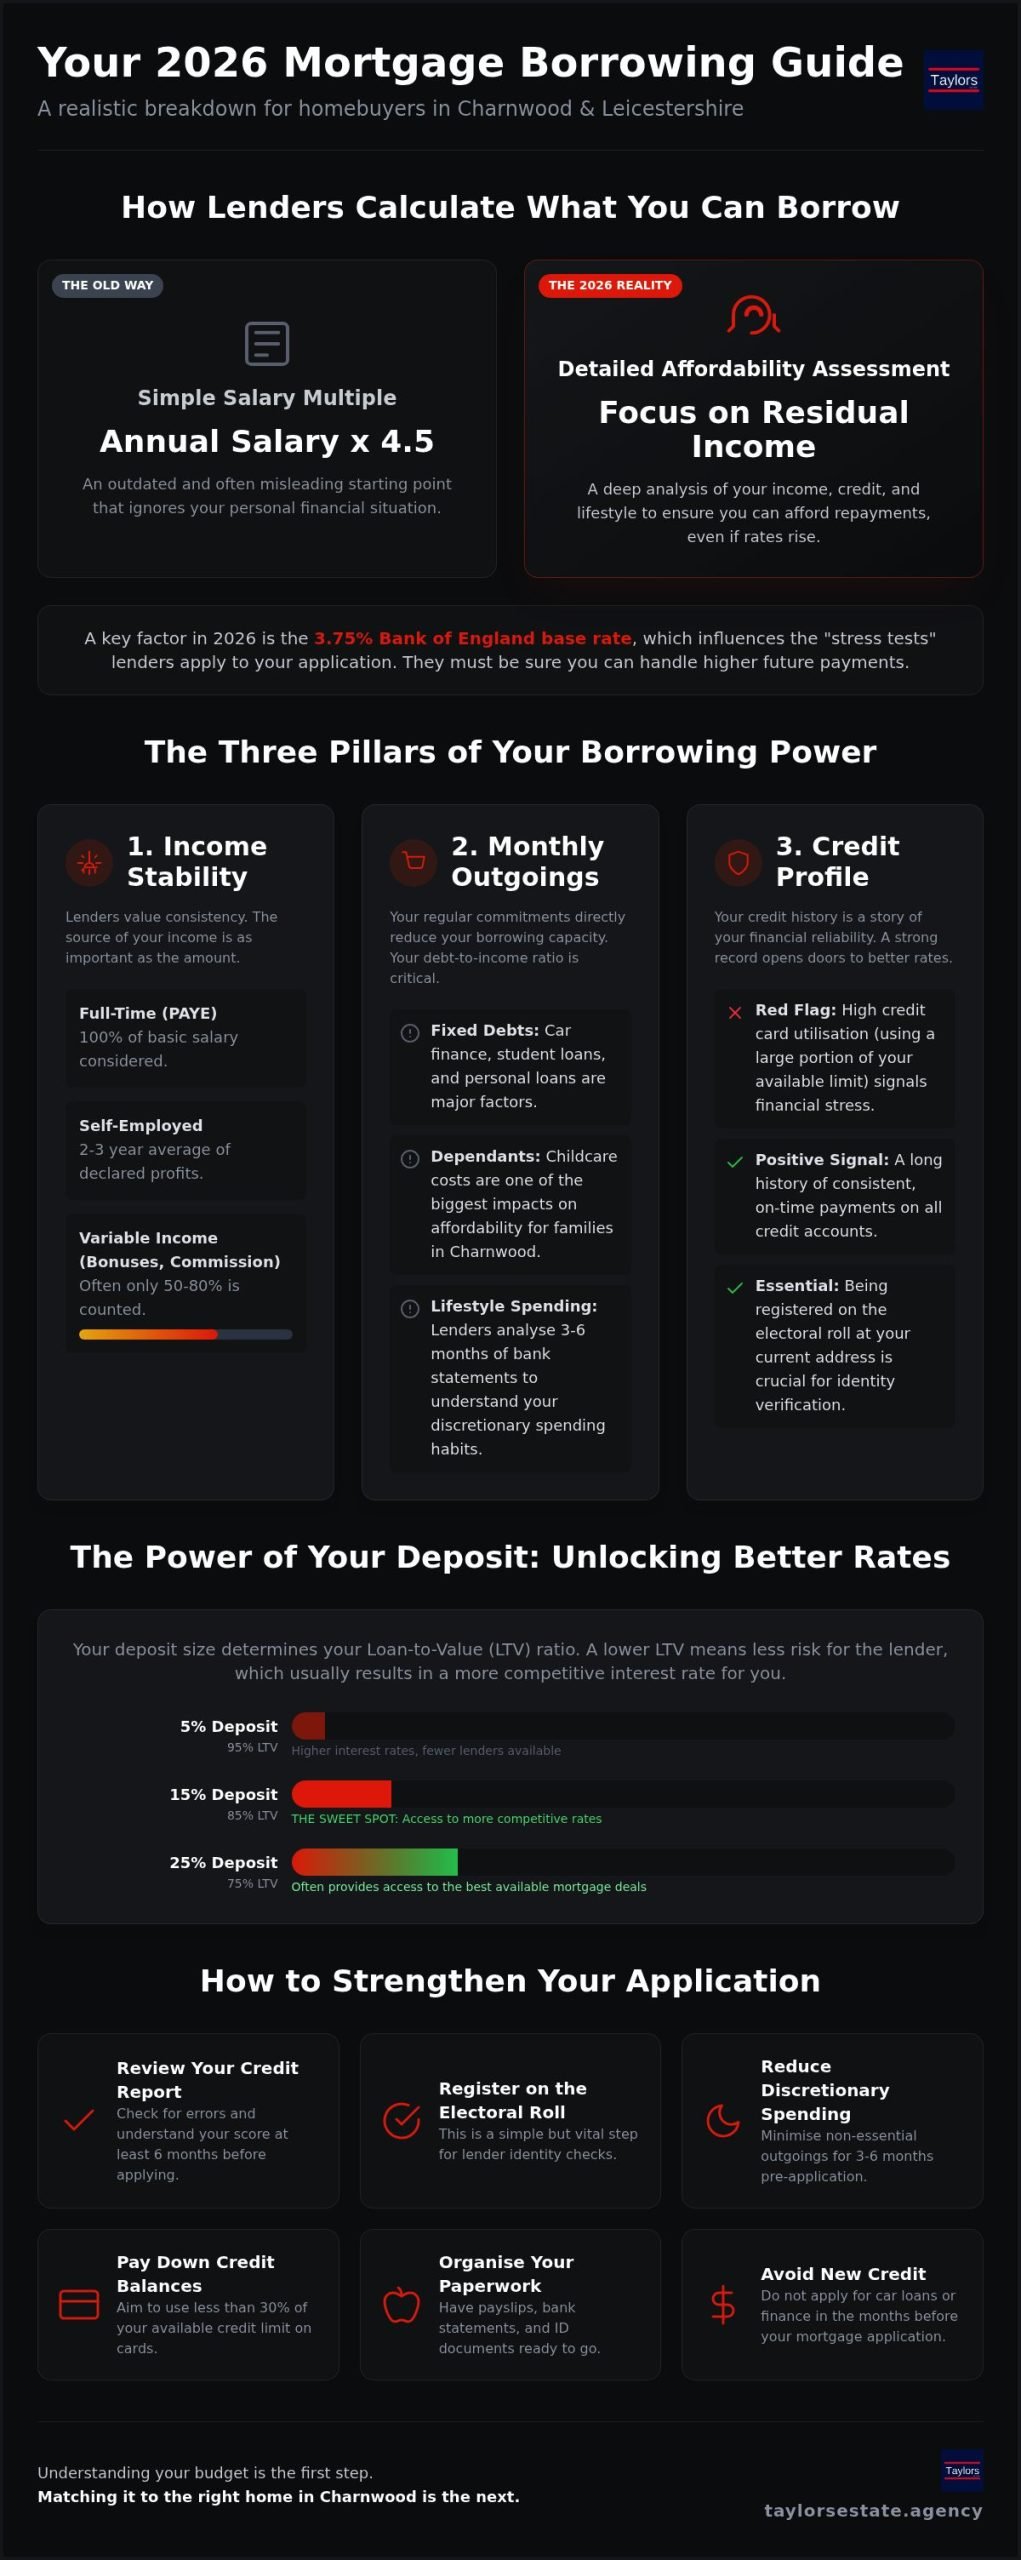
Mortgage borrowing is essentially the total capital a lender is willing to advance you, based on their detailed assessment of the risk involved. While it’s tempting to focus solely on the final figure, the process is rooted in Mortgage Affordability: Understanding the Basics, where banks balance your aspirations against financial reality. Most high street lenders use a standard “income multiple” as their starting point, which typically sits at 4.5 times your annual gross salary. This gives you a baseline for answering the question: how much can I borrow mortgage UK wide?

There’s a vital distinction between “borrowing power” and “affordability.” Borrowing power is the maximum amount a bank might theoretically offer you, whereas affordability is what you can comfortably pay back without sacrificing your lifestyle in villages like Mountsorrel or Quorn. An Agreement in Principle is the formal start of your buying journey, providing a document from a lender that states how much they’re prepared to lend you in theory.

The Role of Income Multiples in 2026

In 2026, these multiples aren’t set in stone. For joint applications, lenders usually combine your incomes before applying the multiple, which can significantly boost your budget for larger homes in Rothley. High earners, typically those with a salary over £75,000, or professionals like doctors and lawyers, might access enhanced multiples of 5 or even 5.5 times their income. With the Bank of England base rate currently at 3.75%, lenders are being more precise. They’re balancing these higher multiples against the reality of monthly repayments to ensure borrowers aren’t overextending themselves.

Gross Income vs Net Affordability

Lenders have moved far beyond just looking at your headline salary. They now scrutinise your disposable income, which is what remains after your essential outgoings, such as childcare, transport, and existing debts. This is where the stress test comes into play. Banks calculate whether you could still afford your mortgage if interest rates were to rise significantly above the current averages. They use 2026 cost-of-living data to ensure that your dream move to Charnwood remains sustainable even if your daily expenses increase. Understanding this shift from gross to net is crucial when calculating how much can I borrow mortgage UK lenders will actually approve.

Key Factors That Influence Your Maximum Mortgage Limit

While your salary provides the foundation, lenders look at three main pillars to determine your final limit: your deposit size, your credit history, and your monthly outgoings. These factors often carry more weight than the headline income multiple when calculating how much can I borrow mortgage UK lenders will offer. Your Loan-to-Value (LTV) ratio is particularly significant; it represents the percentage of the property value you are borrowing. Lower LTVs usually result in more competitive interest rates because the lender’s risk is reduced.

Age and the length of the mortgage term also play a role. A longer term can lower monthly payments but increases the total interest paid; meanwhile, lenders may cap terms that extend past your planned retirement age. To ensure a smooth application, maintaining a clean credit report for at least six months prior is vital. This means avoiding new credit applications or missed payments. You can follow the Official government guide to buying a home to help prepare your documentation and understand the legal steps involved.

The Power of the Deposit

For many buyers in Charnwood, a 10% or 15% deposit represents the “sweet spot” where interest rates become significantly more attractive. Larger deposits act as a safety net for the bank, which often leads to a higher borrowing ceiling. If you are already a homeowner in Leicestershire, the equity in your current property often serves as your primary deposit. Getting an accurate valuation is the first step to understanding how much equity you can bring to your next move, especially if you are moving between villages like Woodhouse Eaves or Sileby.

Debt-to-Income Ratios and Monthly Commitments

Lenders are increasingly sensitive to your debt-to-income ratio. Monthly commitments like car finance, student loans, and credit card balances effectively reduce the amount of income available for mortgage repayments. In 2026, childcare costs are a major factor in affordability checks, sometimes carrying as much weight as a significant loan. This is why banks scrutinise your bank statements so closely.

Organising your finances at least three months before you apply is essential. This includes clearing small balances and ensuring your bank statements reflect a stable financial pattern. If you’re unsure how your current commitments might affect your property search in Rothley or Birstall, get in touch with our team for some informal local guidance on preparing your finances for a move.

Beyond Salary: How Lenders Calculate Your True Borrowing Power

Lenders look far beyond your basic pay slip to understand your financial capacity. For many professionals across Leicestershire, a significant portion of their earnings comes from variable income such as bonuses, commission, or overtime. While these sums are vital to your household budget, banks rarely treat them with the same weight as a guaranteed salary. Most lenders will take a two-year average of these payments or apply a “haircut,” often only counting 50% of the total towards your borrowing limit. Understanding these nuances is a key part of answering how much can I borrow mortgage UK lenders will actually support.

Other income sources like pensions, dividends, or court-ordered maintenance payments can also be included, provided they are stable and documented. It’s also worth remembering that every lender has a different appetite for risk. A rejection from one high-street bank doesn’t mean your plans are over; it simply means your specific income structure didn’t fit their particular model. As local agents, we often see buyers succeed with a secondary lender after a “No” from their primary bank.

Self-Employed and Contractor Criteria

For the many business owners and freelancers in Rothley and Mountsorrel, the standard requirement is usually two years of certified accounts or SA302s. Lenders typically average your net profit over the last two years to find a stable figure. If your profits have recently increased, they might still use the lower figure to remain cautious. However, contractors in specific fields like IT or medicine are often treated differently. Some specialist lenders will calculate borrowing based on your daily rate rather than your annual accounts, which can significantly boost your budget for a home in Charnwood.

Joint Applications and Booster Options

Combining incomes is the most effective way to reach the price brackets found in villages like Quorn or Woodhouse Eaves. If a joint application still doesn’t provide enough leverage, a “Joint Borrower Sole Proprietor” (JBSP) mortgage might be an option. This allows a parent or family member to add their income to the mortgage to help with affordability without being named on the property deeds. Modern lenders are also very comfortable with gifted deposits from family, provided the funds are a genuine gift and not a loan. These “booster” options can be the difference between a compromise and finding your ideal home.

How to Increase Your Borrowing Potential Before You Buy

Your borrowing limit isn’t a static number. It’s a reflection of your financial health at a specific moment in time. By taking proactive steps in the months leading up to your application, you can often influence the final figure a lender offers. Understanding how much can I borrow mortgage UK wide involves looking at your profile through a bank’s eyes. They want to see stability, predictability, and a clear ability to manage debt.

Being on the electoral roll at your current Leicestershire address is one of the simplest yet most effective ways to boost your internal credit score. Whether you’re renting in Birstall or living with family in Anstey, this registration provides proof of address that lenders use for identity checks. We also advise against making major career changes or large purchases, such as a new car on finance, in the six months before you apply. These shifts can signal instability or reduce your disposable income, which directly impacts your affordability.

  • Register on the electoral roll at your current home address.
  • Avoid new credit applications for at least six months before applying.
  • Keep your credit card balances below 30% of their available limits.
  • Maintain a stable employment history during the application window.
  • Use a professional mortgage broker to access niche lenders who specialise in your specific income type.

Credit Score Optimisation

Fixing errors on your credit report is a vital task while you’re planning your move to villages like Cropston or Thurcaston. Even a small mistake in a past address or a wrongly recorded late payment can cause delays. Interestingly, having too much unused credit can sometimes be as detrimental as having too little. Lenders worry that you could suddenly run up large debts after the mortgage is granted. When checking your score, always use “soft” searches where possible, as “hard” searches leave a footprint that can temporarily lower your rating if too many occur in a short period.

Reducing Outgoings to Boost Affordability

Lenders perform a deep dive into your bank statements to identify discretionary spending. They may flag frequent high-value luxury purchases or recurring subscription services that you no longer use. Closing dormant store cards and cancelling unnecessary memberships can help clean up your financial profile. A small reduction in monthly debt can lead to a surprisingly large increase in the capital lent. For example, clearing a £50 monthly credit card payment could potentially increase your total mortgage offer by several thousand pounds, bringing that dream home in Rothley within reach.

Get in touch for a local perspective on your moving plans

How Much Can I Borrow for a UK Mortgage? 2026 Guide

Applying Borrowing Limits to the Leicestershire Property Market

Understanding how much can I borrow mortgage UK wide is only half the battle; the other half is knowing how that figure translates into a real-world home in Charnwood. Local market resilience is evident, with house prices in the area rising by 3.8% in the year to June 2026. This growth outpaced the wider East Midlands average, meaning your borrowing power needs to be matched carefully with current village values. In high-demand areas like Rothley or Quorn, where average sold prices sit between £393,000 and £425,000, being mortgage-ready is essential to securing a property against competing bids.

One challenge many buyers face is the “lending gap.” This occurs if a lender’s surveyor values a property lower than your agreed purchase price. Because banks only lend based on their own valuation, you may need to bridge this gap with extra cash. At Taylors Estate Agency, we provide integrated financial tools, including our in-house mortgage calculator, to help you model these scenarios before they happen. We aim to ensure that your financial planning is rooted in the reality of the Leicestershire market, rather than just a theoretical salary multiple.

What Your Borrowing Power Buys in Charnwood

Location significantly dictates what your budget can achieve. For example, a borrowing limit of £250,000 might secure a modern three-bedroom semi-detached home in Syston or Birstall. However, in a premium village like Woodhouse Eaves, that same figure might only be the starting point for a smaller cottage or a high-end apartment. It is also vital to look beyond the purchase price. You must budget for “hidden” costs such as removals and the 2026 Stamp Duty thresholds to ensure your move remains affordable. For a detailed breakdown of these expenses, see The True Cost of Moving House in Leicestershire: A 2026 Resource Guide.

Expert Valuations as a Financial Tool

If you are a homeowner in Rothley or Mountsorrel looking to move up the ladder, an accurate valuation of your current property is the cornerstone of your search. Knowing your equity is the “second half” of the equation when asking how much can I borrow mortgage UK lenders will permit. Taylors Estate Agency helps coordinate the entire chain by understanding both sides of the affordability equation; this reduces the risk of a sale falling through due to financial surprises. If you are starting your journey, our guide on How Much Is My House Worth in Syston? A 2026 Guide to Property Values offers a great starting point for local homeowners.

Your borrowing capacity is far more than a simple calculation on a bank’s website. As we have explored, the final answer to how much can I borrow mortgage UK lenders will support depends on your deposit, your outgoings, and the specific property you have your eye on. In a resilient market like Charnwood, having these figures confirmed is what allows you to move from browsing to making a successful offer.

Since 1992, Taylors Estate Agency has acted as a trusted local guide for thousands of families across Leicestershire. We believe that clarity is the best cure for anxiety, and our team is here to provide the personalised support you need to understand both your mortgageability and your current home’s value. If you’re thinking about moving in Charnwood and would like honest, local advice, please reach out.

our team would be happy to help

Finding your ideal home in a village like Rothley or Quorn should be an exciting milestone. With the right financial foundation and expert local knowledge, you can approach your next move with absolute confidence.

Frequently Asked Questions

How many times my salary can I borrow for a mortgage in 2026?

Most lenders use a baseline of 4.5 times your annual salary, though this can increase for specific applicants. High earners with a combined income exceeding £150,000 may access multiples as high as 6.5 times through certain banks. When asking how much can I borrow mortgage UK lenders will ultimately decide based on your debt-to-income ratio. This ensures that your monthly repayments remain sustainable even if your circumstances change after moving to villages like Quorn or Sileby.

Does my student loan affect how much I can borrow for a mortgage?

Yes, your student loan repayments are considered a monthly outgoing that reduces your overall disposable income. Lenders don’t look at the total debt balance, but they do factor the monthly deduction into their affordability calculators. This means a higher student loan payment could slightly lower the maximum capital a bank is willing to advance. It’s a common factor for many young professionals looking at properties in Birstall or Syston.

Can I get a mortgage with a 5% deposit in Leicestershire?

Yes, 5% deposit mortgages are available in Leicestershire, provided you meet the lender’s credit and affordability criteria. These 95% Loan-to-Value (LTV) products are popular with first-time buyers in areas like Mountsorrel or Anstey. However, you’ll usually find that interest rates are higher for smaller deposits. Saving a 10% or 15% deposit often provides access to more competitive deals, which can significantly lower your monthly mortgage costs over the long term.

How do high interest rates in 2026 impact my borrowing power?

High interest rates directly reduce your borrowing power because they increase the cost of monthly repayments. With the Bank of England base rate at 3.75% in 2026, lenders apply “stress tests” to see if you could afford payments if rates rose even further. This cautious approach means you might be offered a lower total amount than you would have been in a lower-rate environment. It makes accurate budgeting for your Charnwood home search even more critical.

Will being self-employed reduce the amount I can borrow?

Being self-employed doesn’t automatically reduce your borrowing limit, but lenders calculate your income differently. Most banks will average your net profits from the last two years of certified accounts to determine a stable figure. If your profits are fluctuating, they’ll often use the lower year as a precaution. Providing clear SA302 documents is essential for business owners in Rothley to demonstrate they have the consistent income needed to support a mortgage application.

What outgoings do lenders look at during affordability checks?

Lenders scrutinise a wide range of essential and discretionary outgoings during their deep dive into your bank statements. They specifically look at:

  • Childcare and school fees
  • Existing loans and car finance
  • Credit card and store card balances
  • Regular pension contributions
  • Essential living costs like utilities and groceries

Reducing these commitments three months before applying can help maximise the figure you see when calculating how much can I borrow mortgage UK lenders will agree to.

Does a higher credit score always mean I can borrow more money?

Not necessarily, as a high credit score primarily affects your eligibility for a mortgage and the interest rates you’re offered. While a perfect score makes you a more attractive borrower, the actual amount you can borrow is dictated by your income and outgoings. You could have an excellent credit rating but still be limited by a high debt-to-income ratio. Both factors must work in harmony to secure the best possible mortgage for your move.

How long does a mortgage offer stay valid once I find a house in Rothley?

Most mortgage offers are valid for between three and six months from the date they are issued. This gives you time to complete the legal process once you’ve found your ideal home in Rothley or Barrow upon Soar. If the purchase takes longer than expected, you may need to apply for an extension or provide updated bank statements. It’s always best to keep your lender informed of any delays in the conveyancing process to avoid your offer expiring.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

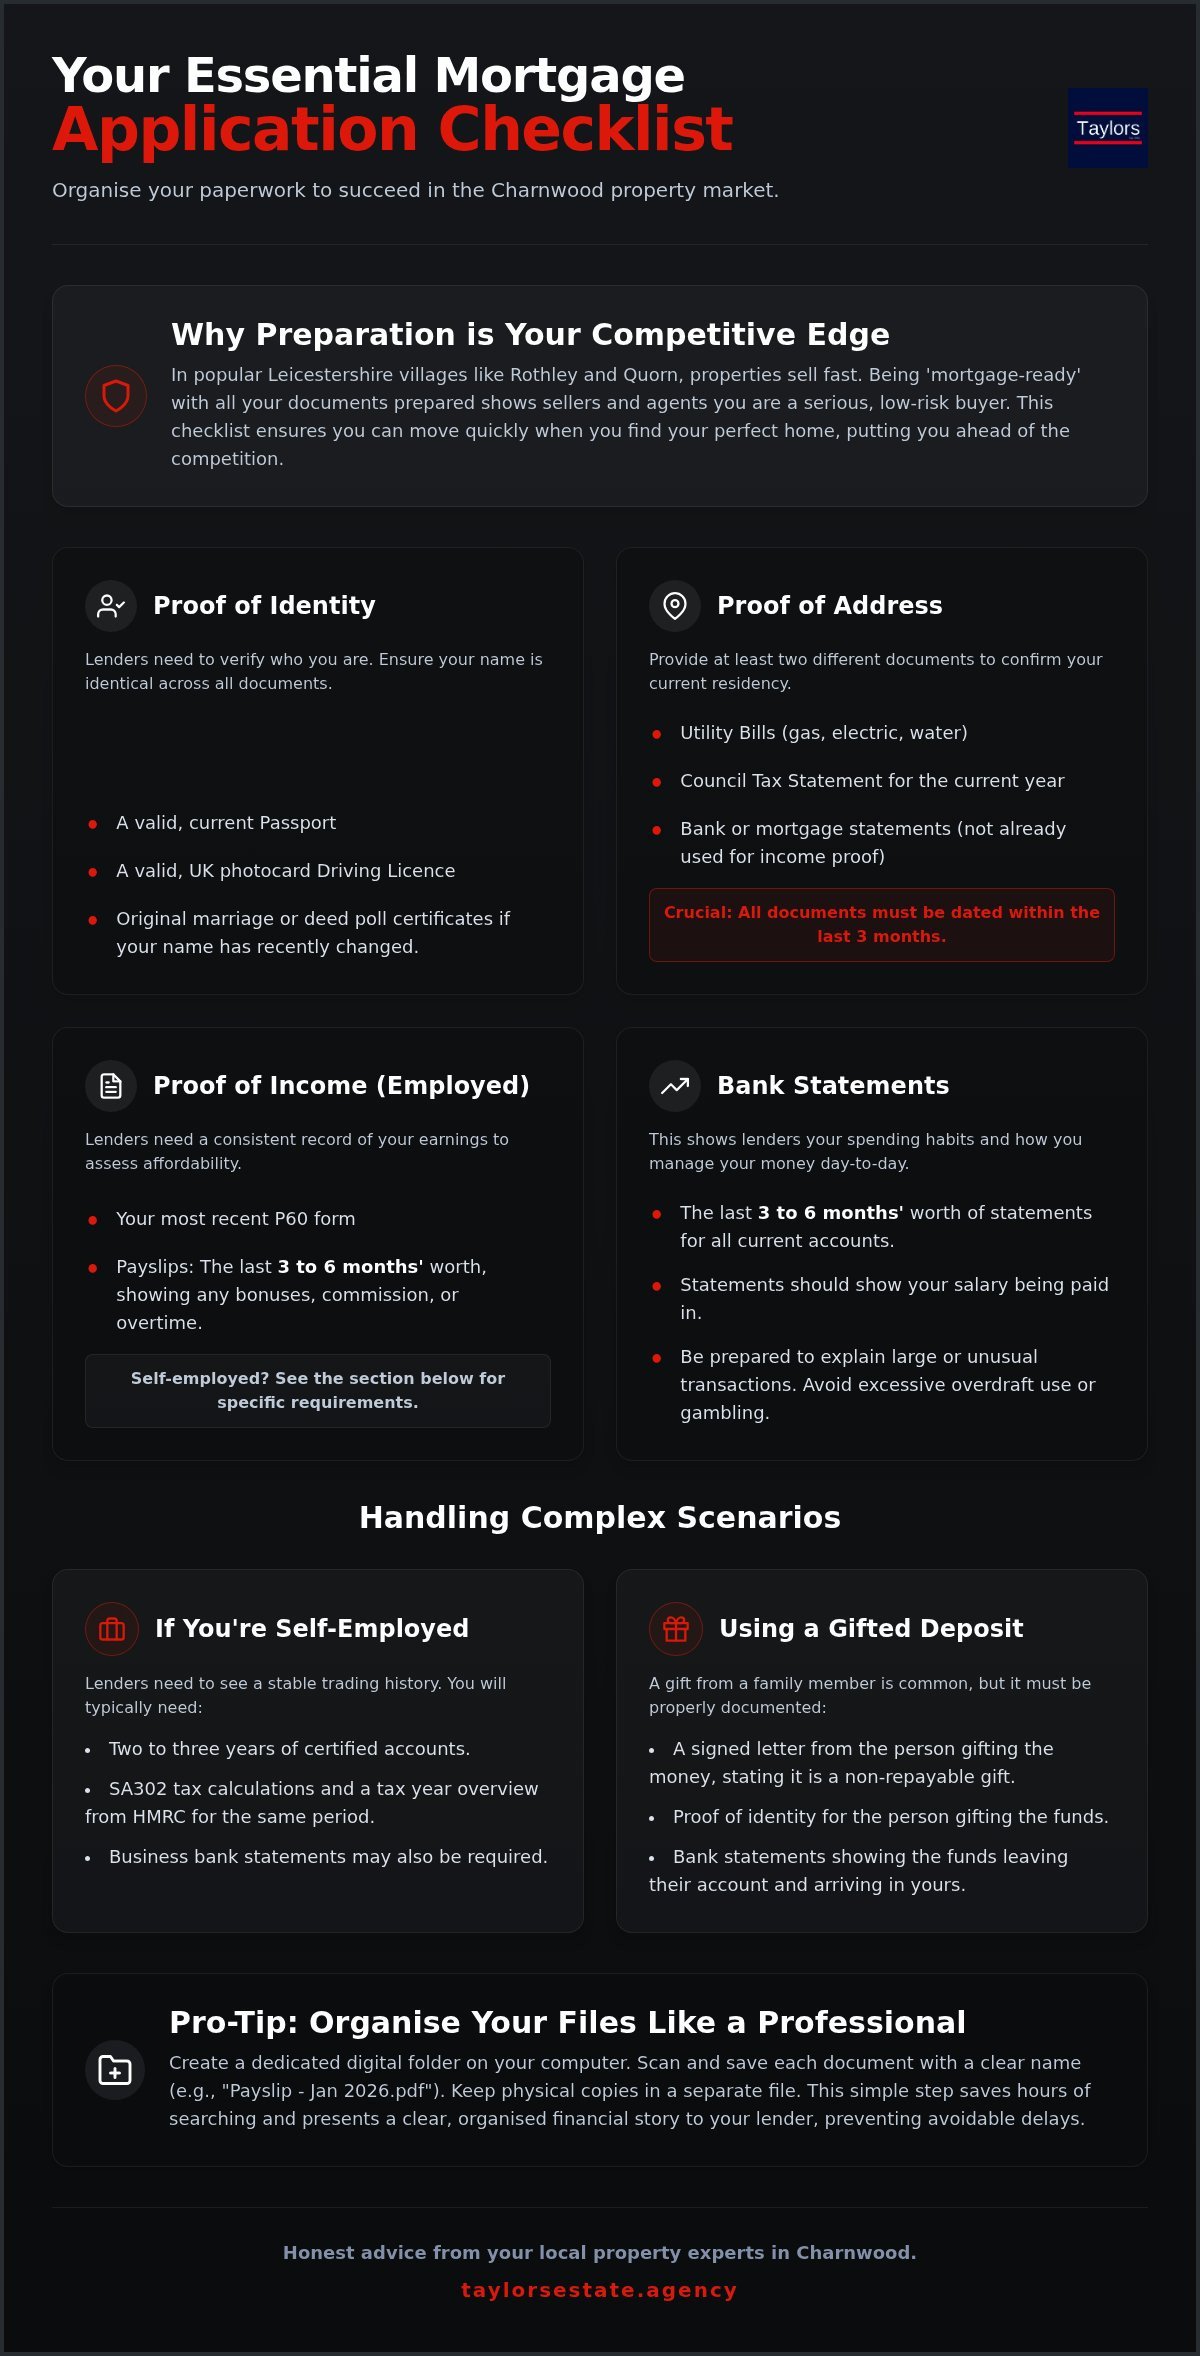
Mortgage Application Checklist UK: A Professional Guide for Leicestershire Buyers (2026)

Imagine finding your perfect home in Rothley or a Victorian terrace in Quorn, only to watch it slip away because a single document was missing from your file. It’s a frustrating situation that many buyers face when they aren’t prepared for the lender’s scrutiny. In the Charnwood property market, being mortgage-ready is just as important as having your deposit saved, as delays in paperwork can lead to losing out to a more prepared bidder.

We know that gathering years of financial history feels daunting, especially if you’re self-employed or managing a gifted deposit. This guide provides a definitive mortgage application checklist UK to help you organise your paperwork well before you start viewing properties. We’ll walk you through exactly what lenders require in 2026, from proof of identity to the intricate details of your monthly expenditure. You’ll gain a clear understanding of the application timeline and the peace of mind that comes from having your story of money perfectly documented and ready for review.

Key Takeaways

  • Understand why preparing your paperwork early is essential for staying ahead in competitive Leicestershire villages like Rothley and Quorn.
  • Follow a detailed mortgage application checklist UK to ensure your identity, address, and income documents are exactly what lenders expect in 2026.
  • Learn how to manage complex financial situations, such as self-employment or gifted deposits, without causing delays to your purchase.
  • Discover how to organise your digital and physical files to present a clear, professional story of your finances to your lender.
  • See how an expert property valuation provides the foundation for your budget before you begin viewing homes across the Charnwood area.

Why Being Mortgage Ready Matters in the Leicestershire Property Market

Properties in villages like Rothley and Quorn don’t wait for anyone. When a charming cottage or a modern family home hits the market, the interest is often immediate and intense. Being “mortgage ready” isn’t just a suggestion; it’s a strategic necessity for anyone serious about moving. If you haven’t started your mortgage application checklist UK, you risk being pushed to the back of the queue by buyers who have their finances perfectly aligned and ready for scrutiny.

A Mortgage in Principle (MIP) serves as your badge of credibility. It tells a seller that a lender has already looked at your basic figures and is prepared to lend you a specific amount. In a competitive environment, this document is often the difference between an agent booking you a viewing or advising the vendor to wait for a more “qualified” applicant. Beyond the logistics, being prepared reduces the immense emotional weight of the search. You can view homes with confidence, knowing exactly what you can afford amongst the various listings across Leicestershire. This clarity allows you to make decisions based on facts rather than hope.

The Competitive Edge in Charnwood

Vendors in Sileby or Anstey are looking for the path of least resistance. They want a sale that is likely to complete without a hitch. By having your paperwork in order, you present yourself as a low-risk buyer. The UK mortgage industry is complex, and lenders are increasingly thorough with their checks. Local agents, including our team at Taylors, prioritise offers from buyers who can prove their funding immediately. This proactive approach prevents the heartbreak of losing your dream home because you were still hunting for old payslips whilst someone else was signing their contract.

Using Financial Tools to Set Your Budget

Before you fall in love with a property in Mountsorrel, you need a realistic view of your purchasing power. A good starting point is to use a mortgage calculator to get a rough estimate of your borrowing capacity. However, you should remember that these tools provide a general guide. A lender will dive much deeper into your mortgage application checklist UK to verify your actual disposable income. You must also account for the cost of moving house leicestershire, including stamp duty and legal fees, to ensure your budget is robust and sustainable for the long term.

The Essential Documentation Checklist: Proving Your Identity and Income

Lenders in 2026 are more meticulous than ever. To meet the standards of a mortgage application checklist UK, you must provide documents that leave no room for doubt. Your primary identity document, typically a valid UK photocard driving licence or international passport, must be current and valid. If you’ve recently moved to a new home in Birstall or Sileby, ensure your licence reflects your new address before applying. For proof of residency, lenders usually require two separate documents, such as utility bills or council tax statements, dated within the last three months.

Income verification is the next hurdle. Lenders generally ask for your last three to six months of payslips to establish a consistent earning pattern. If your income includes shift allowances, bonuses, or commission, these should be clearly visible. Bank statements are perhaps the most sensitive part of the process. Lenders look for a clean money trail, scrutinising your spending habits amongst other monthly commitments. They’ll look for excessive overdraft use or frequent gambling transactions, which can flag you as a higher risk. Ensure you provide full statements, not just transaction lists, to show you manage your finances responsibly. If you’re unsure if your current statements are “mortgage ready,” you can message our team for a quick chat about local requirements.

Identity Documents: Avoiding Common Errors

Consistency is the foundation of a successful application. Your full name must appear exactly the same way on your passport, utility bills, and payslips. If you’ve recently changed your name through marriage or deed poll, you’ll need the original certificates to bridge any gaps. Using a comprehensive UK mortgage application checklist helps ensure you don’t miss these small but vital details that can stall an application for weeks. Lenders won’t accept documents where the names don’t align perfectly without legal proof of the change.

Income Proof for Employed Professionals

When submitting your documents, quality matters. Lenders require original PDF downloads from your employer’s payroll portal rather than mobile phone screenshots or blurry photos. Screenshots often lack the essential metadata and formatting that banks use to verify authenticity. If your pay varies due to commission or overtime, be prepared to explain these fluctuations to your advisor so they can present your case accurately to the lender. The P60 is the annual summary of your pay and tax that lenders use to verify your basic salary. Having this document ready prevents unnecessary back-and-forth during the underwriting stage.

Handling Complex Scenarios: Self-Employment and Gifted Deposits

Not every buyer in Leicestershire is a PAYE employee with a simple deposit. If you’re a business owner in Mountsorrel or receiving help from family to buy in Rothley, your mortgage application checklist UK will require extra layers of verification. Lenders aren’t trying to be difficult; they’re simply performing due diligence to ensure the loan is sustainable and the funds are legitimate. Preparing these specific documents early prevents the stress of a last-minute scramble when you’ve found a property you love.

The Self-Employed Paper Trail

For the self-employed, the traditional payslip is replaced by the SA302 form and a Tax Year Overview. Lenders typically look for at least two years of certified accounts to assess your average earnings. They’re searching for consistency in your net profit over this period. If your income fluctuates significantly, be prepared to explain why, perhaps due to a large one-off investment in your business or a temporary market shift. Consistency is key, and lenders often take an average of the last two years’ profits to determine your borrowing power.

Having a qualified accountant sign off on your financial statements adds a layer of authority that lenders appreciate. You can download your SA302 forms directly from the HMRC website, which provides the “Tax Calculation” summary lenders use to verify your declared income. Ensuring these figures match your bank statements is a vital step in proving your financial stability. Without these matching records, underwriters may struggle to approve your application, regardless of how successful your business appears on the surface.

Handling Gifted Deposits Correctly

Gifted deposits are common amongst first-time buyers in villages like Anstey or Cropston. However, a simple bank transfer isn’t enough to satisfy modern lending requirements. Your family members must provide a signed letter stating the amount, their relationship to you, and a clear “no-repayment” clause. This confirms the money is a genuine gift, not a hidden loan that would affect your monthly affordability calculations. It’s a small but vital detail that can halt an application if missed.

To comply with UK Anti-Money Laundering (AML) regulations, the donor also needs to provide proof of identity and their own bank statements. This documents the “source of funds,” showing exactly how the money was accumulated. It’s wise to ensure your solicitor and chosen estate agents leicestershire are aware of the gift early in the sales process. Early transparency prevents delays when you’re nearing the exchange of contracts on your new home, keeping the momentum of your move on track.

Avoiding Delays: How to Organise Your Financial Paperwork Like a Pro

Efficiency is the hallmark of a successful move. Once you’ve gathered the items for your mortgage application checklist UK, the way you store and present them can significantly impact your speed to offer. We recommend creating a dedicated digital folder with a logical structure. Use clear, descriptive filenames, such as “John_Doe_Payslip_Jan_2026.pdf”, rather than generic strings of numbers. This small step allows your mortgage advisor or solicitor to identify documents instantly, preventing the back-and-forth emails that often stall an application.

Whilst digital is the standard for submissions, keeping a physical “home-buying file” is equally beneficial. Having hard copies ready for face-to-face meetings with local advisors in Rothley ensures you can answer questions on the spot. You must also remember the “Three-Month Rule”. Lenders require the most recent data, so if your search for a home in Charnwood takes longer than expected, you’ll need to refresh your file as old statements expire. It’s also wise to review your credit report via Experian or Equifax before the lender does, allowing you to correct any errors that might affect your score.

Audit Your Own Bank Statements

Lenders look for patterns, not just balances. Before you submit your statements, perform a self-audit to identify potential “red flags”. Frequent payday loans or large, unidentified transfers between accounts can trigger requests for more information. If you have regular outgoings that look unusual, be prepared to explain them as part of your affordability assessment. We advise buyers to stop using their overdraft three months before an application to show better financial behaviour. This proactive shift demonstrates that you are living within your means and are ready for the responsibility of a monthly mortgage payment.

Collaborating with Local Professionals

Your mortgage application checklist UK isn’t just for the bank. A local solicitor in Rothley or Loughborough will require the same proof of identity and source of funds for the conveyancing process. By having these organised early, you can move from “offer accepted” to “contracts exchanged” with much more momentum. Working with a local mortgage broker who understands the Charnwood property market adds another layer of security. At Taylors, we encourage buyers to be transparent about their financial position from the first viewing. This honesty allows us to advocate for you more effectively when speaking to vendors in villages like Mountsorrel or Quorn.

Get expert advice on organising your paperwork

Mortgage Application Checklist UK: A Professional Guide for Leicestershire Buyers (2026)

Beyond the Paperwork: Taking Your Next Steps with Taylors Estate Agency

Completing your mortgage application checklist UK is a significant milestone, but it represents just one half of the moving journey. Once you have your documents organised and your Mortgage in Principle secured, the focus shifts to finding a property that fits your lifestyle. At Taylors, we’ve spent over 30 years guiding buyers and sellers through the nuances of the Leicestershire property market. Established in 1992, our Rothley-based team offers a level of local proficiency that only comes from decades of active engagement in the community. We understand that behind every document is a family looking for a fresh start in Mountsorrel or a professional seeking a quiet retreat in Sileby.

Our role is to act as a reliable pillar of support throughout the entire transaction. Choosing a local, independent agent ensures you have a dedicated partner who communicates directly with your lender and solicitor to maintain momentum. This “steady hand” approach is designed to reduce client anxiety, providing clarity whilst you move from the initial application to the day you receive your keys. By being transparent about your financial readiness from the start, you allow us to advocate for you more effectively when presenting offers to vendors in competitive areas like Rothley or Anstey.

Start Your Search with Confidence

You can begin your search with complete confidence by browsing our current residential listings across Charnwood. We strongly recommend registering for our property alerts to ensure you’re the first to hear when a new home in Quorn or Barrow Upon Soar hits the market. Our team prides itself on proactive coordination, acting as the essential link between you, the seller, and the various professionals handling your move. This ensures that the hard work you put into gathering your financial paperwork translates into a successful and timely completion.

Get a Professional Valuation

For many Leicestershire residents, the next step involves selling a current home to fund their purchase. Understanding your available equity is a vital part of the mortgage application checklist UK, as it forms the foundation of your deposit and borrowing capacity. We provide expert, no-obligation property valuation services to give you an accurate, evidence-based figure for your financial planning. Knowing your home’s true value allows you to approach lenders with the confidence that your budget is realistic. Contact Taylors Estate Agency today for a friendly, honest chat about your future plans and how our independent boutique service can deliver the results you need.

Securing Your Future in Leicestershire

Taking the time to prepare your mortgage application checklist UK is the most effective way to ensure your journey to a new home in Charnwood is as smooth as possible. By organising your financial story before you begin viewing properties in Rothley or Quorn, you position yourself as a serious, qualified buyer ready to act when the right opportunity arises. This proactive approach doesn’t just satisfy the lender’s requirements; it gives you the confidence to make decisions based on clear, verified facts.

As independent local experts since 1992, we’ve spent decades becoming specialists in Rothley and Charnwood property. Our team provides friendly, honest advice from experienced agents who prioritise your peace of mind whilst handling the complexities of the 2026 market. We’re proud to act as a reliable pillar of the community, offering the steady hand and local proficiency needed to turn your moving plans into a reality.

Book a free property valuation with Taylors Estate Agency today

We look forward to helping you take the next step toward your dream home in our beautiful corner of Leicestershire.

Frequently Asked Questions

How long does a mortgage application take in the UK?

A mortgage application typically takes between two and six weeks to reach a formal offer stage, though this timeline depends on the complexity of your finances and the lender’s current workload. Providing a complete mortgage application checklist UK at the start can significantly speed up the process. Delays often occur when underwriters require additional clarification on bank statements or self-employed accounts, so being prepared from day one is essential for a smooth experience.

Can I apply for a mortgage if I have only been self-employed for one year?

Whilst most high-street lenders require at least two or three years of certified accounts, it’s possible to apply with only one year of self-employment through specialist providers. You’ll need a finalised SA302 and a Tax Year Overview from HMRC to prove your earnings. Lenders will scrutinise your previous employment history and the sustainability of your business, so having a qualified accountant to sign off your figures is highly recommended for buyers in Rothley or Quorn.

Do I need to provide bank statements for all my accounts?

Lenders generally require the last three to six months of statements for all active current accounts, especially those where your salary is paid and your outgoings are managed. If your deposit is held in a separate savings account, you must provide statements for that as well to prove the source of funds. Underwriters look for a clear, consistent money trail across all your financial holdings to ensure your reported disposable income is accurate and sustainable.

What is the difference between a Mortgage in Principle and a full application?

A Mortgage in Principle is an initial estimate from a lender indicating how much they might be willing to lend you based on basic information. It doesn’t involve a full credit check or a property valuation. A full application is the formal process triggered once you have an offer accepted on a home. This stage involves the detailed scrutiny of your mortgage application checklist UK and a professional assessment of the property you intend to buy in Leicestershire.

Will a gifted deposit affect my mortgage application?

A gifted deposit won’t negatively affect your application as long as it’s documented correctly with a signed gift letter. This letter must confirm the money is a gift, not a loan, and that the donor has no legal interest in the property. Lenders must also verify the donor’s identity and the source of their funds to comply with anti-money laundering regulations, which is a standard part of the process for buyers in Charnwood villages.

What happens if my passport has expired before I apply?

You cannot use an expired passport as your primary proof of identity for a mortgage application. Lenders require valid, current photocard identification to satisfy their security checks and regulatory requirements. If your passport has expired, you may be able to use a valid UK photocard driving licence instead. If you possess neither, you should prioritise renewing your passport before starting your application to avoid unnecessary delays in the home-buying process across Leicestershire.

Do I need to provide proof of my deposit if it is in a savings account?

Yes, you must provide bank statements for any savings account where your deposit is held. Lenders need to see the accumulation of funds to ensure the money has been saved legitimately over time or comes from a verified source like an inheritance. If the money was recently transferred from another account, be prepared to provide the statements for that account too, ensuring the entire trail is transparent and easy for the underwriter to follow.

How far back do lenders look at my bank statements?

Most UK lenders will ask to see your bank statements from the last three months, though some may request up to six months if your income is complex. They use this period to assess your typical spending habits and identify any regular financial commitments that could impact your ability to keep up with mortgage repayments. Maintaining clean statements during this window, with no returned payments or excessive overdraft use, is vital for a successful outcome when buying in Sileby.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager

Posted on

How Much Can I Borrow? 2026 UK Affordability Guide

How Much Can I Borrow? 2026 UK Affordability Guide

Why does one website tell you that you can afford a detached home in Quorn, while another suggests you’re limited to a small apartment in the city centre? It’s a common frustration because determining how much can I borrow mortgage UK has shifted from a simple salary calculation to a complex assessment of your daily lifestyle. You’ve likely spent hours on generic calculators only to end up more confused by conflicting results and the impact of the 3.75% Bank of England base rate on your monthly budget.

We understand that this uncertainty makes planning your move to Rothley or Mountsorrel feel like a guessing game. This guide breaks down the realistic factors lenders use in 2026, from the standard salary multiple rules to the way your credit history and monthly outgoings truly impact your capacity. We will explain how current interest rates affect your repayments and provide a clear roadmap to strengthen your financial profile. By the end, you’ll have the knowledge to start viewing properties in Charnwood with a budget that’s grounded in reality and professional insight.

Key Takeaways

  • Learn how lenders calculate how much can I borrow mortgage UK by moving beyond simple salary multiples to look at your specific lifestyle and monthly commitments.
  • Understand why your discretionary spending and credit history are just as important as your annual income when banks assess your affordability in 2026.
  • Identify the “sweet spot” for deposit sizes, typically between 10% and 15%, to secure more competitive interest rates and increase your overall borrowing power.
  • Discover practical steps to improve your financial profile before applying, such as ensuring you are on the electoral roll and managing your outgoings early.
  • See how matching your budget to specific Charnwood locations requires a deep understanding of local market values and moving costs, a speciality of Taylors Estate Agency.

Understanding the UK Mortgage Borrowing Landscape in 2026

The UK mortgage industry has evolved significantly over the last few years. While many buyers still start their journey by multiplying their gross annual income by 4 or 4.5, this is rarely the final figure. Lenders now use sophisticated algorithms to determine how much can I borrow mortgage UK, focusing on your ability to maintain payments even if life throws a curveball. The Financial Conduct Authority (FCA) oversees these standards to ensure lending remains responsible, preventing the market from returning to the risky practices of the past.

There is a vital distinction between what a bank is willing to lend and what you can comfortably afford each month. In 2026, with the Bank of England base rate sitting at 3.75%, your “paper” affordability might look different from your bank balance reality. A high salary is a great foundation, but it’s only one piece of the puzzle. We often see buyers in Rothley who are surprised that their maximum loan is lower than expected because of high commuter costs or existing financial commitments.

The Salary Multiple vs. Affordability Testing

Lenders prioritise residual income in their 2026 assessments. This is the money left over after you’ve paid for essentials like utilities, council tax in Charnwood, and groceries. Even if you earn a substantial wage, high childcare costs or significant personal debt will reduce your maximum loan. Banks also apply stress tests, calculating whether you could still manage repayments if interest rates were to climb several percentage points higher than your current deal. This ensures you won’t lose your home if the economic climate shifts during your fixed term.

How Your Employment Type Affects the Calculation

Your income’s stability is just as important as the total amount. Full-time PAYE employees usually have the simplest path, with lenders taking 100% of their basic salary into account. However, for those working in Leicestershire’s thriving self-employed sector or on fixed-term contracts, the rules are more nuanced. Following the FCA’s recent consultation on mortgage rules, some lenders now offer more flexibility for those with variable incomes. They may look at a two or three-year average of your accounts. Bonuses, commissions, and overtime are often shaded, meaning a bank might only count 50% to 80% of that income towards your total borrowing capacity.

Critical Factors That Influence Your Borrowing Capacity

Your borrowing capacity isn’t a static figure etched in stone. It’s a moving target shaped by what we call the “big three”: your income, your outgoings, and your credit score. When you ask how much can I borrow mortgage UK, you’re really asking how a lender views your financial reliability. Banks in 2026 are particularly focused on your debt-to-income ratio. This is a simple calculation of your monthly debt commitments against your gross earnings. If you have dependent children or existing financial commitments like car leases; these will naturally reduce your total borrowing power.

Lenders now scrutinise discretionary spending with a fine-tooth comb. They aren’t just looking at whether you can pay the mortgage today; but whether you can sustain it if life becomes more expensive. If you’re looking at homes in Rothley or Quorn; understanding these nuances early can save significant stress later. If you want to see how your current debts might change your outlook; a mortgage affordability calculator is a brilliant place to start your research.

The Role of Your Credit Profile

Your credit score is about more than just paying your bills on time. It’s a snapshot of your relationship with money. Lenders look for patterns; such as how much of your available credit you actually use. High credit card utilisation; even if you pay the minimum every month; suggests a reliance on debt that banks find off-putting. We recommend that buyers in Mountsorrel and Birstall organise their finances at least six months before starting their search. This means avoiding new credit applications; such as furniture finance or car loans; and keeping your balances low. If you’re wondering how your specific profile might affect your chances; send us a quick message for some honest local advice.

Assessing Your Monthly Expenditure

Lenders divide your bank statements into essential and non-essential costs. Essentials are the non-negotiables; student loans, car finance, and childcare costs. For many families in Charnwood; childcare is often the heaviest weight on an application. Then they look at your lifestyle choices. Discretionary spend is the primary lever for 2026 mortgage approvals. By reducing non-essential outgoings like premium subscriptions or frequent dining out in the months leading up to your application; you effectively increase your “paper” affordability. This demonstrates to the lender that you have the surplus income necessary to handle the 3.75% base rate environment comfortably.

Loan-to-Value (LTV) and Its Impact on Your Purchase

Loan-to-Value, or LTV, is the percentage of the property’s value that you are looking to borrow. If you are buying a home in Rothley for £400,000 and have a £40,000 deposit, your LTV is 90%. This figure is a critical component when calculating how much can I borrow mortgage UK because it determines which interest rate tiers you qualify for. Lenders view a lower LTV as a lower risk; which often results in more generous borrowing limits and cheaper monthly repayments.

In the 2026 market; the “sweet spot” for many buyers in Leicestershire is a 10% or 15% deposit. While the Freedom to Buy scheme has made 95% mortgages a permanent fixture; these high-LTV products usually come with higher interest rates to offset the lender’s risk. By reaching an 85% LTV; you often move into a different pricing bracket that can save you thousands of pounds over the life of your fixed term. Property valuations in sought-after areas like Mountsorrel are stable; but lenders will always base their final loan offer on their own surveyor’s valuation rather than the agreed purchase price.

How Deposit Size Changes Your Monthly Costs

The difference between a 95% and an 80% LTV mortgage is about more than just the initial cash you put down. A 95% mortgage might carry an interest rate significantly higher than the average 5-year fixed rate of 5.66%. Stepping up to an 80% LTV can unlock rates that are much closer to the base rate; drastically reducing your monthly outgoings. If you are planning to sell an existing property to fund your next move; it’s vital to get an accurate starting point. You can check how much is my house worth in Syston to understand how much equity you could potentially port over to your new purchase.

Property Types and Lender Restrictions in Leicestershire

The type of property you choose in Charnwood can also dictate your LTV requirements. Period properties in Quorn or Anstey are beautiful; but they often require more detailed surveys. If a property has non-standard construction; such as a thatched roof or timber frame; some lenders may reduce the maximum LTV they are willing to offer. They might even require a larger deposit to protect their security. The property itself acts as the final collateral for the loan; so if the building is considered high-maintenance or difficult to resell; it directly impacts the bank’s willingness to lend the full amount you’ve requested.

Practical Steps to Maximise Your Borrowing Power

Preparing for a mortgage application is a marathon; not a sprint. If you want to accurately determine how much can I borrow mortgage UK; you need to look at your finances through a lender’s eyes at least six months before you intend to buy. Start by ensuring you’re on the electoral roll at your current address. This is a simple but vital step for identity verification; as a lack of registration can lead to automatic rejections or frustrating delays that might cost you a property in a competitive village like Quorn or Woodhouse Eaves.

Gathering your documentation early is equally important for a smooth process. You’ll generally need your last three P60s and three months of bank statements to prove your income and spending habits. For the self-employed in Leicestershire; have your last two years of tax calculations (SA302s) and tax year overviews ready. Reducing existing debt before your search begins is also a primary lever; as it improves your debt-to-income ratio and increases your monthly disposable income. This proactive approach shows lenders you’re managing your finances responsibly. Having this data at your fingertips ensures your application is based on accurate; verifiable figures rather than estimates.

Financial preparation also involves a realistic look at your lifestyle. Lenders in 2026 are looking for stability and predictability. If you’ve recently changed jobs or have gaps in your employment history; be prepared to explain these clearly. By organising your finances well in advance; you position yourself as a low-risk borrower; which is essential for securing the most competitive rates in the Charnwood market.

Financial Housekeeping Before You Apply

Lenders prefer a “clean” financial history. Closing credit cards you don’t use reduces the total credit available to you; which banks see as a potential risk. Try to stay out of your overdraft for three months and avoid large purchases like new cars. These commitments appear as monthly outgoings; directly reducing your borrowing capacity. Maintaining transparent spending makes it much easier for an underwriter to approve your loan.

Contact our team for a personal consultation on your local property search

Securing a Decision in Principle (DIP)

A Decision in Principle (DIP) is an initial assessment confirming a lender’s willingness to lend a specific amount. While it isn’t a full mortgage offer; it shows sellers in Rothley or Anstey that you’re a prepared buyer. A DIP is the “currency of trust” when making an offer on a competitive property. It proves you’ve researched your budget and have the backing to move forward with confidence; which is vital in the 2026 market where how much can I borrow mortgage UK remains a key concern for many.

How Much Can I Borrow? 2026 UK Affordability Guide

Knowing your borrowing limit is the foundation; however, applying that figure to the Charnwood market is where the real work begins. A generic calculator won’t tell you that a budget stretching to a semi-detached in Birstall might secure a more spacious detached property in Sileby. We believe in a balanced approach where your financial capacity meets your lifestyle aspirations. It’s about more than just the mortgage; you must also account for the true cost of moving house in Leicestershire, including updated stamp duty thresholds and local surveyor fees.

When you finally determine how much can I borrow mortgage UK, the next step is matching that loan to the right postcode. This is where local expertise becomes your most valuable asset. We support our clients from the initial valuation through to the day they collect their keys; ensuring every decision is backed by evidence and 15 years of local market experience. Understanding how much can I borrow mortgage UK is only half the battle; the other half is knowing where that money goes furthest in the current landscape.

Why Local Knowledge Trumps Online Calculators

Online tools provide a rough estimate; but they lack the nuance of local market dynamics. For instance, some lenders are more cautious about specific property ages or construction types in villages like Barrow Upon Soar. An experienced agent understands these lender attitudes and can guide you toward homes more likely to pass a valuation survey without complications. We help you find the right balance between borrowing and the practical reality of maintaining a home in a specific neighbourhood. This ensures you don’t just buy a house; but a home you can afford to enjoy for years to come.

Starting Your Journey in Rothley

Our team has seen every common pitfall; from over-borrowing to missing out on properties due to a lack of preparation. We offer a “steady hand” approach; providing honest advice that prioritises your peace of mind. Whether you’re moving within Cropston or looking to settle in Thurcaston; we act as your guide through the entire process. If you have questions about specific village values or need a sounding board for your plans; you can get in touch via WhatsApp for personalised advice.

Taking Your Next Steps in the Charnwood Market

Determining how much can I borrow mortgage UK is a strategic look at your financial life through a lender’s eyes rather than a simple calculation. We have explored how 2026 affordability models prioritise your daily spending habits and how reaching specific deposit thresholds can significantly lower your monthly costs. By taking proactive steps to manage your credit and organise your documentation; you build a foundation of trust with potential lenders before you even step inside a property.

Since 1992; Taylors Estate Agency has acted as a trusted local guide for buyers across Rothley and the wider Charnwood area. Our independent status and 15 years of professional experience mean we offer honest; practical advice tailored to the villages we know so well. We are committed to helping you find a balance between your borrowing capacity and the lifestyle you want to lead in Leicestershire.

Ask our local experts for honest mortgage advice on WhatsApp

We are here to provide the steady hand you need to move forward with confidence. Your journey toward a new home starts with clear; evidence-based planning and a partner who understands the local landscape.

Frequently Asked Questions

Is the 4.5 times salary rule still accurate for UK mortgages in 2026?

The 4.5 times salary rule remains a standard benchmark for the UK mortgage industry in 2026; however; it is no longer the sole deciding factor. While many lenders use this as a baseline; others may offer up to 5.5 times your income if you have a high salary or minimal outgoings. Your final offer depends heavily on detailed affordability stress tests that look at your net income after all essential living costs are deducted.

Can I borrow more if I have a larger deposit?

A larger deposit improves your Loan-to-Value (LTV) ratio; which often unlocks more competitive interest rates. While a bigger deposit doesn’t automatically increase the multiple of your salary you can borrow; lower interest rates reduce your monthly repayment costs. This can lead to a more favourable affordability assessment; potentially allowing you to secure a slightly larger loan because the monthly commitment is more manageable for your household budget.

How do my monthly outgoings affect my mortgage borrowing amount?

Your monthly outgoings are subtracted from your take-home pay to determine your “residual income.” Lenders scrutinise everything from car finance and student loans to childcare costs and regular subscriptions. If your fixed monthly commitments are high; the amount you can borrow will decrease; as the lender must ensure you have enough surplus cash to cover your mortgage payments even if interest rates were to rise during your term.

Will being self-employed reduce how much I can borrow?

Being self-employed doesn’t inherently reduce your borrowing capacity; provided you can supply two to three years of certified accounts or SA302 forms. Lenders typically average your net profit over this period to determine your income. Some specialist lenders are now more flexible for those with only one year of trading; though they may require a larger deposit to offset the perceived risk of a variable or recently established income.

Does a student loan impact my mortgage affordability?

Yes; student loan repayments are treated as a monthly commitment that reduces your net take-home pay. When calculating how much can I borrow mortgage UK; lenders factor in these deductions just like any other debt or tax. While a student loan won’t prevent you from getting a mortgage; it will slightly lower the maximum loan amount available to you because it reduces the total disposable income you have available for repayments.

How much can I borrow if I am buying with a partner?

When buying with a partner; lenders typically combine your gross annual incomes and apply a multiple; usually between 4 and 4.5 times the total. This significantly increases your borrowing power compared to a single application. Both applicants undergo the same rigorous credit checks and expenditure assessments; so high debts or poor credit history from one partner can still impact the overall amount the lender is willing to offer for your joint purchase.

What happens if the property valuation is lower than my mortgage offer?

If a lender’s valuation comes in lower than your agreed purchase price; they will only lend based on that lower figure. This is known as a “down valuation.” In this scenario; you would need to increase your deposit to cover the shortfall or renegotiate the price with the seller. This is why understanding local market values in areas like Rothley or Quorn is vital before making an offer on a home.

Should I use an online mortgage calculator before viewing houses?

An online how much can I borrow mortgage UK calculator is a helpful starting point for a rough estimate; but it shouldn’t be your final word. These tools often miss the nuances of 2026 lender behaviour and your specific outgoings. We recommend obtaining a Decision in Principle (DIP) before viewing properties in Charnwood; as this provides a more accurate reflection of your actual budget and demonstrates your serious intent to sellers.

Sam Cable - Branch Manager

Article by

Sam Cable – Branch Manager